Tax Advisors in Portugal
Tax advisors in Portugal help people and businesses establish their Portuguese tax residence and prepare the AT filing for each tax year. We classify Portuguese and foreign income under the CIRS and calculate any foreign tax credit.
First conversation free Reply within one business day
Who Needs a Tax Advisor in Portugal
- You need to establish your Portuguese tax residence for a year that includes time or a home in Portugal.
- You receive Portuguese and foreign income and need the residence, source and reporting rules applied together.
- You paid foreign tax and need the credit limit and the relevant bilateral treaty checked for each income stream.
- You need Portuguese tax planning or return support that involves investments, property, company interests or more than one country.
Tax compliance work does not include complaints, appeals or other disputes with the tax authority.
What's Included in Tax Compliance Work
You get a quote in writing before any work starts.
- Residence analysis. A certified accountant applies Articles 15 and 16 of the CIRS to your days, homes and other residence facts for the relevant period.
- Income and rate review. A certified accountant classifies the agreed income and applies the relevant general, special or other statutory treatment.
- Foreign-tax-credit analysis. A certified accountant matches the foreign income and tax paid to the credit limits in Article 81 of the CIRS.
- Treaty review. A certified accountant identifies the relevant residence state, source state, income article, taxing rights and double-tax-relief method.
- Return preparation and filing. A certified accountant prepares the agreed Portuguese return and supporting schedules for electronic filing with AT.
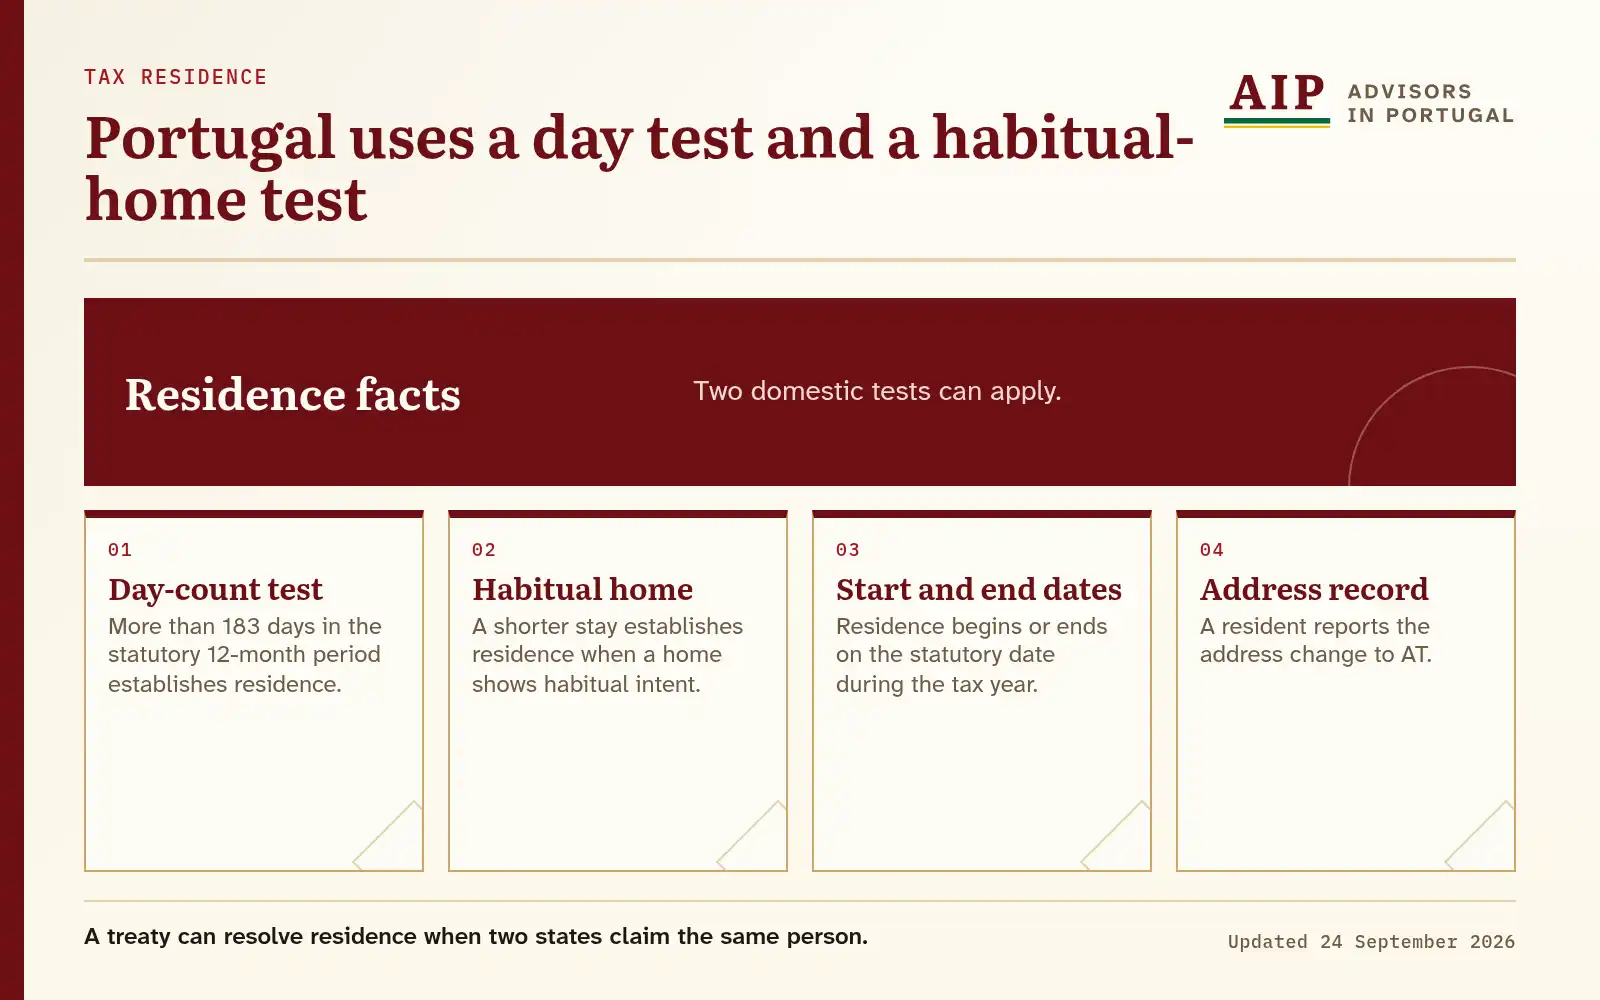
Diagram text version
More than 183 days in the statutory 12-month period establishes residence. A shorter stay establishes residence when a home shows habitual intent. Residence begins or ends on the statutory date during the tax year. A resident reports the address change to AT.
What You'll Need to Provide
- Residence timeline
- Your days in Portugal and other countries, homes available to you, household facts and changes of fiscal address.
- Income records
- Portuguese and foreign employment, pension, business, property, investment and other income records within the engagement.
- Foreign tax evidence
- Assessments, payment records, withholding certificates and returns showing the foreign tax connected with each income stream.
- Asset and transaction records
- The ownership, acquisition, disposal and income documents for property, investments and company interests under review.
- Treaty facts
- The residence and source countries, income type, payer details and any residence certificate or treaty form already obtained.
- Prior Portuguese filings
- Portuguese returns, AT assessments, notices, payments and correspondence for the relevant periods.
How Tax Compliance Work Proceeds
A certified accountant prepares the agreed IRS return for electronic filing with the Autoridade Tributária e Aduaneira and flags accounting, investment and cross-border questions along the way.
-
Establishing the Tax Year and Residence Facts
A certified accountant records the relevant period, travel days, homes, household circumstances and fiscal-address history.
-
Classifying Portuguese and Foreign Income
A certified accountant maps each income stream to its source, CIRS category and supporting evidence.
-
Applying the IRS Treatment
A certified accountant applies the relevant brackets, special rates and aggregation rules to the documented income.
-
Calculating Foreign Tax Credits
A certified accountant compares the foreign tax paid with the Portuguese credit limit for each income stream.
-
Checking the Applicable Treaty
A certified accountant reviews the bilateral convention for the residence state, source state, income article and relief method.
-
Preparing the AT Filing
A certified accountant prepares the agreed return and evidence schedule for electronic filing with the Autoridade Tributária e Aduaneira.
Timing and Possible Delays
Set by the tax year and filing calendar
The work is planned around the Model 3 filing period in Article 60 of the CIRS and AT guidance, which runs from 1 April through 30 June for taxpayers who must file the annual return.
What delays it
More time is needed when travel dates, foreign income statements, tax-payment evidence, treaty certificates, transaction records or prior AT filings are incomplete.
What to prepare now
Your residence, income, foreign-tax, asset, treaty and prior-filing records should be organised by tax year before the work begins.
Tax Advisors by Location
The Modelo 3 return is filed on the Portal das Finanças wherever you live. The Serviço de Finanças competent for your taxpayer address handles any assessment or refund that needs an office.
Lisbon
A certified accountant handles residence analysis, your Portuguese IRS return, foreign income, double-tax credits, rental and capital-gains reporting and the payment calendar for a Lisbon taxpayer.
The assessment and refund dates and the questions for the Serviço de Finanças competent for your address are recorded.
Cascais
A certified accountant handles Cascais residence analysis, your Portuguese IRS return, foreign income, double-tax credits and property income.
The Serviço de Finanças competent for your Cascais address is identified when an office visit is needed.
Residence, Foreign Income and Filing Records
The residence evidence file
You separate travel, home and household evidence by tax year before a certified accountant applies Article 16 of the CIRS. A certified accountant reconciles passports, travel records, leases, ownership documents, utility records and fiscal-address changes.
The foreign-income and tax-credit schedule
A certified accountant creates one line for each income stream, source country, gross amount, foreign tax, payment date and supporting certificate. The accountant then maps the line to the relevant CIRS category and treaty article before calculating the Article 81 credit limit.
The return and evidence sequence
A certified accountant first reconciles the Portuguese and foreign records to the tax year. A certified accountant then resolves the residence, classification, treaty and credit questions, and prepares the Model 3 return and annexes from that completed evidence file.
Set out your Portuguese tax position
Describe where you lived, which income and assets you hold, where tax was paid and which Portuguese filings already exist.
Common questions
When am I tax resident in Portugal?
Does a Portuguese tax resident report foreign income?
What are the general Portuguese IRS brackets for 2026?
Can I claim credit for foreign tax paid?
How does a double-tax treaty affect my return?
Who can represent me when a legal issue is raised before AT?
What can a certified accountant handle?
How much does a tax adviser in Portugal cost?
How is Portuguese tax work handled?
Does one address determine Portuguese tax residence?
How the Service Works
-
One team for the whole case.
One team runs the case and brings in certified accountants and other independent professionals as your tax, investment and cross-border questions require.
-
English or Portuguese.
English or Portuguese, whichever you are most comfortable in.
-
A quote in writing before work starts.
You get a quote in writing before any work starts. A case outside the service is flagged plainly.
Contact us
Your request is in
Every request is read in house. The requirements are assessed, and a reply by email sets out the appropriate next steps.
Every enquiry is read in house, and the aim is a reply within one business day.
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.