Exit Tax in Portugal: When Article 10-A Applies
Exit tax in Portugal under CIRS Article 10-A can bring a qualifying shareholder's deferred capital gain into the year they cease to be Portuguese resident. A charge arises only where an earlier tax-neutral transaction, such as a share exchange or merger, deferred that gain.
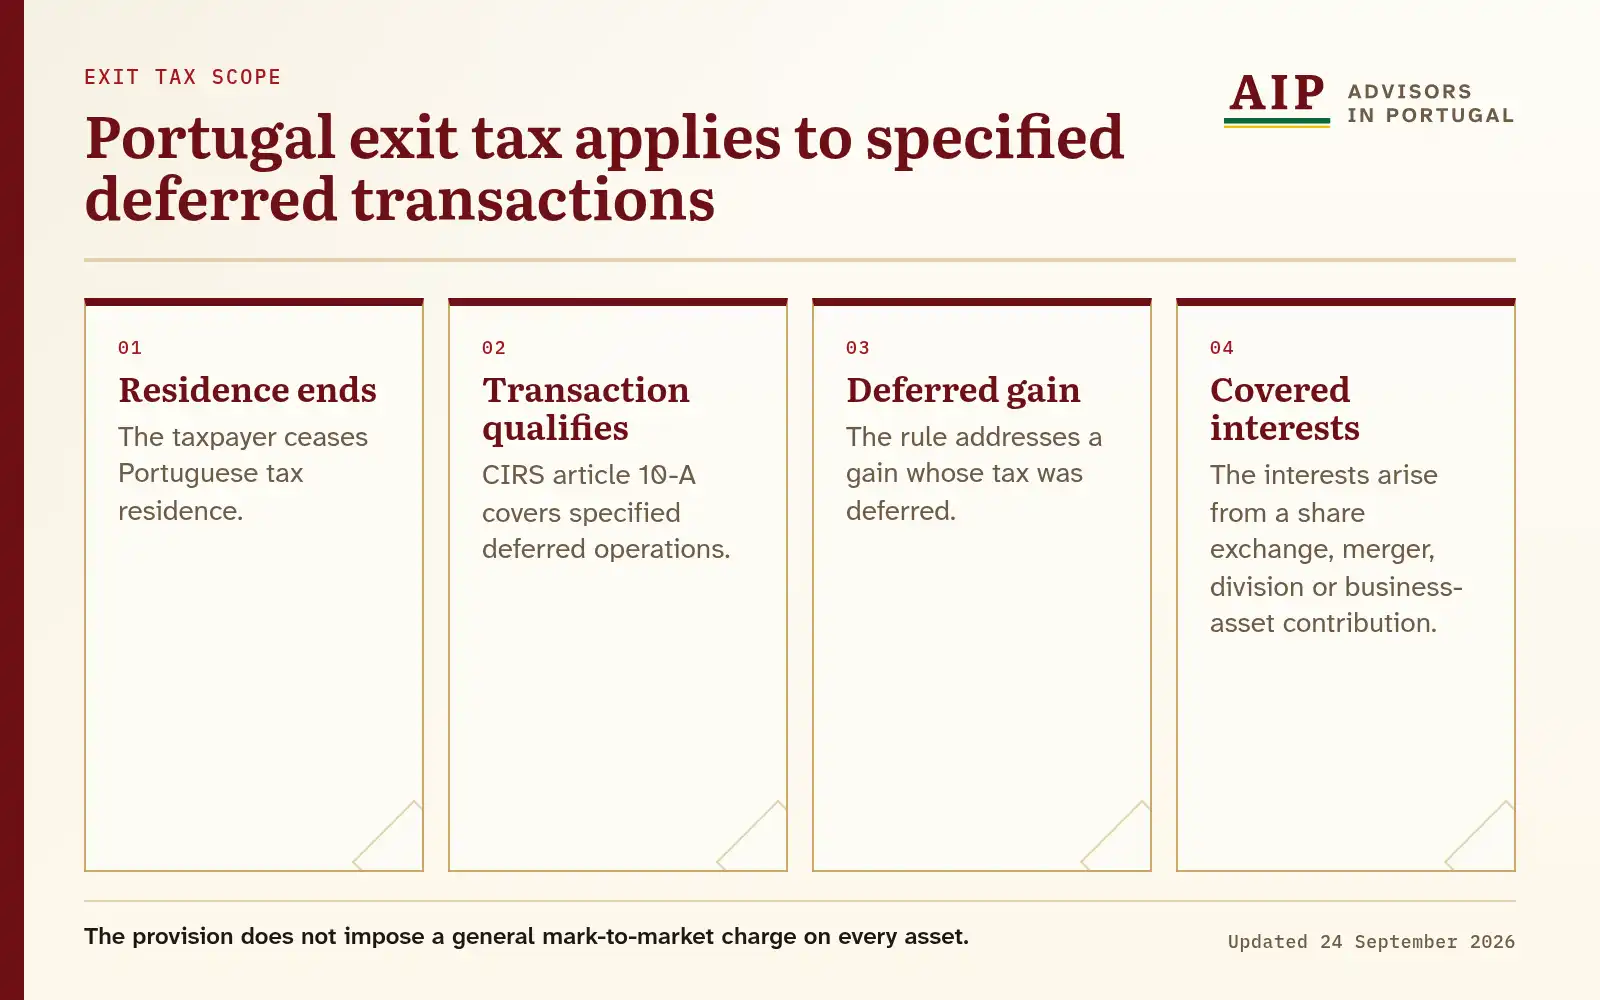
Diagram text version
The taxpayer ceases Portuguese tax residence. CIRS article 10-A covers specified deferred operations. The rule addresses a gain whose tax was deferred. The interests arise from a share exchange, merger, division or business-asset contribution.
You should identify the statutory category, relevant dates and supporting records before acting. This guide explains when a departure from Portugal can trigger CIRS Article 10-A, how the deferred gain is valued and which EU or EEA payment choices exist.
What is Portugal’s individual exit-tax rule?
CIRS Article 10-A(1), headed Perda da qualidade de residente em território português, brings certain previously untaxed amounts into capital gains when a shareholder loses Portuguese residence. It reaches amounts connected with the tax-neutral transactions cross-referenced in Article 10(8)-(9) and Article 38. You should identify the earlier transaction before calculating a departure charge.
Its trigger is the combination of a qualifying earlier transaction, a capital interest and loss of resident status. The transaction documents and the sequence of tax returns show whether a gain was deferred under a cross-referenced rule.
You should collect the original acquisition records, documents from the share exchange or other restructuring, the interests held after the transaction and the planned departure date. Each interest then maps to the relevant paragraph of Article 10-A.
Which earlier transactions matter?
CIRS Article 10-A(1) names Article 10(8)-(9) and Article 38. Those cross-references concern specified tax-neutral share exchanges, mergers, divisions and business-asset contributions for company capital. The deferred amount arises from the transaction that supplied or changed the capital interests, not from departure alone.
You should identify the company, the old interests, the new interests and the legal steps in the transaction. That sequence can be compared with the earlier tax treatment. A transaction described informally as a restructuring needs its actual legal documents to locate the applicable paragraph.
The rule concerns capital interests connected with the listed transactions. The relevant capital interests are separate from property and other holdings whose tax treatment rests on different provisions. That distinction determines what belongs in an Article 10-A computation.
When does Portuguese tax residence end?
CIRS Article 16(1)(a) treats a person as resident after more than 183 days in Portugal, consecutive or not, in a 12-month period beginning or ending in the relevant year. Article 16(1)(b) provides an alternative test where a home available in Portugal shows a present intention to keep and occupy it as habitual residence. Article 16(4) normally ends residence on the last day of presence.
You should reconstruct actual days in Portugal and the facts about any available home. Both Article 16 tests apply to the departure year, and the result identifies the year in which Article 10-A could recognise a gain. The date of a flight, a lease ending and a foreign registration may each be evidence, but the statutory tests govern the Portuguese conclusion.
The residence result controls the timing of the gain and the income-tax return. You should preserve travel records and home documents with the restructuring papers. A bilateral treaty can affect residence or taxing rights separately from the domestic residence test.
Which assets enter the departure calculation?
CIRS Article 10-A(1)(a)-(c) measures the deferred gain by reference to capital interests received or held through the listed transactions. Shares or quotas from a qualifying share exchange, merger, division or business contribution may therefore be relevant.
You should trace each old interest to the interest held at departure. Whether an interest was sold or otherwise extinguished before or after the move matters, because those events can affect the payment route under Article 10-A(3). The transaction file should show what was exchanged and what was received.
A group may have several companies or classes of interest. You should avoid rolling their values into one undifferentiated estimate. A record for each capital interest should be linked to the applicable Article 10-A benchmark. That record supports both the capital-gain calculation and any later declaration.
How is the deferred gain valued?
CIRS Article 10-A(1)(a) uses the difference between the market value of capital interests received and the acquisition value of the old interests for the specified share-exchange cases. Article 10-A(1)(b)-(c) uses the real value of interests and the acquisition or value benchmark stated for the other listed transactions. You should identify the correct subparagraph before choosing figures.
The calculation needs acquisition documents, exchange terms and the evidence for the market or real value required by the chosen provision. The old acquisition value and the value of the received interest are different inputs. A calculation that omits the prior tax-neutral step can misstate the amount brought forward at departure.
Article 10-A makes the amount a capital gain in the year residence is lost. The applicable IRS rate and result follow from the wider tax facts once the Article 10-A gain and year have been established.
Which payment choices follow an EU or EEA move?
CIRS Article 10-A(3) offers three choices when residence transfers to an EU Member State or an EEA state bound by equivalent administrative tax cooperation: immediate payment, payment in the following year when each identified interest is extinguished or transferred, or five equal annual instalments. The instalments each equal one fifth of the tax calculated in the departure year.
You should include the statutory interest consequence when comparing payment choices. You should compare the cash consequences of the available options with the expected holding period of each relevant interest. The destination must meet the statutory condition, and EU or EEA geography alone does not answer the cooperation element for an EEA state.
The payment choice concerns tax on the Article 10-A gain. The destination and any applicable treaty come into play after the Portuguese statutory calculation is prepared.
When must you elect and report?
CIRS Article 10-A(5) requires the election in the income-tax return for the year residence is lost and a declaration listing the affected capital interests by 31 August of the following year when deferred or instalment payment is elected. You should record both filing dates in the departure file.
Article 10-A(6)-(7) contains the continuing information duties for the chosen payment route. Which continuing declaration applies depends on the chosen payment method and the holdings. You should preserve evidence of each filing and later transfer of a listed interest.
The return election and the capital-interests declaration serve different purposes. You should keep copies of both with the valuation work. A later disposal should be matched to the same interest identified at departure so the payment event can be recorded accurately.
How does a treaty affect the result?
CIRS Article 10-A(3) sets the EU or qualifying EEA destination condition for deferred-payment choices. You should examine treaty residence and taxing rights separately. You should identify the destination state and any treaty separately from the domestic payment election.
The Portuguese residence conclusion under CIRS Article 16 is compared with the treaty residence provisions, and the treaty treatment of the relevant gain follows. The treaty question depends on the actual agreement and the type of interest involved. A domestic classification under Article 10-A is only one part of that analysis.
You should keep the treaty analysis connected to the departure-year return, especially where a foreign residence claim starts at a different time from the Portuguese domestic conclusion. The dates and source of each residence position should be documented.
Did a 2025 or 2026 change alter this rule?
The AT legislative history for CIRS Article 10-A records its enactment and a later amendment. You should apply the current text to the transaction and departure year and not assume a new general departure tax was introduced.
You should keep a personal shareholder’s Article 10-A question separate from a company’s own tax position, even where the same group transaction generated both files.
The original restructuring, the end of residence and each subsequent event affecting the interests each need a date. Those dates allow the correct version of the rule and the correct return year to be established. The source history is a chronology, not a substitute for the transaction documents.
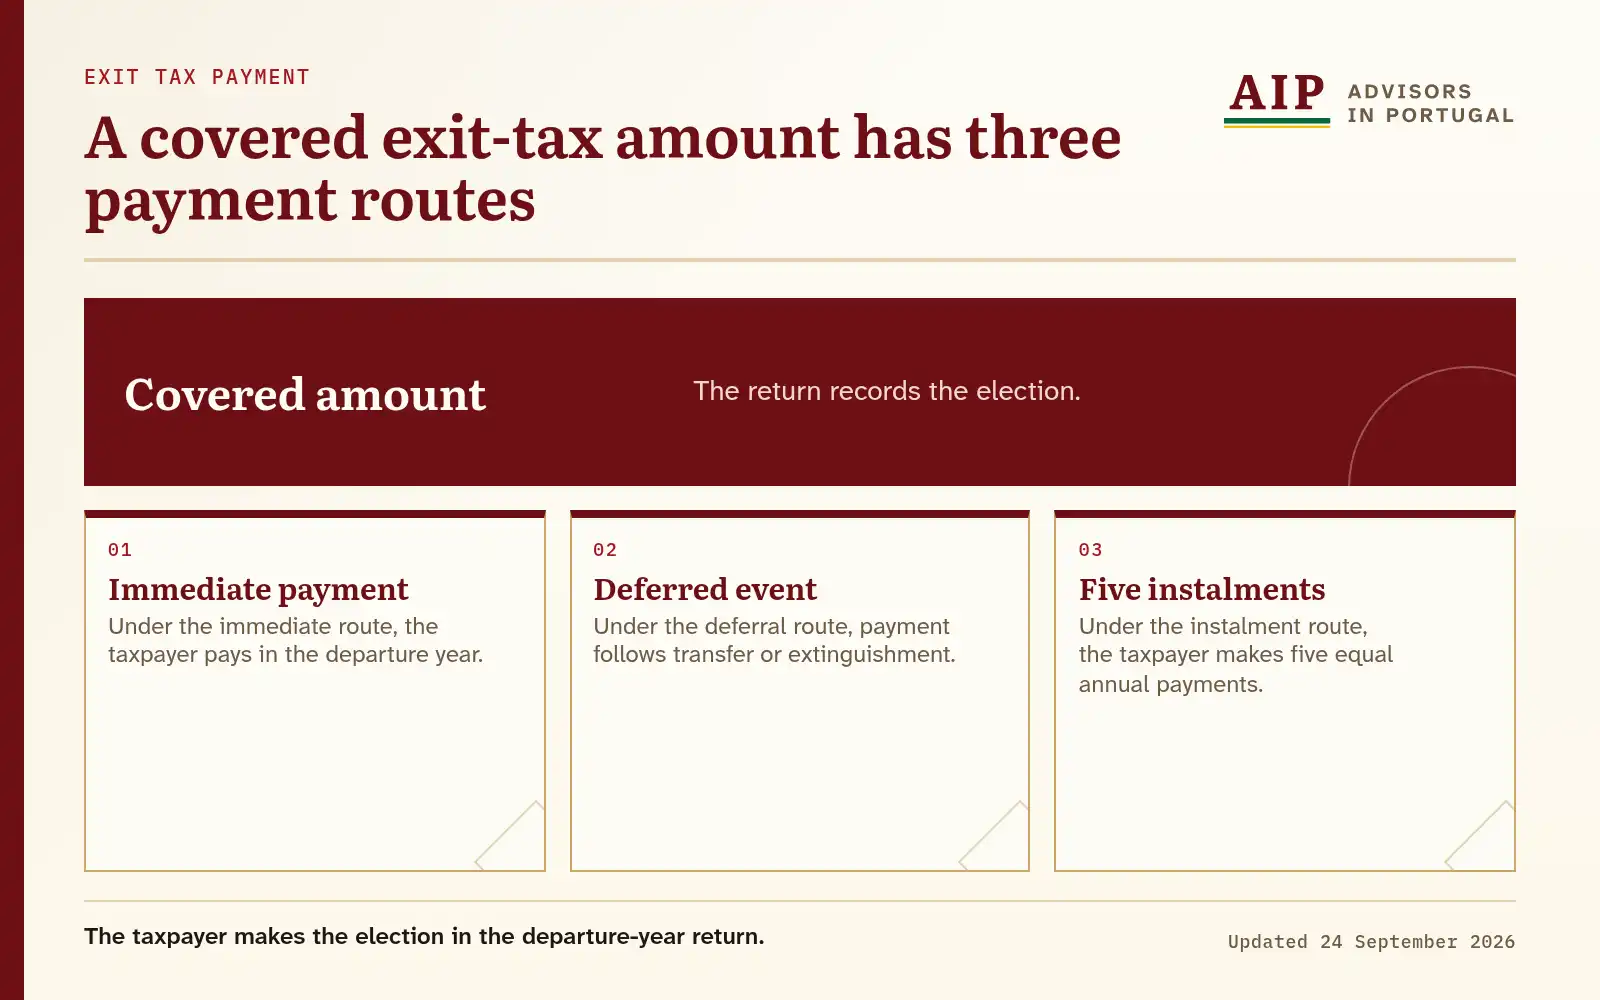
Diagram text version
Under the immediate route, the taxpayer pays in the departure year. Under the deferral route, payment follows transfer or extinguishment. Under the instalment route, the taxpayer makes five equal annual payments.
Common questions
Does Article 10-A set a flat exit-tax rate?
When is the annual electronic report due?
Does the five-instalment choice avoid interest?
What is the date for the capital-interests declaration?
Which separate article addresses a company exit?
Which law introduced this individual rule?
Related guides
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.