Mortgage Brokers in Portugal
Mortgage broker support in Portugal helps buyers who live outside the country prepare their borrower file for a Portuguese home purchase. We check the credit intermediary's Banco de Portugal registration and set out the costs in each FINE side by side.
First conversation free Reply within one business day
Who Needs Mortgage Broker Support in Portugal
- You are buying a Portuguese home and need the borrowing documents organized before applying.
- You live outside Portugal and want to understand what income and expense records a lender may request.
- You have received mortgage offers and need the FINE, charges and conditions set side by side.
- You are refinancing and need the early-repayment charges in the existing contract located.
A loan, a creditworthiness decision and a promise of lender approval or lending terms are outside the offer.
What's Included in Mortgage Support
The service helps you prepare the borrower file and tabulate the figures in the regulated offer documents.
- Intermediary register check. The Banco de Portugal entry and the intermediary's category and disclosed services are checked.
- Borrower file. A specialist organizes identity, income, expense, existing-debt and property information for the lender's assessment.
- Offer comparison. The comparison sets out the rate structure, annual percentage rate of charge and disclosed costs from each Ficha de Informação Normalizada Europeia (FINE) side by side.
- Fee comparison. The fee comparison separates intermediary remuneration from lender charges and lists the early-repayment charge shown in the credit offer or lender tariff.
- Property steps. The list covers the valuation, mortgage instrument, insurance and land-registry steps that affect the purchase.
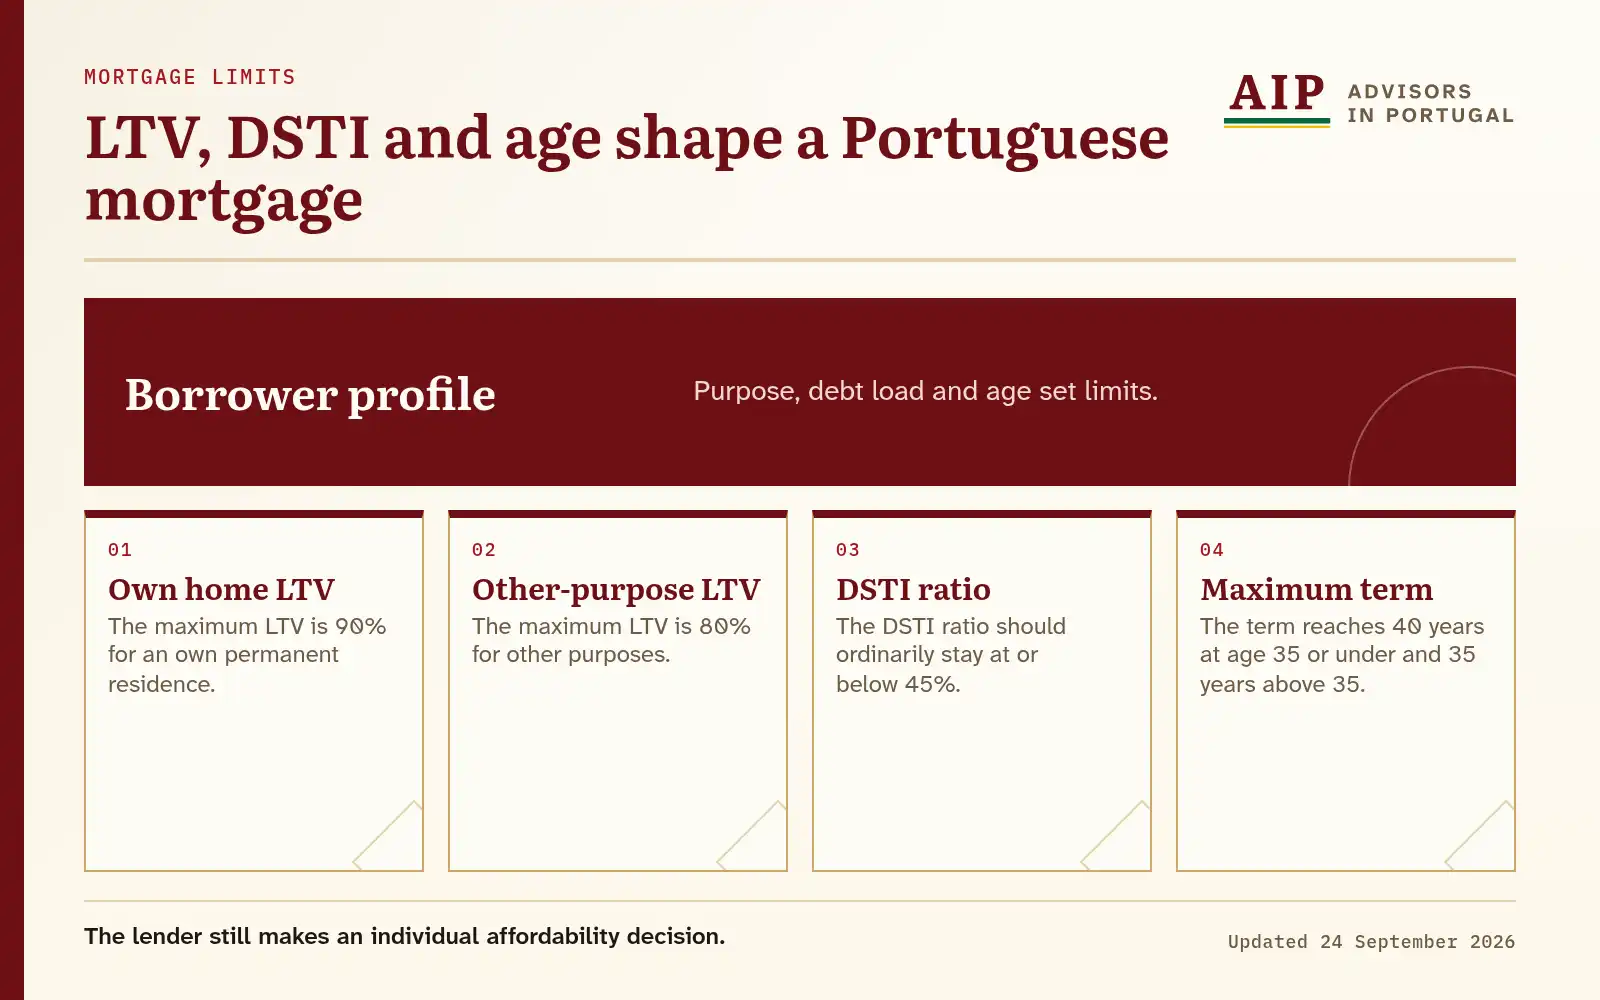
Diagram text version
The maximum LTV is 90% for an own permanent residence. The maximum LTV is 80% for other purposes. The DSTI ratio should ordinarily stay at or below 45%. The term reaches 40 years at age 35 or under and 35 years above 35.
What You Need to Provide
- Personal and residence details
- Identification, tax numbers, current residence and the people who will borrow or own the property.
- Income and expenses
- Recent income evidence, recurring expenses, existing debts and employment or business records.
- Property information
- Price, address, property documents, proposed deposit and any promissory contract.
- Existing credit documents
- Current mortgage contract, repayment statement or lender offer if you are refinancing or comparing proposals.
- Purchase dates
- The dates in the promissory contract and any known valuation or completion conditions.
How a Mortgage Application Proceeds
A specialist checks the intermediary's Banco de Portugal registration and prepares the borrower information for the lender. The valuation, title and land-registry steps are set out in the section on offer and property documents below.
-
Check the intermediary's authorisation
The Banco de Portugal register and the disclosed category are checked before an application.
-
Prepare income and property evidence
A specialist organizes the information the lender needs to assess affordability and the property.
-
Read the lender's FINE
The rate, APRC and disclosed costs from each FINE are set side by side.
-
Plan the reflection period
You consider the proposal during the statutory period before accepting a mortgage contract.
-
Address valuation and mortgage registration
The documents for the property valuation, mortgage instrument and land-registry entry are tracked.
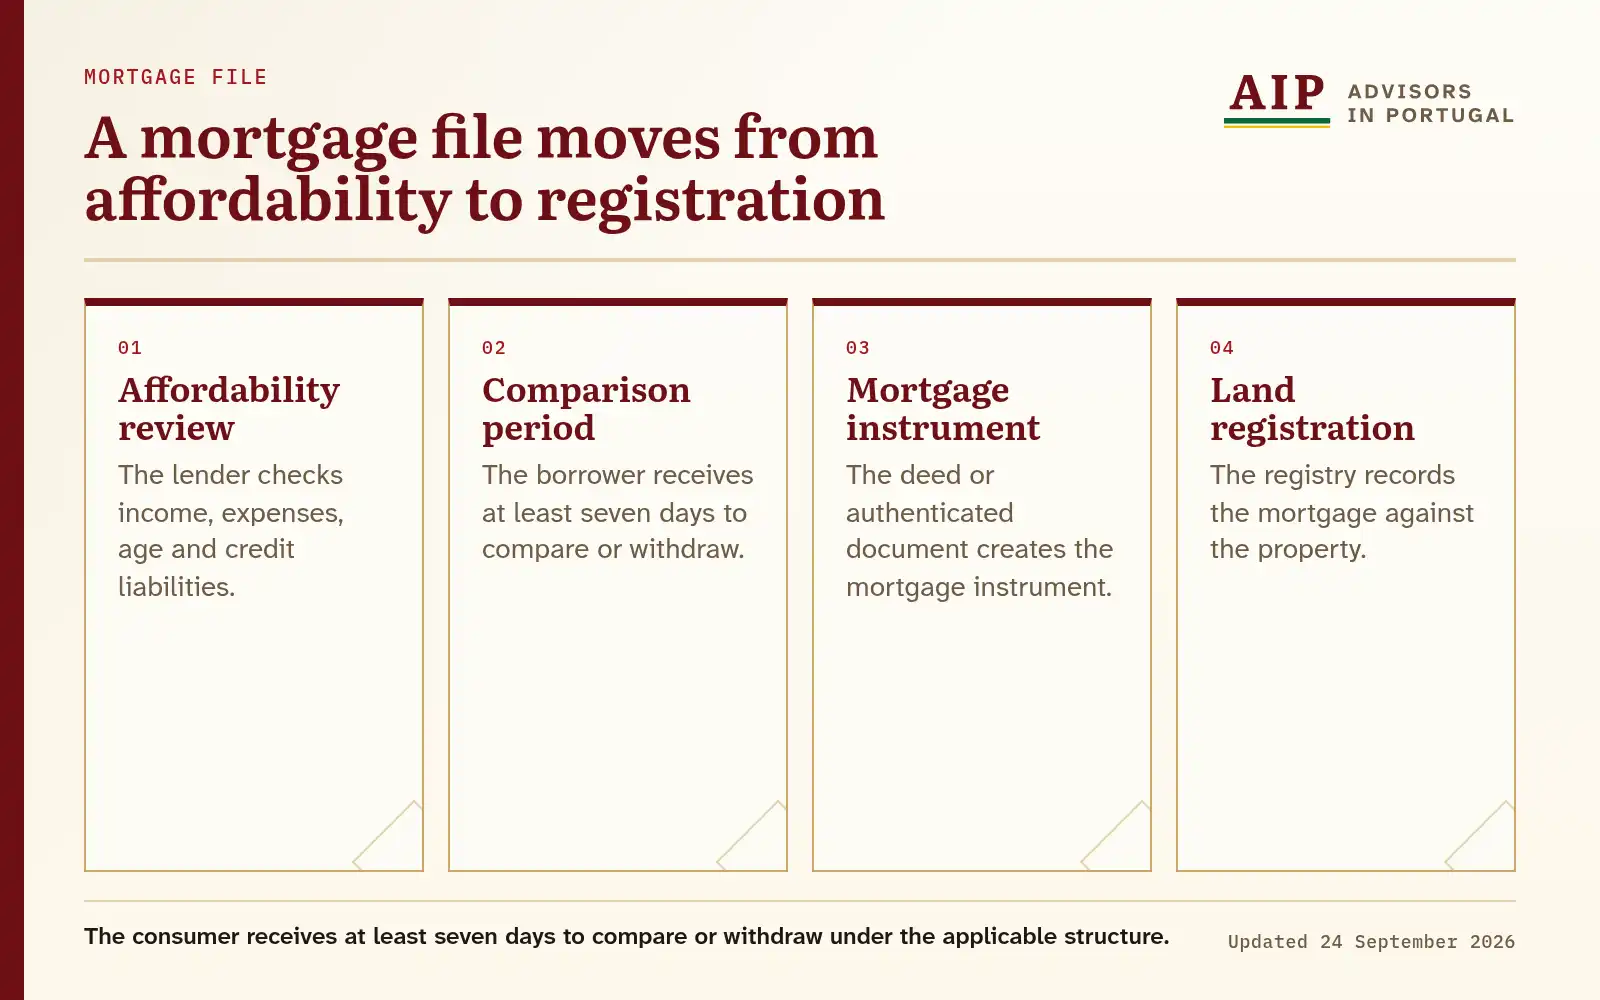
Diagram text version
The lender checks income, expenses, age and credit liabilities. The borrower receives at least seven days to compare or withdraw. The deed or authenticated document creates the mortgage instrument. The registry records the mortgage against the property.
Timing and Possible Delays
Set by the lender and property steps
The document preparation is planned around the purchase contract, lender assessment and statutory reflection period.
What delays it
More time is needed when income evidence is incomplete, the valuation raises questions or title and mortgage documents need correction.
What to prepare now
Your income, debt, property and purchase-date documents are requested before the lender application.
Mortgage Support by Location
Credit intermediaries are authorised and registered nationally with Banco de Portugal under Decreto-Lei n.º 81-C/2017, so the same register check applies wherever the property is.
Lisbon
Mortgage-broker support for Lisbon property purchases includes intermediary-register checks, borrower files, lender offers, valuation questions and completion documents.
Mortgage registration follows the deed or authenticated document, the land-registry route and the dates agreed in the transaction.
Offer and Property Documents
Offer details and purchase papers
You compare the property price, borrower names and intended use in the FINE with the promissory contract and supporting records. You should resolve inconsistent details before signing because the lender evaluates the property and borrower on the information supplied.
Keep valuation and title records separate
The registry extract shows the encumbrances on the property, and the lender arranges its valuation separately. You should place the registry extract and valuation report beside the lender’s completion conditions before signing the final documents.
Prepare the mortgage instrument
A specialist lists which deed or authenticated-document route the transaction uses and the lender’s completion conditions. You should retain the executed instrument and registration evidence with the purchase file after completion.
Explain your property and financing plan
State the price, proposed borrowing, residence and any purchase deadline already agreed.
Common questions
Must a mortgage intermediary be registered in Portugal?
Who decides whether I can borrow?
What is a FINE?
How long must I wait before accepting a mortgage offer?
Can a tied mortgage intermediary charge me?
Where can I check early-repayment charges?
Does a property valuation settle title to the property?
Who registers the mortgage?
How long does mortgage completion take?
How is mortgage support handled?
How the Service Works
-
One team for the whole case.
One team handles the finance, property and tax preparation that arises in the same purchase.
-
English or Portuguese.
English or Portuguese, whichever you are most comfortable in.
-
A written quote before work starts.
You get a quote in writing before any work starts. Fees are set case by case. A case outside the service is flagged plainly.
Contact us
Your request is in
Every request is read in house. The requirements are assessed, and a reply by email sets out the appropriate next steps.
Every enquiry is read in house, and the aim is a reply within one business day.
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.