Fiscal Representation in Portugal
Fiscal representation in Portugal gives non-residents with income subject to Portuguese IRS a Portugal-based representative for their dealings with the Autoridade Tributária e Aduaneira. We prepare the AT appointment record and the representative's express acceptance in English or Portuguese.
First conversation free Reply within one business day
Who Needs Fiscal Representation in Portugal
- You live outside the EU or a qualifying EEA state and have established a Portuguese tax relationship.
- You receive income subject to Portuguese IRS while you are non-resident, and the CIRS representation duty may apply.
- You are leaving Portugal for an extended period, and the CIRS representation rule may apply.
- You carry on taxable Portuguese operations and need the separate VAT-representation records prepared before activity begins.
You may not need a representative if you are eligible for and join a dematerialised-notification channel under Decreto-Lei n.º 44/2022.
What's Included in Fiscal Representation
You get a quote in writing before any work starts.
- Requirement checklist. The checklist sets out the CIRS and LGT representation rules with the facts they refer to: residence country, Portuguese income, absence and tax relationship.
- Appointment and acceptance. A specialist prepares the AT appointment record and the representative's express acceptance.
- NIF and address records. The taxpayer number, fiscal domicile and address information in the engagement are checked for completeness and consistency.
- Notification-channel information. The list names the eligible dematerialised-notification routes with the records each one needs.
- Tax duties within the mandate. A certified accountant handles the agreed notifications, accessory duties and tax filings within the powers granted.
- VAT representation records. Records for the separate CIVA Article 30 status are prepared where your Portuguese activity requires a VAT representative.
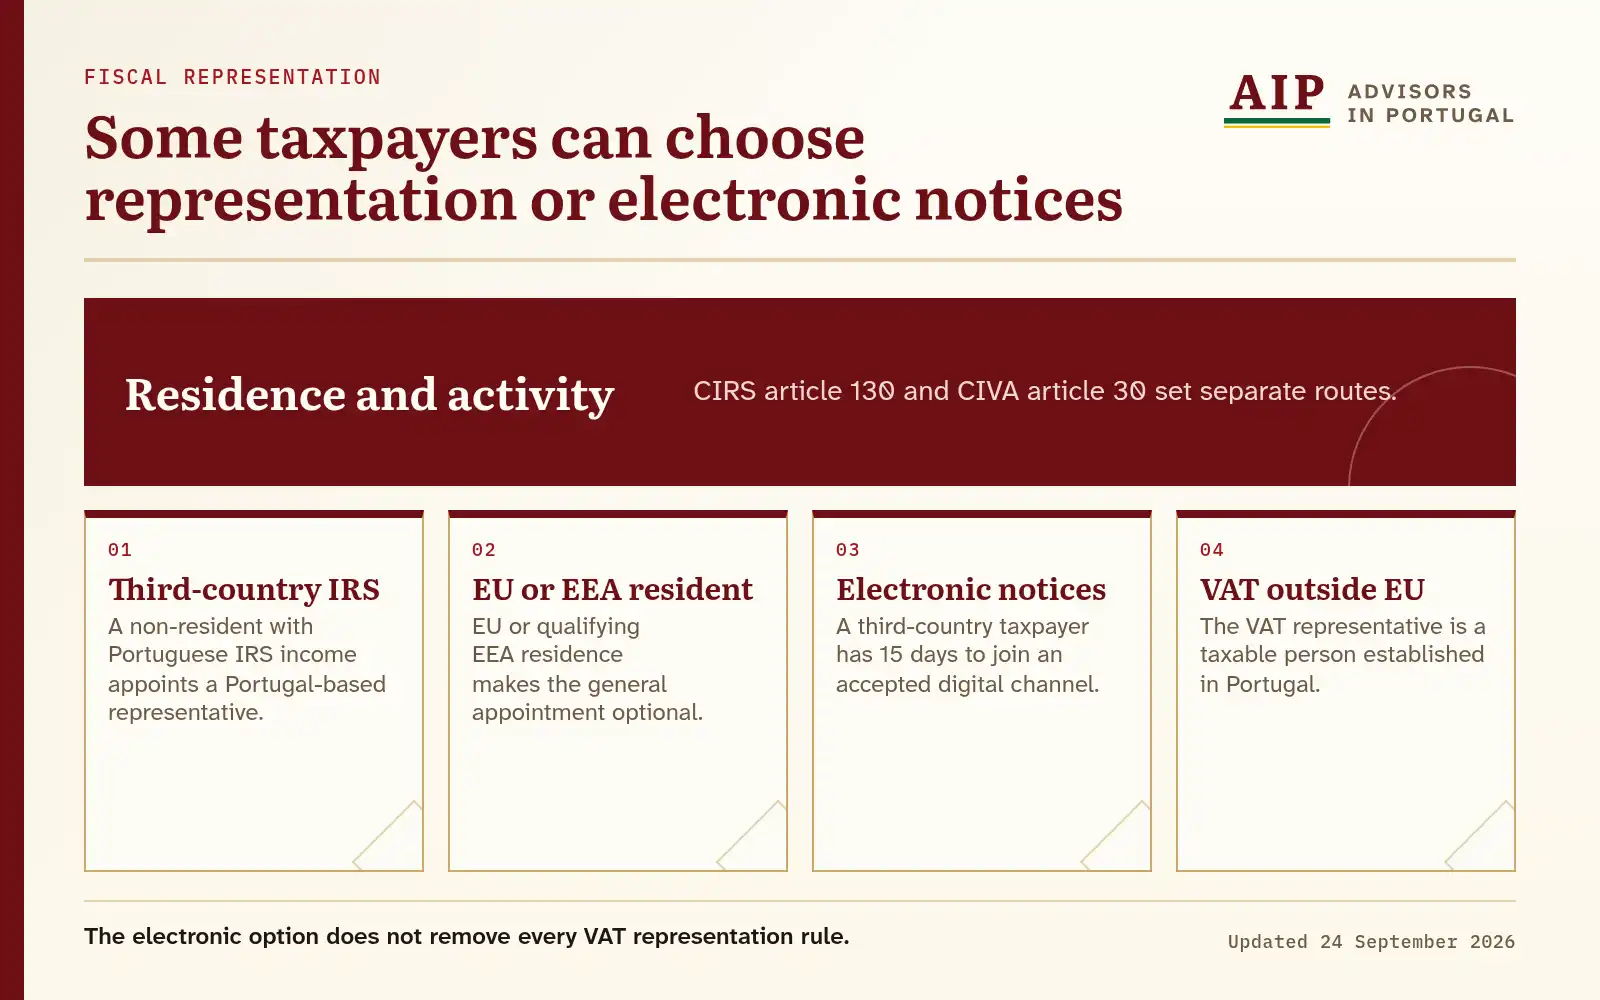
Diagram text version
A non-resident with Portuguese IRS income appoints a Portugal-based representative. EU or qualifying EEA residence makes the general appointment optional. A third-country taxpayer has 15 days to join an accepted digital channel. The VAT representative is a taxable person established in Portugal.
What You'll Need to Provide
- Identity and NIF
- Your identification, Portuguese NIF and access details needed for the agreed AT procedure.
- Residence and address evidence
- Your current residence country, fiscal address and the date of any move into or out of Portugal.
- Portuguese tax relationship
- The income, property, registration, contract or other fact that creates your relationship with the Portuguese tax system.
- Activity and VAT facts
- Your Portuguese supplies, establishment, self-employed activity and current VAT registration position.
- Current notification arrangements
- Any Portal das Finanças notification setting, electronic mailbox or Morada Única Digital service already in use.
- Existing representation records
- Any appointment, acceptance, replacement request, power of attorney or AT communication already issued.
How Fiscal Representation Is Handled in Portugal
A specialist prepares the representation record for the Autoridade Tributária e Aduaneira, and a certified accountant handles the tax filings the engagement requires.
-
Collecting the Facts for the Representation Rules
Your residence country, Portuguese tax relationship, income, absence and activity facts are collected. A certified accountant compares them with CIRS Article 130.
-
Setting Out the Electronic-Notification Option
The notification step lists the eligible dematerialised-notification channels with the records each one needs.
-
Preparing the Appointment and Acceptance
A specialist prepares the taxpayer, representative, address and acceptance information for the selected AT route.
-
Registering the Representative With AT
The agreed appointment is submitted through the Portal das Finanças or the applicable Serviço de Finanças procedure.
-
Defining the Tax Mandate
The mandate record lists the powers and tax duties included in the engagement.
-
Addressing VAT Representation
A specialist prepares the VAT-representation records under the separate CIVA rules when your Portuguese operations require a VAT representative.
Timing and Possible Delays
Within the applicable AT deadline
AT guidance gives a third-country taxpayer 15 days after establishing the Portuguese tax relationship or communicating a third-country address to appoint a representative or join an eligible dematerialised-notification channel.
What delays it
The work takes longer when the NIF, fiscal address, residence evidence, representative acceptance, Portal access or VAT-activity facts are incomplete.
What to prepare now
Your identification, NIF, residence, address, activity, notification and existing-representation records need to be gathered before the work begins.
Registration, Mandate and VAT Considerations
The appointment and acceptance record
The declaration of commencement, change or taxpayer-number registration records the appointment, and the representative’s express acceptance is preserved. A specialist checks that the completed record identifies the taxpayer and representative consistently before it is submitted through the applicable AT route.
The mandate for tax acts
The engagement file records the mandate document and the tax acts it includes. Each act has its basis in law or in the mandate, and the file notes that basis before the act is submitted.
The separate VAT file
The separate VAT file opens when you carry on taxable Portuguese operations. The file identifies your establishment, supplies, commencement date and proposed representative, and the representative needs the powers and Portuguese taxable-person status required by Article 30 of the CIVA before a covered self-employed activity begins.
Set out your representation needs
Describe where you live, which Portuguese tax relationship you have, whether you carry on an activity and what AT arrangements already exist.
Common questions
Who must appoint a fiscal representative in Portugal?
Is fiscal representation mandatory for an EU or EEA resident?
Can I use electronic notifications without a fiscal representative?
Can a company act as a fiscal representative?
Is a VAT representative the same as a general fiscal representative?
Does a fiscal representative pay the non-resident's tax?
What can a representative do before AT?
What is the penalty for failing to appoint a required representative?
How much does fiscal representation cost?
How is my fiscal representation handled?
How the Service Works
-
One team for the whole case.
The same team handles all of the representation, tax, VAT and accounting records.
-
English or Portuguese.
English or Portuguese, whichever you are most comfortable in.
-
A quote in writing before work starts.
You get a quote in writing before any work starts. You are told plainly if your case falls outside the service.
Contact us
Your request is in
Every request is read in house. The requirements are assessed, and a reply by email sets out the appropriate next steps.
Every enquiry is read in house, and the aim is a reply within one business day.
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.