International Tax Advisors in Portugal
An international tax advisor in Portugal helps people with foreign and Portuguese income claim relief when the same income is taxed in two states. We check each treaty claim against the residence certificate that AT requires from the other state.
First conversation free Reply within one business day
Who Needs International Tax Support in Portugal
- You have lived in Portugal and another country during the same tax period and need a certified accountant to apply the residence tests to your facts.
- You receive foreign employment, pension, investment, property or business income alongside Portuguese income.
- You need a treaty, residence certificate and foreign-tax-credit position checked for a particular income stream.
- Your company has Portuguese and foreign activity and needs the applicable corporate treaty and credit rules reviewed.
You need a complaint, appeal or court work. Advisors in Portugal does not handle those matters. The work covers tax compliance and tax consultancy by certified accountants within the agreed scope.
What's Included in International Tax Consultancy
You get a quote in writing before any work starts.
- Residence analysis. A certified accountant applies Article 16 of the CIRS to your days, homes and residence history for the relevant period.
- Foreign-income classification. A certified accountant maps each income stream to its source, Portuguese tax category and supporting evidence.
- Treaty review. A certified accountant checks the residence state, source state, income article, taxing rights and relief method in the applicable convention.
- Foreign-tax-credit analysis. A certified accountant compares foreign tax paid with the Portuguese credit limit under Article 81 of the CIRS.
- Treaty-relief evidence. A certified accountant checks the foreign tax-authority residence certificate and any treaty form required for the relief route.
- Personal and company consequences. A certified accountant reviews the personal and company consequences of the cross-border position.
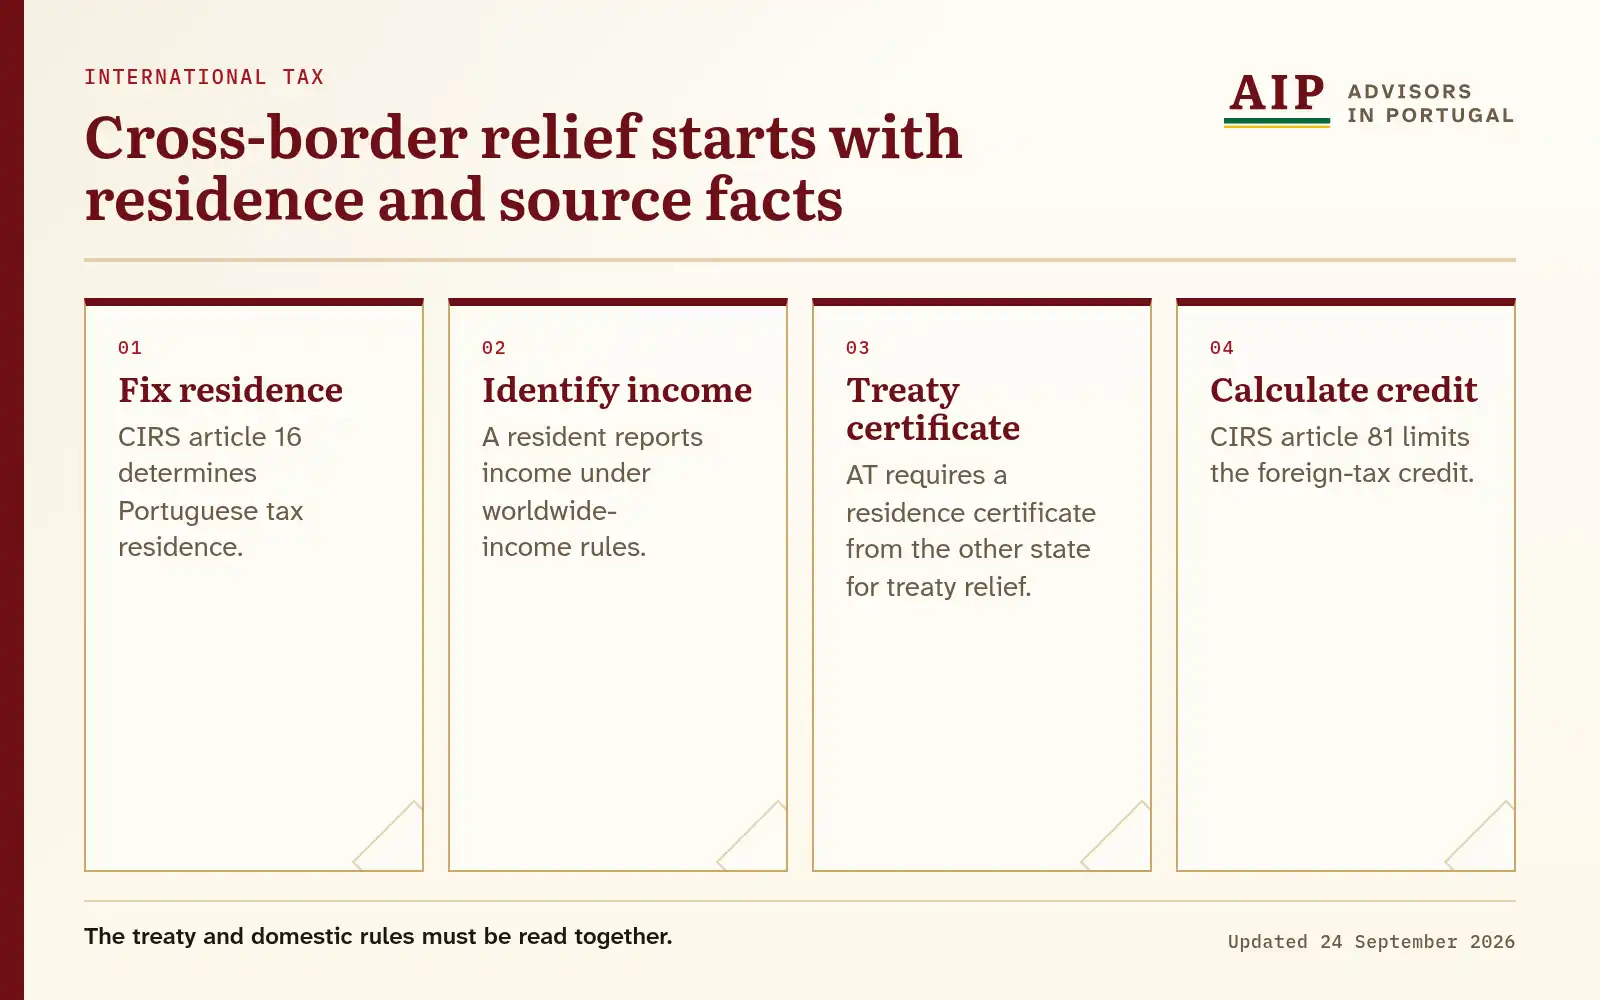
Diagram text version
CIRS article 16 determines Portuguese tax residence. A resident reports income under worldwide-income rules. AT requires a residence certificate from the other state for treaty relief. CIRS article 81 limits the foreign-tax credit.
What You'll Need to Provide
- Residence timeline
- Your travel days, homes, household facts and fiscal-address changes by tax year.
- Income schedule
- Portuguese and foreign employment, pension, property, investment, business and other income records.
- Foreign-tax evidence
- Foreign returns, assessments, withholding certificates and proof of tax paid for each income stream.
- Treaty evidence
- The residence and source countries, income type, payer details, residence certificate and treaty form available to you.
- Asset and company records
- Ownership, acquisition, disposal and company documents relevant to the cross-border analysis.
- Prior Portuguese filings
- Returns, assessments, notices, payments and Autoridade Tributária e Aduaneira correspondence for the periods under review.
How International Tax Consultancy Works
A certified accountant prepares the agreed filings for the Autoridade Tributária e Aduaneira and notes any accounting, investment or company questions that arise.
-
How Residence and Tax Periods Are Established
A certified accountant records the relevant years, travel days, homes and residence history before applying the Portuguese tests.
-
How Each Income Stream Is Classified
A certified accountant maps each amount to its source country, Portuguese category and supporting evidence.
-
How Treaty Residence and Relief Are Checked
A certified accountant identifies the convention, income article, taxing rights and certificate requirements for each stream.
-
How Foreign-Tax Credits Are Calculated
A certified accountant compares foreign tax paid with the Portuguese limit and records the evidence for the return.
-
How Personal and Corporate Effects Are Reviewed
A certified accountant checks the personal and company consequences of the position.
-
How the Required Filing Is Prepared
A certified accountant prepares the agreed Portuguese filing and evidence schedule for submission to the Autoridade Tributária e Aduaneira.
Timing and Possible Delays
Set by the tax year and evidence
The work is planned around the relevant tax year, filing period, treaty evidence and number of income streams.
What delays it
The work takes longer when travel dates, foreign statements, proof of tax paid, residence certificates, transaction records or prior filings are incomplete.
What to prepare now
You organize your residence, income, foreign-tax, treaty, asset and prior-filing records by tax year before the work begins.
Residence, Treaties and Foreign Income
The residence evidence file
A certified accountant prepares a dated residence chronology from passports, leases and utility records before the return file is assembled. A certified accountant records the evidence source beside each move so a partial-year question can be resolved without reopening the entire file.
Treaty certificates and the relief sequence
A certified accountant annotates each residence certificate with its issuing authority and covered period before attaching it to the treaty schedule. A certified accountant records the convention reference beside the certificate before the filing evidence is assembled.
Arrival-year and treaty transition records
A certified accountant records the treaty effective-date evidence in the tax-year file before any cross-border filing is drafted. A certified accountant adds a source note when a convention changes during an open tax year so the filing record preserves the rule used.
Set out your international tax position
State where you lived, which income and assets you hold, where tax was paid and which countries affect the position.
Common questions
When can Portugal treat me as tax resident?
Does a Portuguese resident report foreign income?
Can I claim a Portuguese credit for foreign tax paid?
How do I prove treaty residence?
Does one treaty result apply to every type of income?
What changed in the UK-Portugal treaty?
Does IFICI replace international tax analysis?
Can a company claim foreign-tax credit in Portugal?
What does an international tax review cover?
How much does international tax consultancy cost?
How is the international tax work handled?
What to Expect From the Service
-
One team for the whole case.
Tax, accounting, investment and company questions are handled together in one case.
-
English or Portuguese.
English or Portuguese, whichever you are most comfortable in.
-
A quote in writing before work starts.
You get a quote in writing before any work starts. A case outside the service is flagged plainly.
Contact us
Your request is in
Every request is read in house. The requirements are assessed, and a reply by email sets out the appropriate next steps.
Every enquiry is read in house, and the aim is a reply within one business day.
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.