Capital Gains Tax Advice in Portugal
Capital gains tax advice in Portugal supports sellers whose disposal of Portuguese property, shares or another asset raises questions of residence, exemption or treaty position. Our work runs from asset classification and the gain calculation through to the agreed Portuguese filing.
First conversation free Reply within one business day
Who Needs Capital Gains Tax Support in Portugal
- You sold or plan to sell Portuguese property and need the acquisition, improvement and disposal records reviewed.
- You disposed of shares, securities or another asset and need its category under Article 10 of the CIRS identified.
- Your Portuguese residence position changed before or after the disposal and may affect the tax analysis.
- You are considering an exemption or reinvestment position and need the statutory conditions tested against the transaction facts.
You need only recurring income-tax filing with no asset disposal or capital-gains question; the service covers tax work connected with an asset disposal or capital gain.
What's Included in Capital Gains Tax Support
You get a quote in writing before any work starts.
- Asset classification. A certified accountant identifies the relevant Article 10 category from the asset and transaction facts.
- Residence analysis. A certified accountant reviews your Portuguese residence position under Article 16 of the CIRS for the relevant period.
- Gain calculation. A certified accountant reviews the agreed acquisition, improvement, ownership, disposal and transaction-cost evidence.
- Exemption and reinvestment review. A certified accountant tests the relevant CIRS conditions against the disposal and use of proceeds.
- Cross-border analysis. A certified accountant identifies the residence, source and treaty questions included in the engagement.
- Tax-return support. A certified accountant prepares the agreed Portuguese filing work for the relevant tax period.
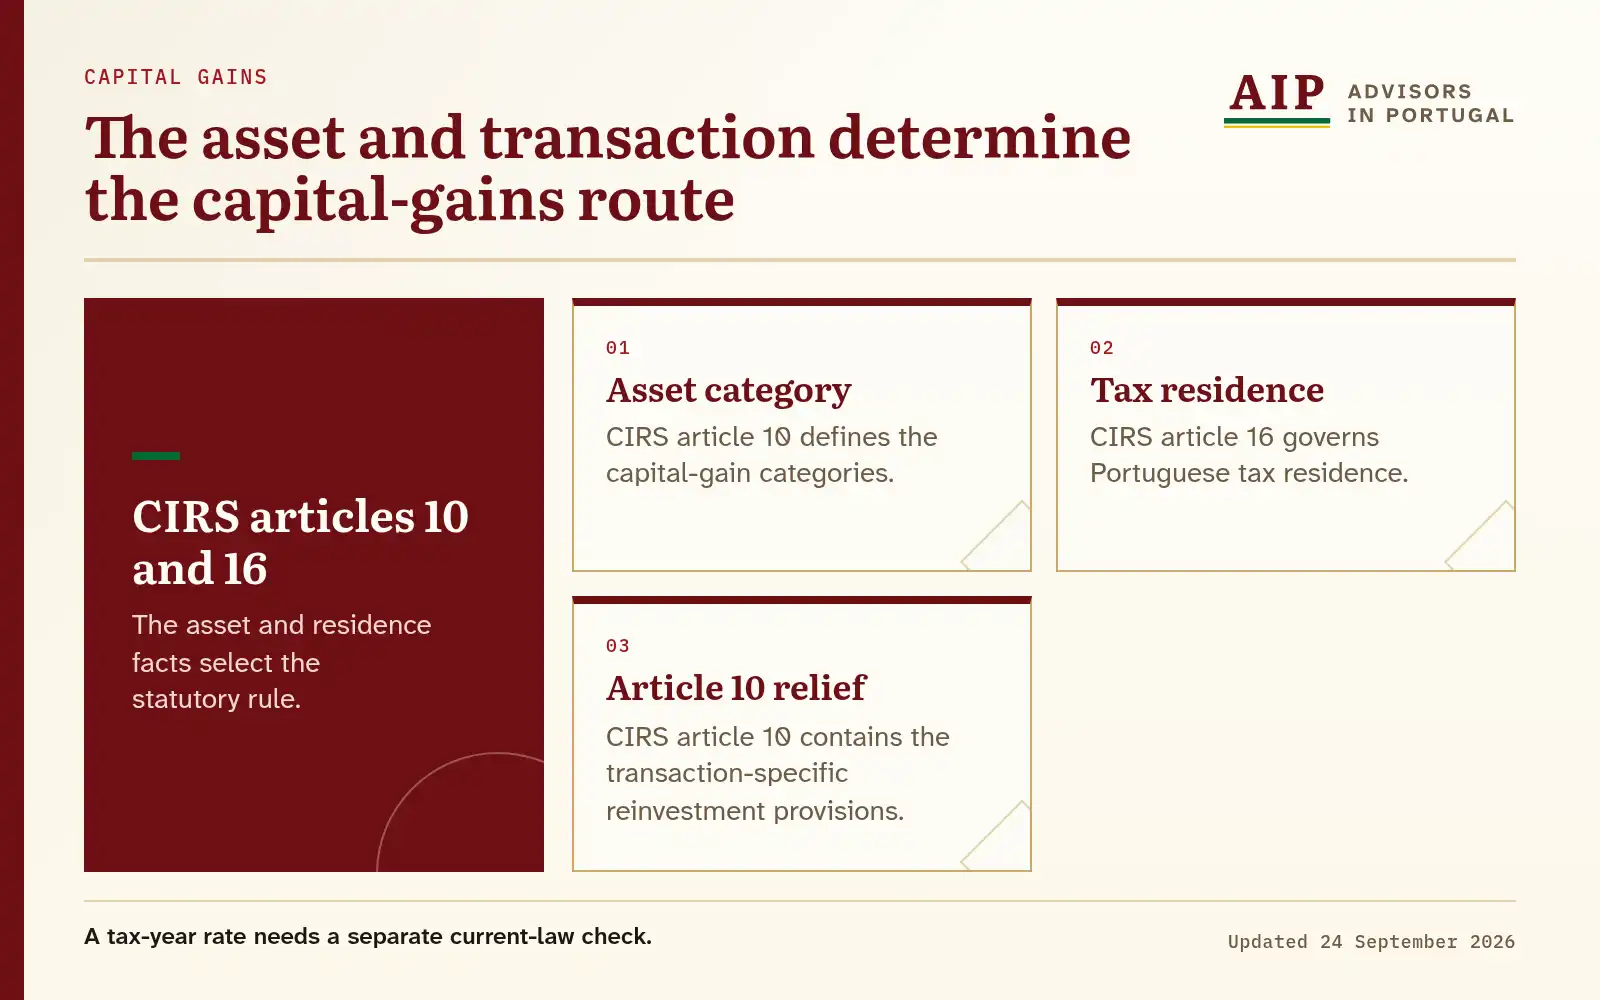
Diagram text version
CIRS article 10 defines the capital-gain categories. CIRS article 16 governs Portuguese tax residence. CIRS article 10 contains the transaction-specific reinvestment provisions.
What You'll Need to Provide
- Asset and ownership details
- The asset type, ownership percentages, acquisition route and any changes in ownership.
- Acquisition records
- The purchase or acquisition document, price, date, taxes, fees and financing records.
- Improvement evidence
- Invoices, contracts, payment records and descriptions for expenditure connected with the asset.
- Disposal records
- The sale agreement, completion statement, price, date, commissions, legal costs and proceeds received.
- Residence timeline
- Your dates in Portugal and other countries, homes, household facts and Portuguese tax registration.
- Reinvestment and prior filings
- Documents for any claimed use of proceeds and the relevant Portuguese and foreign tax returns.
How Capital Gains Tax Support Works in Portugal
A certified accountant prepares and submits the agreed Portuguese return to the Autoridade Tributária e Aduaneira and flags residence, reinvestment, ownership and treaty questions along the way.
-
Asset and transaction classification
A certified accountant maps the asset, ownership, acquisition and disposal facts to Article 10 of the CIRS.
-
Portuguese residence review
A certified accountant checks the relevant residence period under Article 16 of the CIRS.
-
Acquisition and disposal evidence
A certified accountant reconciles the purchase, improvement, sale, cost and proceeds records included in the engagement.
-
Exemption and reinvestment analysis
A certified accountant tests the relevant CIRS conditions against the documented transaction and use of proceeds.
-
Cross-border tax review
A certified accountant identifies the foreign residence, tax and treaty questions that form part of the agreed work.
-
Portuguese return preparation
A certified accountant prepares the agreed filing work against the Autoridade Tributária e Aduaneira's calendar for the relevant period.
Timing and Possible Delays
Set by the transaction and filing period
The work is planned around the asset, acquisition history, disposal documents, residence facts, reinvestment evidence and relevant tax period.
What delays it
The work takes longer when ownership records, acquisition costs, improvement invoices, disposal statements, residence dates or foreign tax documents are incomplete.
What to prepare now
You gather your asset, acquisition, improvement, disposal, residence, reinvestment and prior-filing records before the work begins.
Acquisition Evidence, Residence and Reinvestment Records
Acquisition and improvement evidence
You record when each cost was incurred and which asset or improvement it concerns. You attach each improvement invoice to its contract, proof of payment and description so a certified accountant can test the cost against the relevant transaction.
Residence evidence at the disposal date
You separate the evidence for each residence period and mark travel dates that overlap the acquisition, disposal or reinvestment events. A certified accountant uses that file to test the Article 16 position against each residence period.
Reinvestment record sequence
You record the disposal proceeds, each later payment and the legal document for the asset or purpose connected with the claimed reinvestment. A certified accountant compares that sequence with the relevant statutory conditions before the agreed filing is prepared.
Set out your capital gains position
State what you acquired and disposed of, where you lived, which costs you can document and how you used the proceeds.
Common questions
Which law governs capital gains in Portugal?
Which assets can fall within Portuguese capital gains rules?
Does Portuguese tax residence affect a disposal?
How is the taxable gain calculated?
Can an exemption apply to a capital gain?
Can reinvestment affect the tax position?
Which records support the calculation?
Who is my contact for the capital gains tax work?
How the Service Works
-
One team for the tax work.
One team manages the case end to end, and certified accountants handle the tax and cross-border filing questions.
-
English or Portuguese.
English or Portuguese, whichever you are most comfortable in.
-
A quote in writing before work starts.
You get a quote in writing before any work starts. You are told plainly if your case is outside the service.
Contact us
Your request is in
Every request is read in house. The requirements are assessed, and a reply by email sets out the appropriate next steps.
Every enquiry is read in house, and the aim is a reply within one business day.
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.