Taxes in Portugal: A Guide for Individuals
Taxes in Portugal for individuals include IRS on income and capital gains, property taxes on ownership and purchase, and VAT. Your tax residence decides which income Portugal taxes, and a double-tax treaty can change the result.
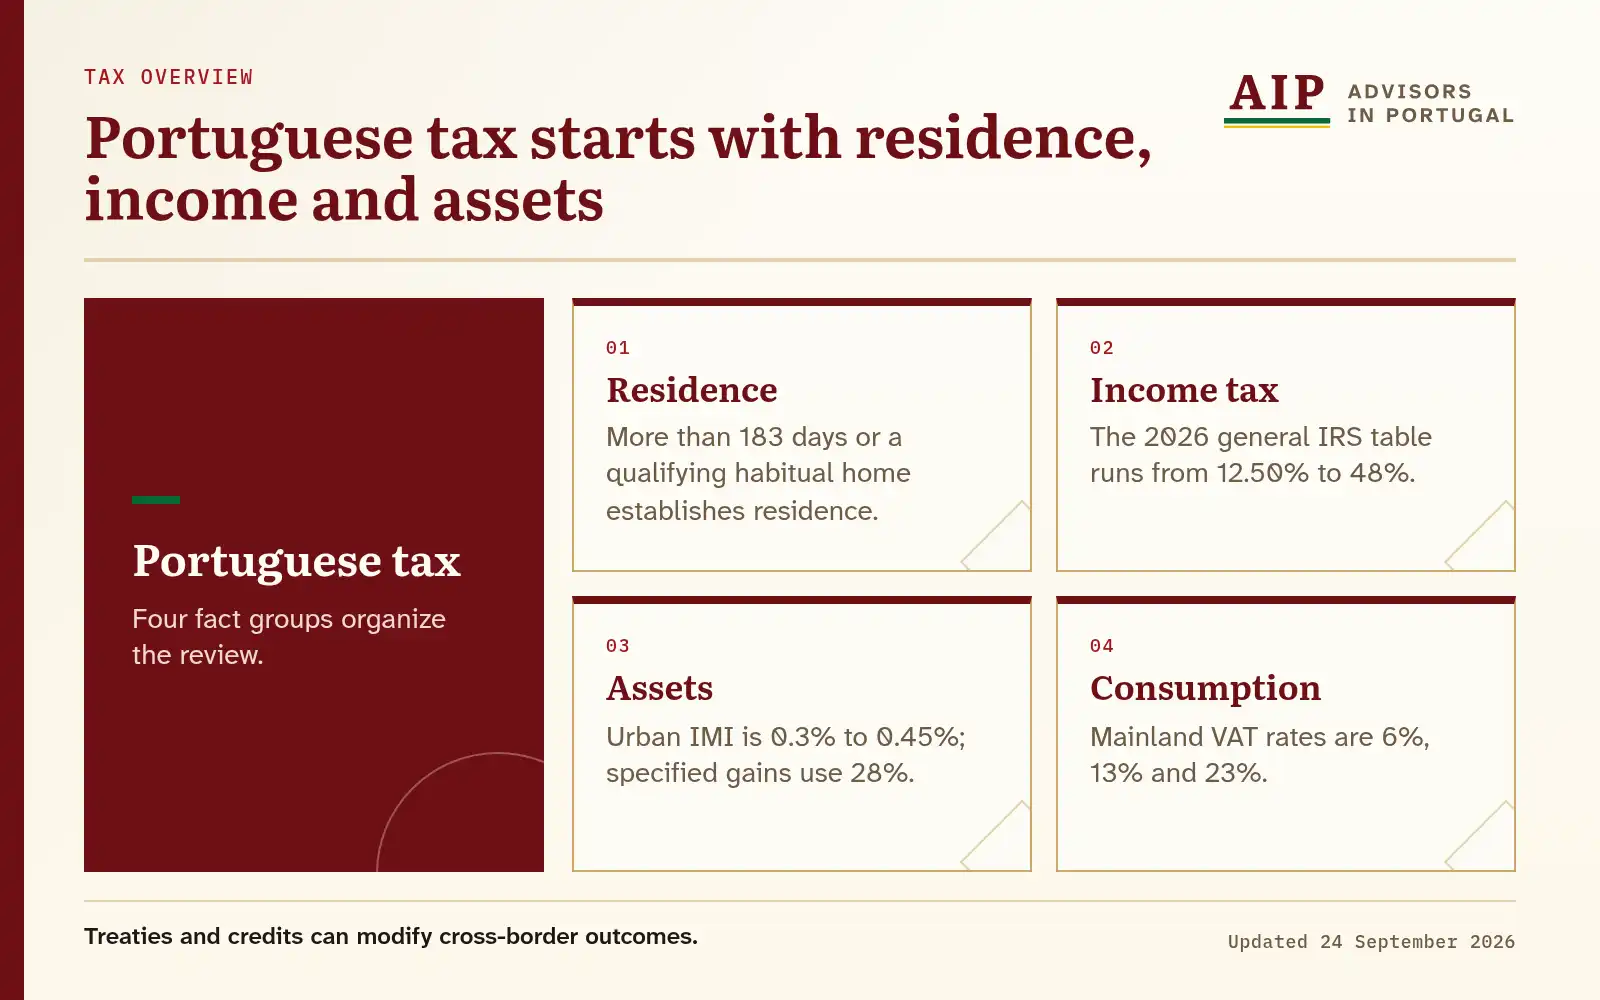
Diagram text version
More than 183 days or a qualifying habitual home establishes residence. The 2026 general IRS table runs from 12.50% to 48%. Urban IMI is 0.3% to 0.45%; specified gains use 28%. Mainland VAT rates are 6%, 13% and 23%.
Portugal applies residence, income-category, source, asset, activity and tax-year rules to each person’s facts. Two people living at the same address can have different Portuguese obligations because their income and cross-border facts differ.
Article 16 of the Código do Imposto sobre o Rendimento das Pessoas Singulares, or CIRS, governs residence, Article 10 governs capital gains and the Autoridade Tributária e Aduaneira publishes the filing calendar. Each tax position rests on the facts behind every income stream, asset and filing.
How Does Portugal Decide Tax Residence?
Article 16(1)(a) of the CIRS treats a person as resident when that person spends more than 183 days, consecutively or intermittently, in any 12-month period beginning or ending in the relevant year. Article 16(1)(b) can also apply with fewer days when a Portuguese home is held in conditions showing an intention to keep and occupy it as a habitual residence. A day count and a review of housing test the two limbs separately.
Tax residence is decided by the Article 16 tests; an address, a tax number or a residence permit is only evidence for them. Immigration residence and tax residence involve separate tests.
Another country may also treat the same person as resident for the same period. That overlap can raise treaty questions, filing obligations and credit or exemption analysis. A travel calendar, home information, employment or business arrangements and any foreign residence certificates that already exist record the facts for both countries.
The move date and other date-sensitive facts are compared with the applicable CIRS rules. Evidence of travel, housing and the start or end of work and business activities is easier to assemble before the filing deadline approaches.
Which Income Needs Portuguese Tax Review?
Portuguese residents are taxed on their total income, including income from abroad. A complete income map is the starting point. It classifies employment, self-employment, pensions, rent, dividends, interest and gains by category and source.
The map lists gross income before foreign withholding and identifies the payer and country. Keep the statement or contract that explains each payment with the map. Each item is then classified under Portuguese law and checked for treaty relevance.
Employment income, independent services and business income create different registration, expense and contribution questions. The contract and the way the work is performed decide which rules apply. Share awards, carried interest, director payments, partnership income and deferred compensation each need separate treatment. Each item is tested against the Portuguese income category.
A spouse or partner may have different residence histories, income sources and ownership interests. Those facts are separated before the household filing position is considered.
How Are Portuguese IRS Rates Identified?
For 2026, Article 68(1) of the CIRS, as amended by Lei 73-A/2025, sets normal IRS rates from 12.5% on taxable income up to EUR 8,342 to 48% above EUR 86,634, with thresholds at EUR 12,587, EUR 17,838, EUR 23,089, EUR 29,397, EUR 43,090 and EUR 46,566. Each income category is placed in the table for the year.
Gross amounts, deductible-cost records and foreign tax evidence establish the taxable base before the relevant rate rule applies. The rate applies to the correct taxable base even when the percentage itself is current.
Article 72 of the CIRS contains special-rate provisions, and each provision applies only to the income and circumstances it covers. Investment income, rent and a payment from abroad do not always receive the same treatment. The legal category, the source and any election or aggregation question affect the calculation.
The law and official material applicable to the tax period govern the result. The tax year needs identifying before a rate or rule from a later budget is relied on.
How Does Portugal Treat Capital Gains?
Article 10 of the CIRS identifies the transactions that can produce a capital gain, and Article 72(1)(c) applies a 28% autonomous rate to the positive balance of listed gains and losses, subject to the exceptions and mandatory aggregation in Article 72(14). The balance of gains and losses for the year is computed before the rate is applied.
The calculation uses the acquisition date, acquisition value, disposal date, proceeds, ownership percentage and documented transaction costs. Property gains may also require the deed, tax record and evidence of qualifying expenditure. Securities gains may require broker statements, corporate-action records and transaction histories in the original currency.
Residence and the location or nature of the asset may affect the Portuguese treatment. A treaty can also matter when another country taxes the same disposal. The gain is therefore reviewed together with residence and foreign-tax facts as part of the complete tax calculation.
Timing records matter when assets were acquired in stages, inherited, received as gifts or reorganised. Those records support the basis and transaction history, even when a platform or bank no longer displays older statements online.
Which Property Taxes Can Matter?
Article 112(1)(c) and (5) of the CIMI place urban IMI within a municipal annual rate range of 0.3% to 0.45% of the property tax value. Article 17 of the CIMT applies separate progressive or fixed IMT rates according to the property, value, destination and buyer facts. Acquisition, ownership, income and disposal are separate events.
For each property, the land-registry description, the tax record, the deed, the ownership share and the intended use matter. A rented property also needs the lease, income and expense records. Acquisition and improvement records become central to the Article 10 CIRS capital-gains analysis when a sale is planned.
Keeping the acquisition, ownership, income and disposal records in separate schedules lets the current Portuguese rules apply to each event and keeps the charges separate.
The person or entity that owns the asset and the way funds and income move between countries also matter. Financing, company ownership and treaty connections need disclosing before the property calculation is finalised.
When Does VAT Need Review?
CIVA Article 18(1) sets mainland VAT at 6% for List I, 13% for List II and 23% for other imports, supplies and services; Article 18(3) permits regional rates for the Azores and Madeira. Each supply is classified against those lists before a rate applies.
Registration, invoicing and return questions depend on the supply and taxpayer facts. Contracts, invoice examples, customer locations and any existing VAT numbers show those facts.
VAT, income tax and social contributions are separate systems. Each registration and return stands on its own.
How Can a Tax Treaty Affect the Result?
CIRS Article 81(1) gives residents receiving foreign income a credit for international juridical double taxation, generally limited to the lower of foreign tax paid and the Portuguese tax attributable to that income. The applicable bilateral treaty is read by country and income type after the domestic treatment is established.
The treaty analysis uses the other country, payer, income category, tax period and foreign tax withheld or paid. Residence certificates and official assessments may also be needed. The treaty residence certificate and the first-notification or assessment record matter when competent-authority relief may be relevant.
Different articles can govern employment, pensions, property income, dividends, interest, royalties or gains. The article for the payment at issue applies, subject to its conditions. The article and source rule belong beside each income stream.
The taxpayer keeps proof of the foreign tax, taxable base and period. That evidence is matched to the Portuguese return and applicable convention.
When Do You File Portuguese Tax Returns?
The current annual filing window comes from the AT’s published calendar, generally 1 April to 30 June. Separate VAT, property or payment dates can apply to the filings in scope.
The taxpayer should identify each registration and return that may apply before relying on one annual deadline. A person with employment income may have a different filing set from someone with independent activity, rental property or VAT obligations. The filing set follows from the person’s registrations.
Changes during the year can create additional steps. Residence, address, activity and property events each follow their own official procedures. Submission receipts and notices from the Autoridade Tributária e Aduaneira belong with the underlying records.
Missing foreign statements or valuation records are best raised early enough for the return to be prepared accurately.
What Records Should You Gather?
A one-page timeline covering residence, work, business, property and major transactions for the tax year is a good starting point. The timeline shows which documents and jurisdictions need closer review.
The supporting records are identification and tax numbers, residence records, income statements, bank and broker reports, property documents, invoices, pension statements and foreign returns. Gross amounts and the foreign tax withheld should stay visible on every statement.
Every country connected with residence, work, a payer, an asset or a tax payment belongs on the list. That list shows the relevant domestic rules and treaty questions. Planned moves, sales or distributions also matter because the treatment before an event can differ from reporting after it has happened.
Complete facts and original records come first. The legal classification of each item follows from them.
Common questions
What determines tax residence in Portugal?
Does Portuguese residence decide every tax result?
Which Portuguese income-tax rate applies to me?
Which rule covers Portuguese capital gains?
Can a double-tax treaty remove Portuguese tax?
Do property ownership and property purchase use the same tax analysis?
Related guides
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.