Portugal Tax Residency: Tests and Filing (2026)
Tax residency in Portugal arises from more than 183 days in a relevant 12-month period or from a habitual home under Article 16 of the CIRS. Your travel dates and home decide whether your Portuguese IRS return covers worldwide income or only Portuguese-source income.
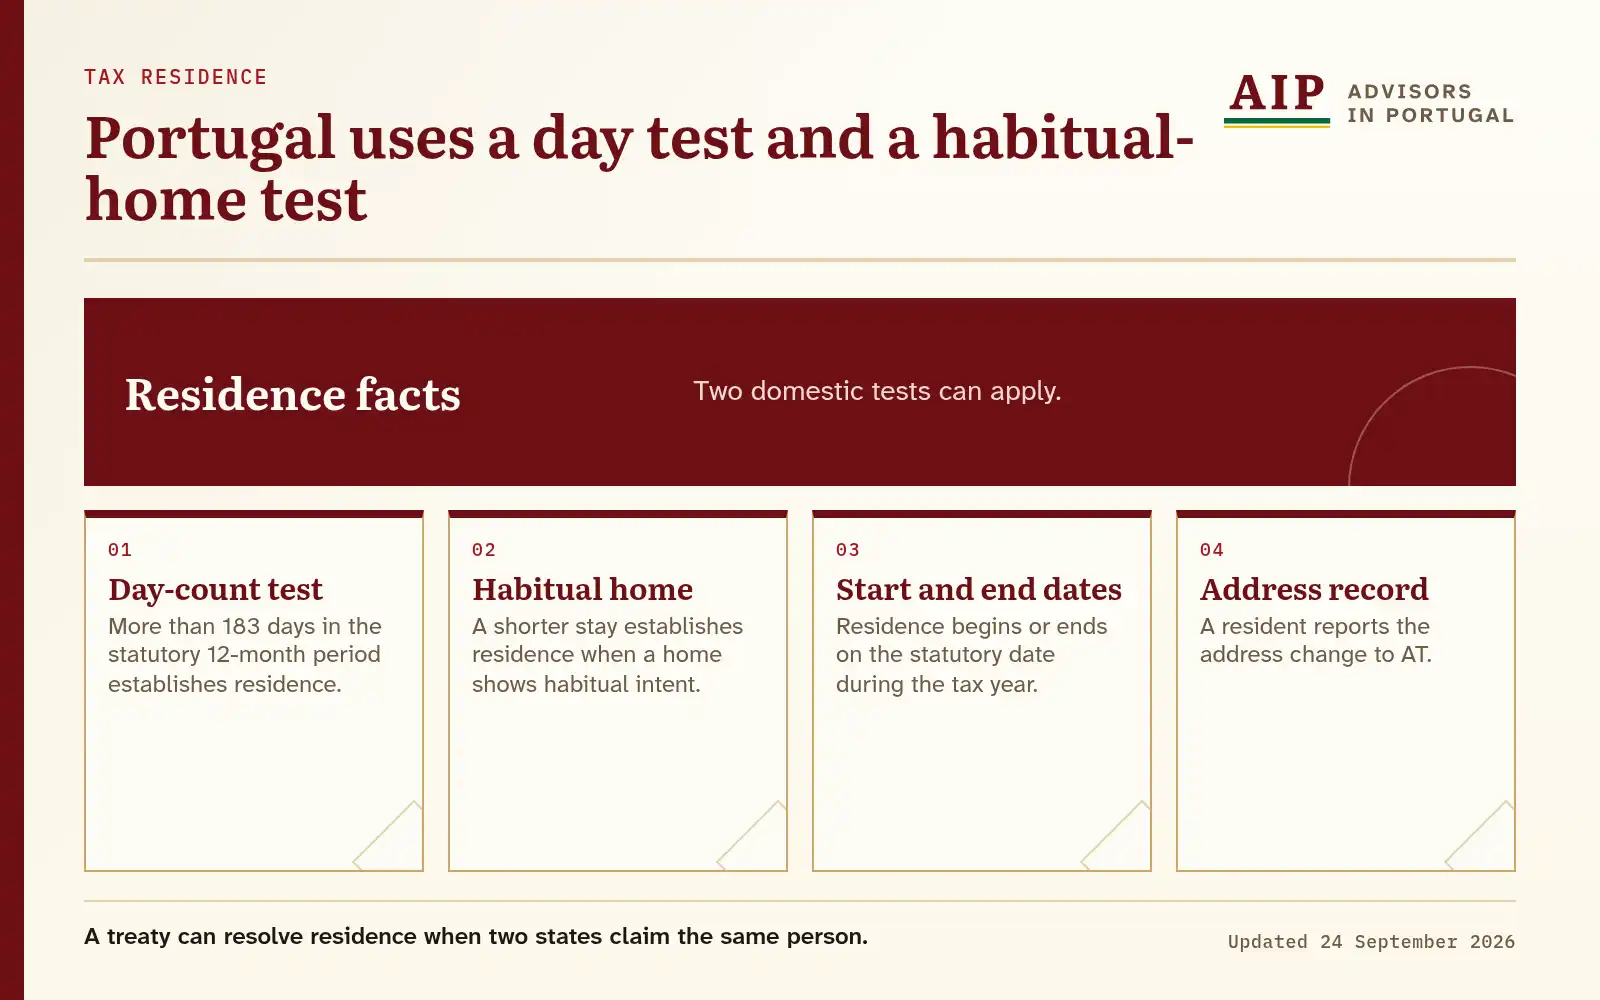
Diagram text version
More than 183 days in the statutory 12-month period establishes residence. A shorter stay establishes residence when a home shows habitual intent. Residence begins or ends on the statutory date during the tax year. A resident reports the address change to AT.
The CIRS treats a person as resident when the Article 16 day-count or habitual-home condition is met. Article 15 then determines whether the return includes worldwide income or Portuguese-source income for the relevant period.
When Do You Become a Tax Resident in Portugal?
Article 16(1)(a) of the CIRS uses more than 183 days, consecutive or intermittent, during a period of 12 months beginning or ending in the relevant tax year; Article 16(1)(b) uses a habitual home held with the intention of occupying it as habitual residence. The period can reach across two calendar years.
Travel, available homes and family or economic connections are mapped against Article 16 before a status change is filed.
How Does the 183-Day Test Work?
More than 183 days in Portugal, consecutive or intermittent, during the relevant 12-month period satisfies the day-count limb of Article 16(1)(a). The law does not require the days to run together. A sequence of short stays can therefore produce the same result as one long stay.
Keep entry and exit evidence, accommodation records and a day-by-day calendar. Border stamps, airline records and payment data can help reconcile an incomplete travel log. The same period is then tested against another country’s domestic residence rules and any treaty.
Can a Habitual Home Make You Resident?
Article 16(1)(b) treats a dwelling as a residence trigger when, on any day of the relevant period, you maintain a home in conditions that show an intention to keep and occupy it as your habitual residence.
The wording focuses on intention shown by objective facts. A long-term lease, available accommodation, household arrangements and the way you use the property can matter. The facts that support or contradict habitual occupation should be documented.
When Does Portuguese Residence Start and End?
Article 16(3) generally starts residence on the first day of the period of stay that meets the statutory test. Residence instead starts on 1 January of the current year in which an Article 16(1) condition is met if you were resident on any day of the previous year. Article 16(4) generally ends residence on the last day of the period of stay, subject to the code’s specific rules. The start and end dates therefore affect the income period reported to Portugal.
Record the date on which the qualifying period begins as well as the date on which you receive a residence card. A departure year can include resident and non-resident periods. The return can be split and the source rules tested for each period.
How Do You Change Your Tax Address?
You must communicate a change from resident to non-resident within 60 days under Article 19(4) of the LGT. An uncommunicated domicile change is ineffective against the Tax Authority under Article 19(4). The same practical discipline matters when your correspondence address or status changes in the other direction.
Update the address through the prescribed Tax Authority channel and retain confirmation. Check whether the change aligns with the residence period and whether any representative or electronic-notification obligation follows.
What Must a Third-Country Resident Appoint?
A resident of a third country who has a Portuguese tax relationship generally has 15 days to appoint a tax representative or use an eligible electronic-notification route under the Tax Authority’s guidance. A person starting self-employment can face an additional VAT-representative condition.
The obligation depends on your country, activity and Portuguese tax relationship. Identify the correct route before the 15-day period expires, and record the representative appointment separately from the Article 16 residence conclusion.
What Income Does Portugal Tax?
Article 15(1) of the CIRS brings worldwide income of Portuguese residents into IRS, while Article 15(2) limits non-residents to income obtained in Portugal. Article 15(3) applies those rules to partial-year residence under Article 16(3) and (4).
The scope can include employment, self-employment, investment, pensions, rents and gains. Classify each stream, identify the tax year and check whether a treaty changes the allocation.
How Do Tax Treaties Resolve Dual Residence?
The applicable convention governs the analysis when both countries’ domestic rules treat you as resident. Most of Portugal’s tax treaties follow the OECD Model Tax Convention’s tie-breaker framework: permanent home, then closer personal and economic relations, habitual abode and nationality in sequence, with competent-authority consultation when those tests do not resolve the case.
Domestic residence is tested first and treaty residence second. The treaty can allocate taxing rights without changing your domestic registration. Keep the convention version, effective date and residence certificate with the analysis.
How Do Foreign Tax Credits Work?
CIRS Article 81(2) adds the applicable convention cap, including the foreign tax paid limit where the treaty so provides.
Match foreign returns, withholding certificates and treaty articles to each income stream. Compute the Portuguese limit, retain evidence of foreign tax actually paid and check any treaty-specific cap.
When Do Residents File the IRS Return?
Article 60(1) sets the electronic IRS filing window from 1 April to 30 June for the preceding year’s income. Article 60(3) and (4) can extend filing to 31 December when a statutory communication is made because foreign income or credit information was unavailable in time.
Collect foreign statements before the filing window opens. Determine whether an extension applies and whether the communication meets the code’s conditions.
What Happened to the NHR Regime?
Lei n.º 82/2023 repealed the former Article 16 NHR paragraphs after the transition, while Article 236 preserves protection for specified taxpayers who met the statutory conditions and were resident by 31 December 2024.
Check the transitional facts, registration evidence and timing against Article 236. Separate a protected NHR position from the current ordinary resident rules and from any newer incentive with its own conditions.
Residence also affects withholding instructions, social-benefit administration and the address used for official notices. An inconsistent record across those systems can trigger questions about the date on which the Article 16 test was met.
Keep a monthly travel ledger for every relevant 12-month period. Mark arrival and departure dates, overnight stays and days spent in transit where the evidence supports your position. Reconcile that ledger to airline, bank and accommodation records before a return or certificate request.
An arrival year often contains a non-resident period followed by a resident period. A departure year can contain the reverse. The income source, payment date and period of performance can produce different outcomes for each segment, so a single annual label can conceal the actual calculation.
A certificate supports a stated status for a period; it does not decide the source of a payment, the correct treaty article or the amount of credit available. Keep the certificate alongside the underlying facts and tax calculations.
Record whether a spouse, dependent or business remains in another country. Those facts can influence treaty centre-of-interests analysis and the evidence needed to support the chosen residence position. Keep the conclusion dated because travel and housing facts change during the year.
Common questions
How many days make me tax resident in Portugal?
Can a home make me resident with fewer than 183 days?
When does the 15-day deadline to appoint a tax representative start?
Does Portugal still offer NHR to every new arrival?
Can a treaty make me resident in another country?
When does Portuguese tax residence start and end?
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.