UK-Portugal Tax Treaty: 2025 Convention and 2026 Rules
The UK-Portugal tax treaty entered into force on 29 December 2025, but its UK Income Tax and Capital Gains Tax rules take effect on 6 April 2026. A UK Income Tax event before that date still falls under the 1968 convention.
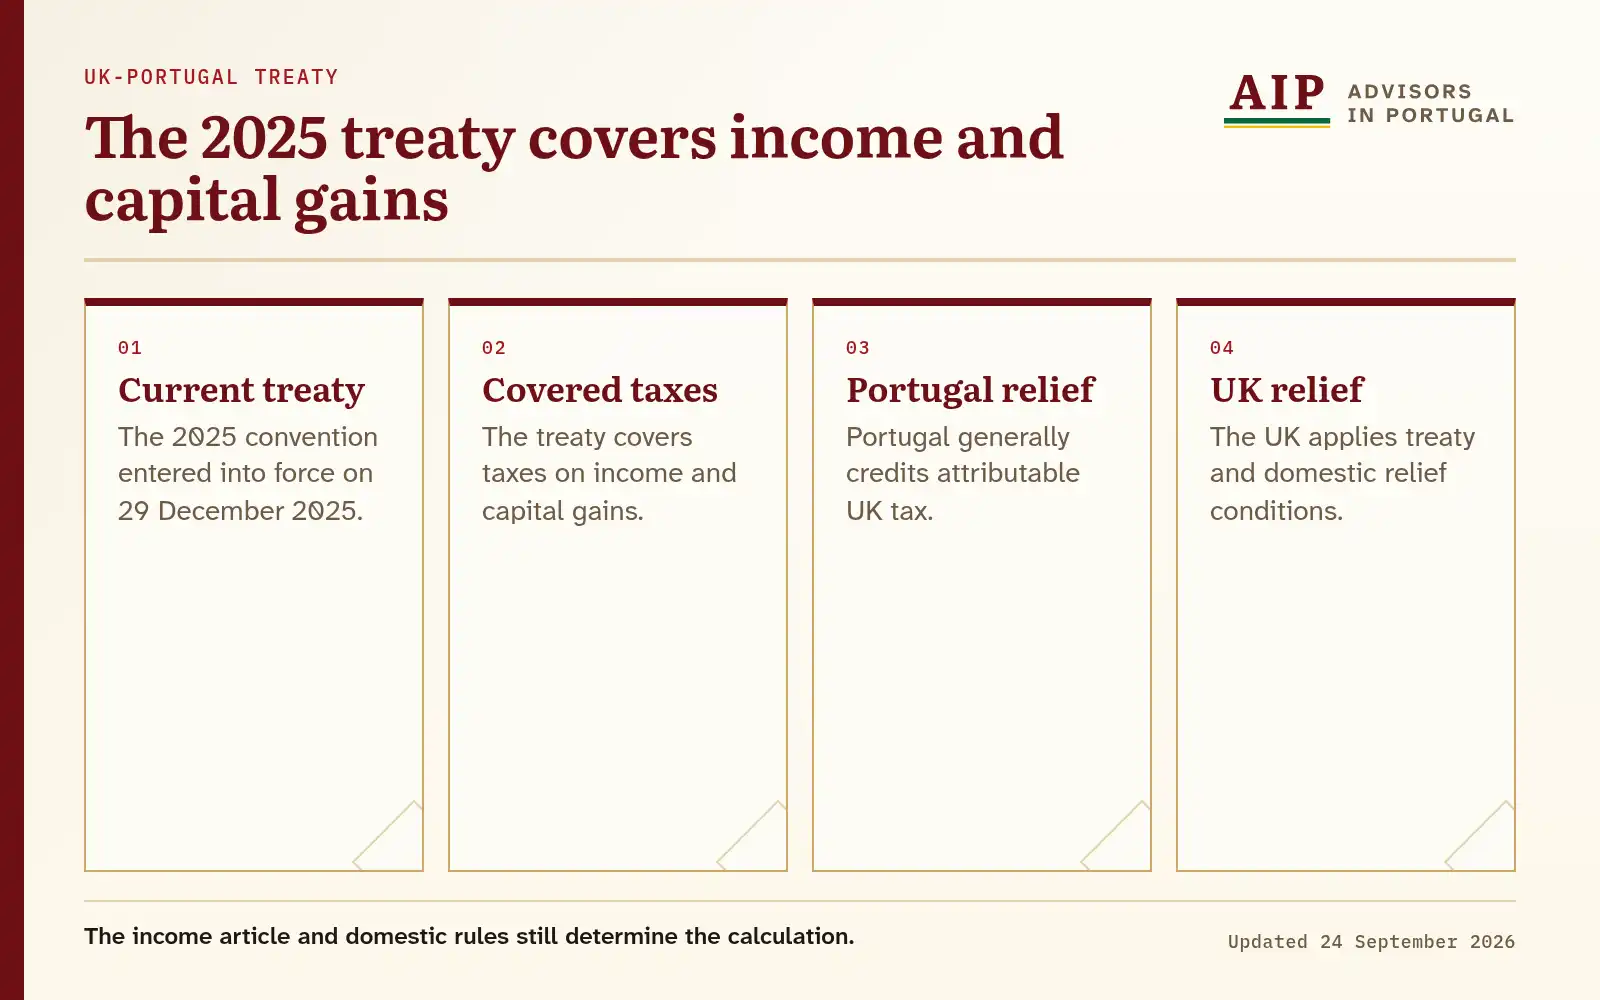
Diagram text version
The 2025 convention entered into force on 29 December 2025. The treaty covers taxes on income and capital gains. Portugal generally credits attributable UK tax. The UK applies treaty and domestic relief conditions.
Portugal applies the 2025 UK-Portugal Double Taxation Convention from 1 January 2026. In the UK it takes effect on 1 January 2026 for withholding taxes, 6 April 2026 for Income Tax and Capital Gains Tax and 1 April 2026 for Corporation Tax, on the split set by Article 28. It replaced the 1968 convention.
Which UK-Portugal Convention Applies in 2026?
The 2025 convention entered into force on 29 December 2025 and is operative for Portugal from 1 January 2026, UK withholding from 1 January 2026, UK Income Tax and Capital Gains Tax from 6 April 2026, and UK Corporation Tax from 1 April 2026. Article 28 leaves the 1968 convention relevant only to earlier periods.
The convention version, article and effective date need confirming for each payment or tax year. A 2025 transaction can need a different analysis from a 2026 withholding event.
When Did the 2025 Convention Take Effect?
Article 28 applies the convention on separate dates for Portugal, UK withholding, UK Income Tax and Capital Gains Tax, and UK Corporation Tax.
The split dates matter when a tax year crosses 5 April or a company period crosses 31 March. The payment date, tax period and effective-date rule are aligned for each tax.
Which Taxes Fall Within the UK Convention?
Article 2 covers Portuguese IRS, IRC and relevant capital-gains taxation and the UK’s Income Tax, Corporation Tax and Capital Gains Tax. The article defines the taxes to which the allocation and relief provisions apply.
Social contributions and taxes outside Article 2 are identified separately. Each domestic charge is then tested for whether the convention covers it and which article allocates it.
How Does Article 4 Resolve UK-Portugal Residence?
Article 1 applies to residents of one or both states, subject to the convention’s special provisions and anti-abuse rules.
Portuguese registration, UK residence evidence, travel dates and home records document the residence position. Each income stream is then classified under the correct convention article.
How Are UK Dividends Taxed in Portugal?
Article 10 caps source-state tax on dividends at 10%. The article sets a 15% cap for the specified investment-vehicle property-income case, subject to its conditions.
The payer, beneficial owner, vehicle and residence certificate show whether the cap is available. The withholding procedure and the Portuguese credit are settled before payment.
How Are Private Pensions Treated?
Article 17 generally assigns private pensions and similar payments to the recipient’s residence state. The pension’s character, payer and the recipient’s treaty residence decide whether it applies.
Article 18 is checked before Article 17 is applied to a government-service pension. The scheme is classified, the paying state is identified and withholding is reconciled with the Portuguese return.
What Is the Government-Service Exception?
Article 18 sets a separate rule for remuneration and pensions connected with government service. Whether it applies depends on the scheme.
The employment or pension authority’s documents and nationality evidence support the classification. Article 18 is tested before the private-pension rule in Article 17 is relied on.
How Does Article 21 Relieve Double Tax?
Article 21 generally permits Portugal to credit UK tax against Portuguese tax attributable to the same income, subject to the convention and CIRS Article 81. UK relief follows Article 21 and the UK’s domestic conditions, which can include credit or exemption treatment.
The credit is limited to the amount permitted by the article and domestic law. The UK assessment or withholding certificate is matched to the Portuguese income, and evidence of tax paid is retained.
When Can Mutual Agreement or Arbitration Help?
Article 23 supplies the mutual-agreement procedure. Protocol paragraph 2 adds mandatory binding arbitration for an unresolved case after 3 years, subject to its conditions; Part IX limits arbitration to cases involving Articles 5, 7 and 9.
The three-year period is an eligibility condition for arbitration. The first notification, the correspondence and the article involved determine whether the dispute falls within the permitted articles.
Which Documents Show Your UK Treaty Position?
Residence certificates, travel calendars, pension statements, dividend vouchers, UK tax calculations, Portuguese IRS returns, withholding records and payment dates are the usual evidence. Each document links to Article 10, 17, 18 or 21 and to the convention’s effective date. Good records also support a competent-authority request if the two assessments conflict.
A UK resident moving during a tax year can have split-year, residence and source questions under domestic law before Article 21 relief is calculated. Those domestic results come first.
The separate application dates apply to each tax. A UK withholding event on 2 January 2026 falls under the 2025 convention, while a UK Income Tax event before 6 April 2026 still falls under the 1968 convention. The payment, tax and accounting periods are recorded together.
Dividend evidence shows the payer, beneficial owner, vehicle type, payment date and withholding. These facts are tested against the 10% and 15% Article 10 conditions before a repayment is requested.
Private occupational pensions, government-service pensions, annuities and lump sums are classified under the domestic and treaty rules. Scheme rules, payment statements, service history and nationality evidence support the Article 17 or 18 conclusion. Domestic tax relief can affect the amount available for a Portuguese credit.
Article 21 relief is limited to tax attributable to the same income. A UK assessment that includes several categories is allocated across interest, dividends, pensions, gains and employment income before the permitted credit applies. The UK tax actually charged, the Portuguese tax attributable to the same income and any domestic limitation are shown side by side, and copies of the filed returns and payment confirmations let a later adjustment trace to the correct treaty article.
Article 23 and Protocol paragraph 2 provide routes with specific conditions, and Part IX narrows arbitration. Preserving the first-notification date and correspondence early keeps those options open when the two authorities assess the same income.
The current HMRC page, treaty text and Portuguese treaty guidance are kept in the file with the checked-on date. They show which source supported the article, effective date and relief used for the return.
The convention does not remove domestic filing duties. A UK return, a Portuguese IRS return, withholding forms or evidence requested by a payer may still be required. HMRC and the Autoridade Tributária control assessments, relief processing and mutual-agreement decisions.
The treaty working paper lists the person or entity, residence period, payment date, tax year, source state and article used. This matters in 2026 because the convention has different UK application dates for withholding, Income Tax, CGT and Corporation Tax. The tax year, payment date and article recorded beside every relief line prevent a later effective-date change from being applied to the wrong payment or tax period.
Common questions
Which UK-Portugal treaty applies from 2026?
When does the new convention apply in the UK?
What is the Article 10 dividend cap?
How does Portugal credit UK tax?
When can arbitration apply?
Which taxes does the UK convention cover?
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.