Portugal Corporate Tax Rates and Deadlines (2026)
The corporate tax rate in Portugal is 19% for tax periods beginning in 2026. The standard rate falls to 18% for periods beginning in 2027 and 17% for periods beginning on or after 1 January 2028.
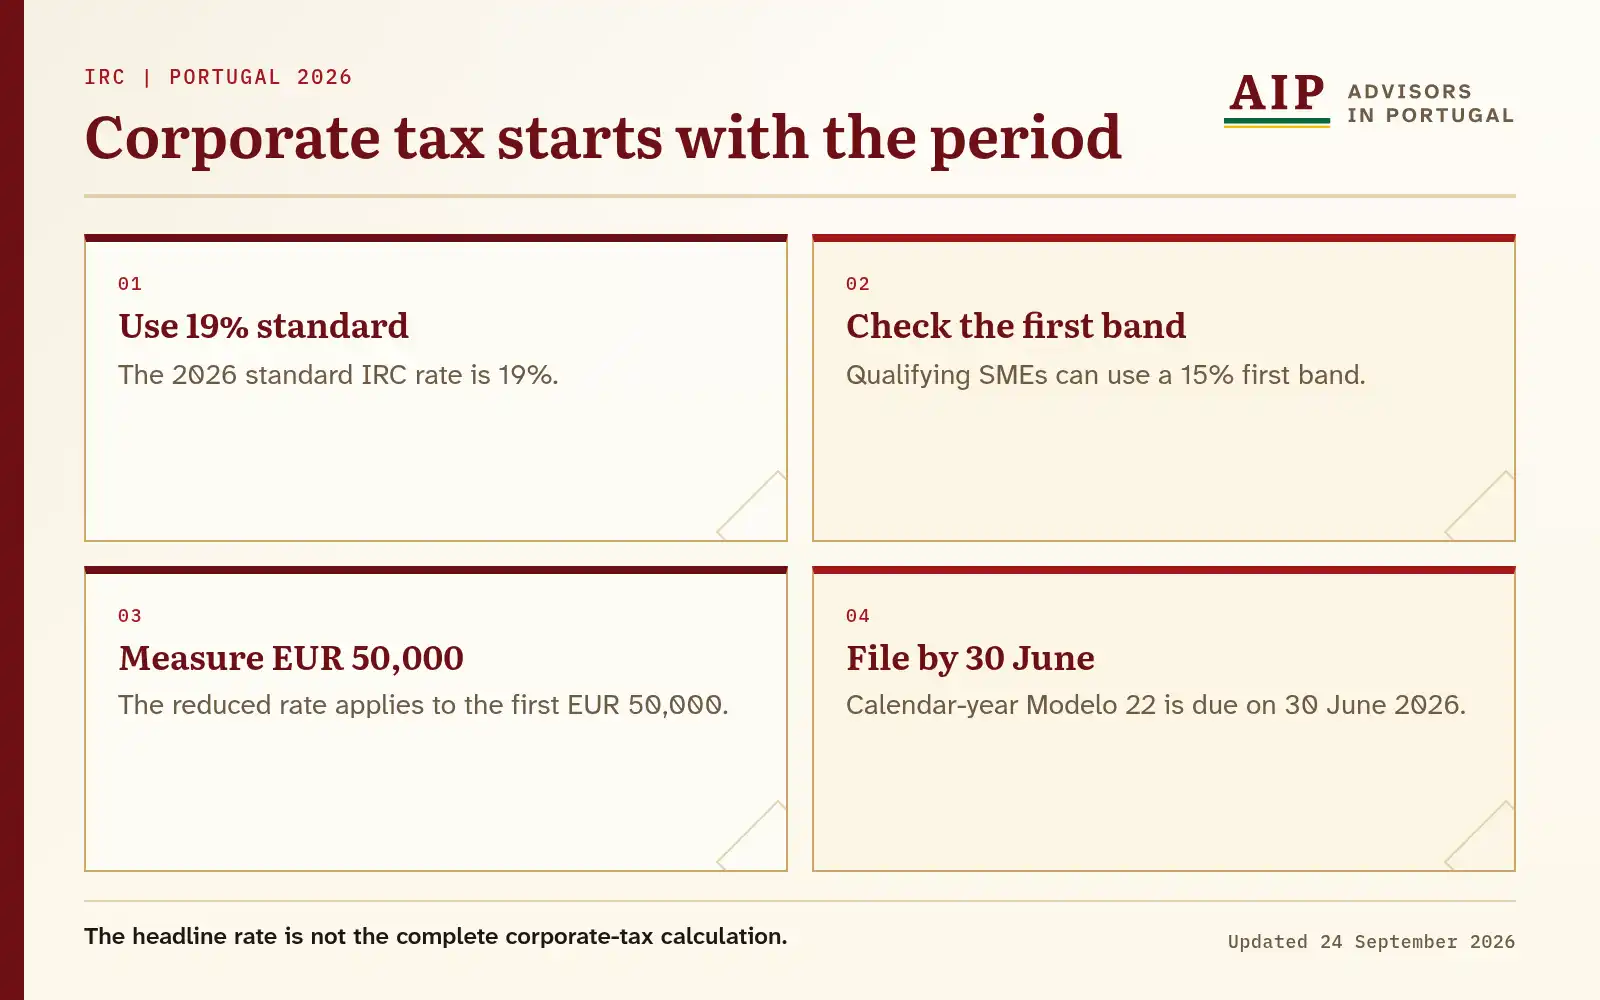
Diagram text version
Use 19 percent as the 2026 standard rate. Check the first band. Measure EUR 50,000. File Modelo 22 by 30 June.
Portugal taxes company profit under Imposto sobre o Rendimento das Pessoas Coletivas, or IRC. The standard rate is only the starting point. Your company may also need to account for a reduced rate, municipal or state surcharge, autonomous taxation, regional rules, reliefs and the filing calendar.
What Is the Portugal Corporate Tax Rate in 2026?
Article 87 of the CIRC, as amended by Lei n.º 64/2025, sets the standard IRC rate at 19% for tax periods beginning in 2026. The rate applies to taxable profit, not revenue.
Qualifying SMEs and small mid-caps use a 15% rate on the first EUR 50,000 of taxable income. The standard rate applies above that amount.
The headline rate does not include municipal surcharge, state surcharge or autonomous taxation. Each sits under a separate rule.
How Will the Standard IRC Rate Change?
Lei n.º 64/2025 created a binding transition in Article 87 of the CIRC. The standard rate is 19% for tax periods beginning in 2026, 18% for periods beginning in 2027 and 17% for periods beginning on or after 1 January 2028.
Your company should use the rate for the tax period it is calculating. A future statutory rate does not change a 2026 liability.
Which Companies Use the Reduced IRC Rate?
Qualifying SMEs and small mid-caps use 15% on the first EUR 50,000 of taxable income in 2026 under Article 87 of the CIRC. This is a band within the company’s taxable income, not a separate rate for all profit.
Portugal also has a simplified IRC regime for smaller companies under Article 86-A.
Which Surcharges Can Apply?
A municipality may levy derrama municipal of up to 1.5% of taxable profit under Article 18 of the Lei das Finanças Locais. The municipality sets its own decision, and reductions or exemptions may apply.
Article 87-A of the CIRC sets state surcharge bands on higher taxable profit:
- 3% on the portion above EUR 1.5 million through EUR 7.5 million.
- 5% on the portion above EUR 7.5 million through EUR 35 million.
- 9% on the portion above EUR 35 million.
The bands apply by portion. The top rate does not apply to the whole taxable profit.
How Does Autonomous Taxation Work?
Article 88 of the CIRC taxes specified expense categories separately from the company’s ordinary IRC calculation. The Autoridade Tributária e Aduaneira’s consolidated text sets 10% on representation expenses and 50% on undocumented expenses.
Passenger vehicles use acquisition-value bands. The rates are 8% below EUR 37,500, 25% from EUR 37,500 to below EUR 45,000 and 32% from EUR 45,000. The listed autonomous-tax rates increase by 10 percentage points when the taxpayer reports a tax loss, subject to the statutory exceptions.
How Do the Participation Exemption and Tax Loss Rules Work?
The participation exemption generally requires the company to hold at least 10% of the relevant entity for an uninterrupted period of one year. Other entity and anti-abuse conditions also apply under Articles 51 and 51-C of the CIRC.
Article 52 places no time limit on carrying tax losses forward. A later-year deduction is capped at 65% of that year’s taxable profit.
What Rates Apply in Madeira and the Azores?
Article 36-A of the Estatuto dos Benefícios Fiscais sets a 5% IRC rate through 31 December 2033 for qualifying Madeira IBC entities licensed through 31 December 2026. The entity must create one to five jobs within its first six months and make EUR 75,000 of qualifying investment within its first two years, or create at least six jobs within its first six months.
AICEP reports a 13.3% standard IRC rate in the Azores and a 10.5% rate for qualifying SMEs on the reduced-rate band.
When Does Your Company File Modelo 22 and IES?
The Autoridade Tributária e Aduaneira’s 2026 fiscal calendar sets these deadlines for a company with a calendar-year tax period:
- Modelo 22: 30 June 2026.
- IES/DA: 15 July 2026.
Your company must calculate its payment-on-account obligations and follow their calendar.
What Else Should an International Group Check?
Domestic withholding applies to dividends, interest and royalties paid to non-residents. An applicable double-tax treaty can reduce that withholding when the payment and formal requirements qualify.
An international group may also need to review transfer-pricing, permanent-establishment, participation-exemption and cross-border structuring rules.
Common questions
What is the corporate tax rate in Portugal in 2026?
Is the 19% rate the final amount every company pays?
What are the state surcharge rates?
Can a company carry tax losses forward?
When are Modelo 22 and IES due for a calendar-year company in 2026?
Can a treaty reduce withholding on a payment to a non-resident?
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.