Madeira Tax Benefits for Companies
Madeira company tax benefits centre on a 5% IRC rate for qualifying income through 2033 if a company receives its Madeira Free Zone licence by 31 December 2026. Your company must check which revenue streams qualify before it forecasts tax savings.
Diagram text version
Two listed pages cover Lisbon. One listed page covers Porto. Two listed pages cover Madeira.
The 5% IRC regime in Madeira, its licensing window, employment and investment conditions, annual limits and exclusions.
Which Madeira companies can use the 5% rate?
Estatuto dos Benefícios Fiscais Article 36-A(1) applies a 5% IRC rate to qualifying income of entities licensed in the Madeira Free Zone between 1 January 2015 and 31 December 2026, through 31 December 2033. Your company should identify its licensing date and the income covered by the article before modelling the rate.
The rate is not a general Madeira company rate. Article 36-A subjects the licensed entity to activity, employment, investment, taxable-income and annual-benefit limits. You should keep the licence and the records showing when activity began and how the income arose.
The current AT text of Article 36-A reflects amendments including Lei n.º 73-A/2025. You should use the wording governing the company’s actual tax period. A future operation needs the licensing window checked before any forecast assumes 5% through 2033.
Which activities and income qualify?
Estatuto dos Benefícios Fiscais Article 36-A(1)(a) to (c) covers specified industrial activities, international maritime or air transport and other qualifying service activities in the Madeira Free Zone. For the latter category, the provision restricts the qualifying income to transactions with other Free Zone entities or the other permitted counterparties in the provision. Your company should identify the counterparty and the source of each revenue stream.
The company licence, contracts and invoices are compared against the Article 36-A category. A service sold to a Portuguese resident business follows a different Article 36-A transaction analysis from a permitted non-resident transaction. You should maintain records that show which income meets the stated counterparty condition.
The article’s activity categories also affect when business must begin after licensing. Your company should set out the planned operation and expected customers before incorporation or licence steps. The classification under the article depends on the activity actually performed.
When must activity begin?
Estatuto dos Benefícios Fiscais Article 36-A(2) generally requires activity to start within six months of licensing and gives specified industrial, maritime and air activities one year. Your company should record the licence date and the evidence of the first qualifying activity.
A signed contract, an invoice and operational records may help establish when an activity actually began. Those records must show that activity began within the statutory deadline.
The start period sits beside the employment and investment conditions in Article 36-A(2). Your company should prepare a dated schedule of licensing, first activity, hiring and asset acquisitions. That schedule lets the statutory periods be read together without treating one completed administrative step as proof of all conditions.
How many jobs and how much investment are required?
Estatuto dos Benefícios Fiscais Article 36-A(2) gives two routes: create one to five jobs in the first six months and invest at least €75,000 in qualifying fixed assets within the first two years, or create at least six jobs in the first six months. Your company should identify the route supported by its actual hiring and investment plan.
The jobs must be linked to the Madeira operation. Employment contracts, payroll and workplace records are compared with the licence and the activity. Under the one-to-five-job route, you should keep asset acquisition and payment records that show the €75,000 threshold and the two-year period.
Your company should check the relevant dates from the licensing event and document the jobs actually created. The investment route and the six-job route are alternatives in the article, so the records should show which one the company claims.
What annual limits apply to the benefit?
Estatuto dos Benefícios Fiscais Article 36-A(3) limits the annual tax benefit by three alternative measures: 20.1% of regional gross value added, 30.1% of regional labour costs, or 15.1% of regional turnover. Your company should calculate the applicable measures from its Madeira operation for each tax period.
The regional figures are reconciled with accounting and payroll records. You should distinguish turnover from taxable profit and labour costs from the number of jobs. Each measure asks a different factual question about the business, so a single revenue estimate cannot replace the three calculations.
The alternative cap test concerns the benefit used in a year. Your company should keep the calculation with the tax return and the source accounts. That record will explain why a given amount of qualifying income received the reduced rate while another amount did not.
How much income can receive the 5% rate?
Estatuto dos Benefícios Fiscais Article 36-A(4) sets taxable-income ceilings by jobs created, beginning at €2.73 million for one or two jobs. Article 36-A(5) requires the relevant jobs to be maintained in each year. Your company should determine the actual job band before applying the rate to taxable income.
The ceiling limits the income to which the reduced rate can apply. It is distinct from the annual benefit caps in Article 36-A(3). Both tests are calculated from the company’s accounts and employment records. You should retain year-by-year evidence because Article 36-A(5) measures the jobs maintained in each later year.
Taxable income, gross revenue and the regional turnover cap are different amounts. Your company should reconcile each figure to the correct account and tax period. That distinction is necessary for a reliable estimate of the tax benefit.
Which companies or transactions are excluded?
Estatuto dos Benefícios Fiscais Article 36-A(8) excludes specified intragroup activities, listed sectors including steel, synthetic fibres, coal and shipbuilding. It also excludes specified agriculture, forestry, fishing, aquaculture and extractive activities. Your company should classify its actual business before treating a Madeira licence as tax eligibility.
Corporate accounts and ownership links show whether the intragroup exclusion in Article 36-A(8) applies. You should identify group counterparties and the nature of services charged to them.
Your company should describe the real transaction and maintain contracts and invoices that identify the counterparty. A careful classification before trading reduces the risk of making a tax forecast from income the statute excludes.
What evidence should a company keep?
Estatuto dos Benefícios Fiscais Article 36-A requires the licence, timely start of activity, specified jobs and investment, qualifying income and annual benefit limits. Your company should keep records for each condition throughout the years in which it claims the rate. The file should connect each revenue stream to a counterparty and each employee to the relevant period.
Invoices, contracts, payroll, asset registers and accounts are reconciled to the applicable paragraph. You should preserve the licence date, first-activity evidence and investment purchases because the statute measures several periods from licensing. The records should permit the income ceiling and the annual benefit cap to be recalculated for each year.
You should obtain the operative licensing instructions for your specific activity before submitting documents. Those instructions are compared with the Article 36-A tax conditions and the company records. The administrative submission must follow the applicable licence procedure.
What changed in the current 2026 text?
The current AT publication of Estatuto dos Benefícios Fiscais Article 36-A records wording amended by Lei n.º 73-A/2025, including paragraphs 1 and 10. Paragraph 1 now states the licensing window through 31 December 2026 and the 5% period through 31 December 2033. Your company should use the current wording for a proposed 2026 licence.
A pre-existing licence is compared with the wording applicable to its tax periods. You should retain the licence and earlier tax records so a later analysis can distinguish a continuing entitlement from a newly proposed operation.
The Article 36-A dates create two different decisions: whether a company can enter the specified licensing window and for how long qualifying income may receive the reduced rate. Your company should record both dates in its forecast and apply the other statutory limits year by year.
You should distinguish the company’s trading forecast from the cap calculation. The same period is reconciled across the income ledger, payroll record and tax computation. You should retain the evidence for each period because the number of maintained jobs can change the income ceiling while turnover and labour costs can change the annual benefit cap. The two tests therefore require separate workings, even where the company’s business activity remains the same.
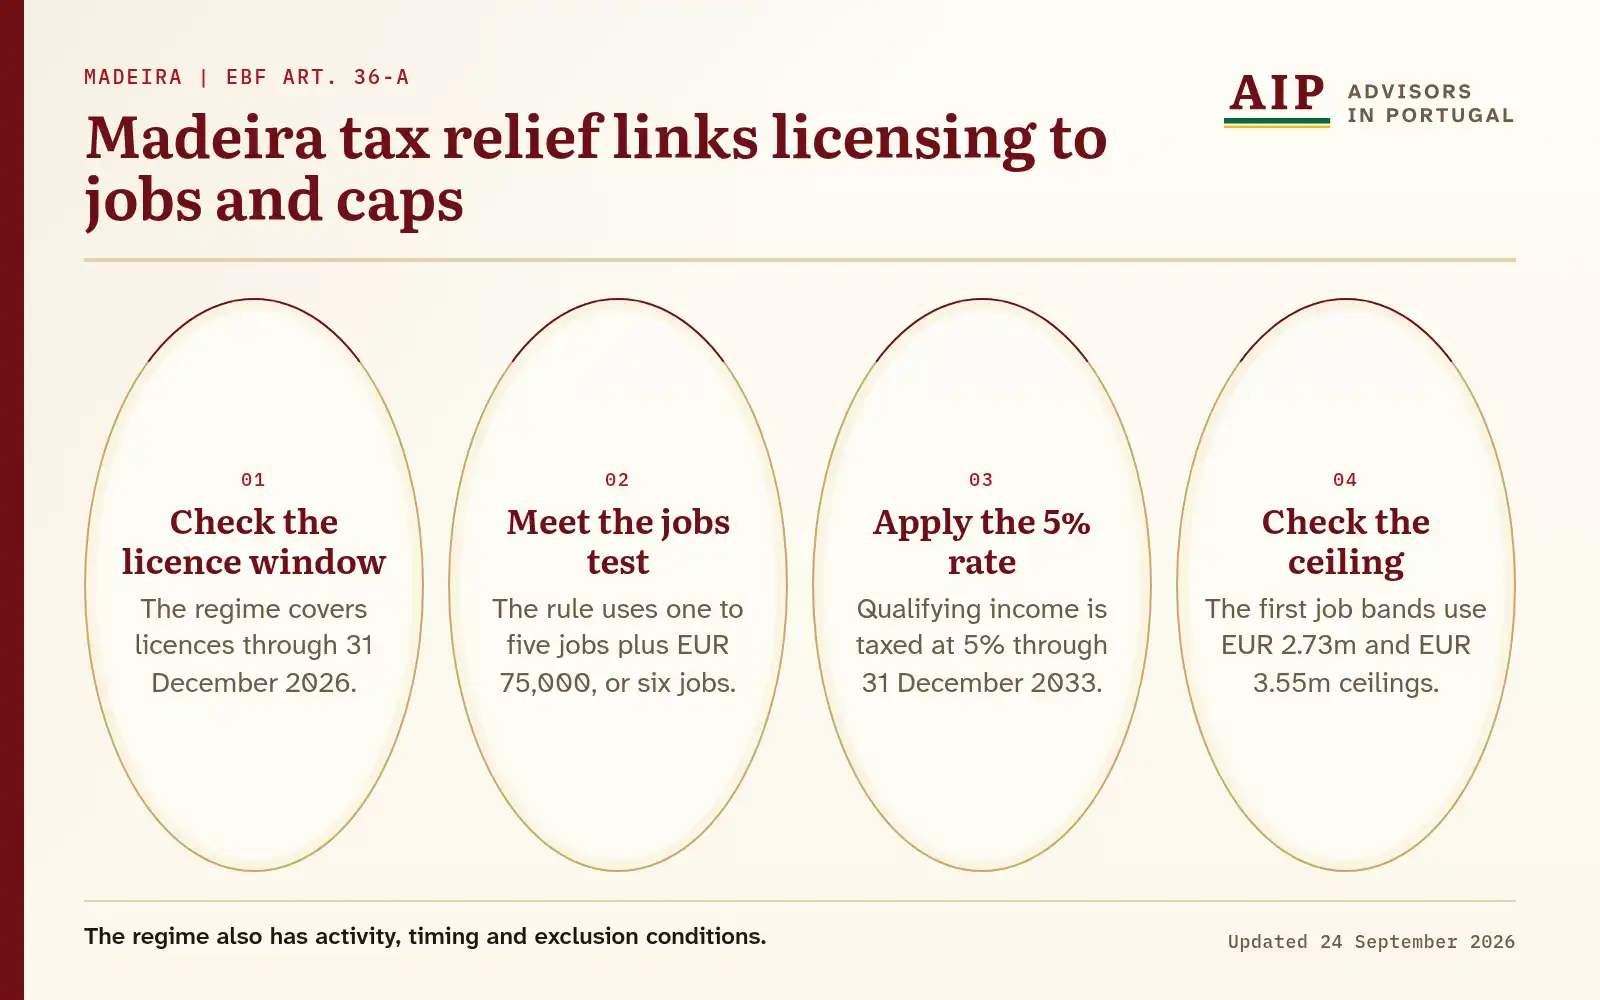
Diagram text version
Check the licence window. Meet the jobs test. Apply the 5 percent rate. Check the job-based ceiling.
Common questions
Which non-resident customers can generate qualifying service income?
Can an entity subject to a recovery injunction qualify?
Does Article 36-A set a universal licensing fee?
What is the largest taxable-income band stated in the article?
Are financial and insurance activities included?
Can a company in difficulty use the regime?
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.