Investment Incentives in Portugal
Investment incentives in Portugal include Portugal 2030 calls and the RFAI, which covers only qualifying investment in listed sectors by IRC taxpayers that meet Article 22 conditions. No grant percentage or deadline can be applied responsibly to your company without a current notice.
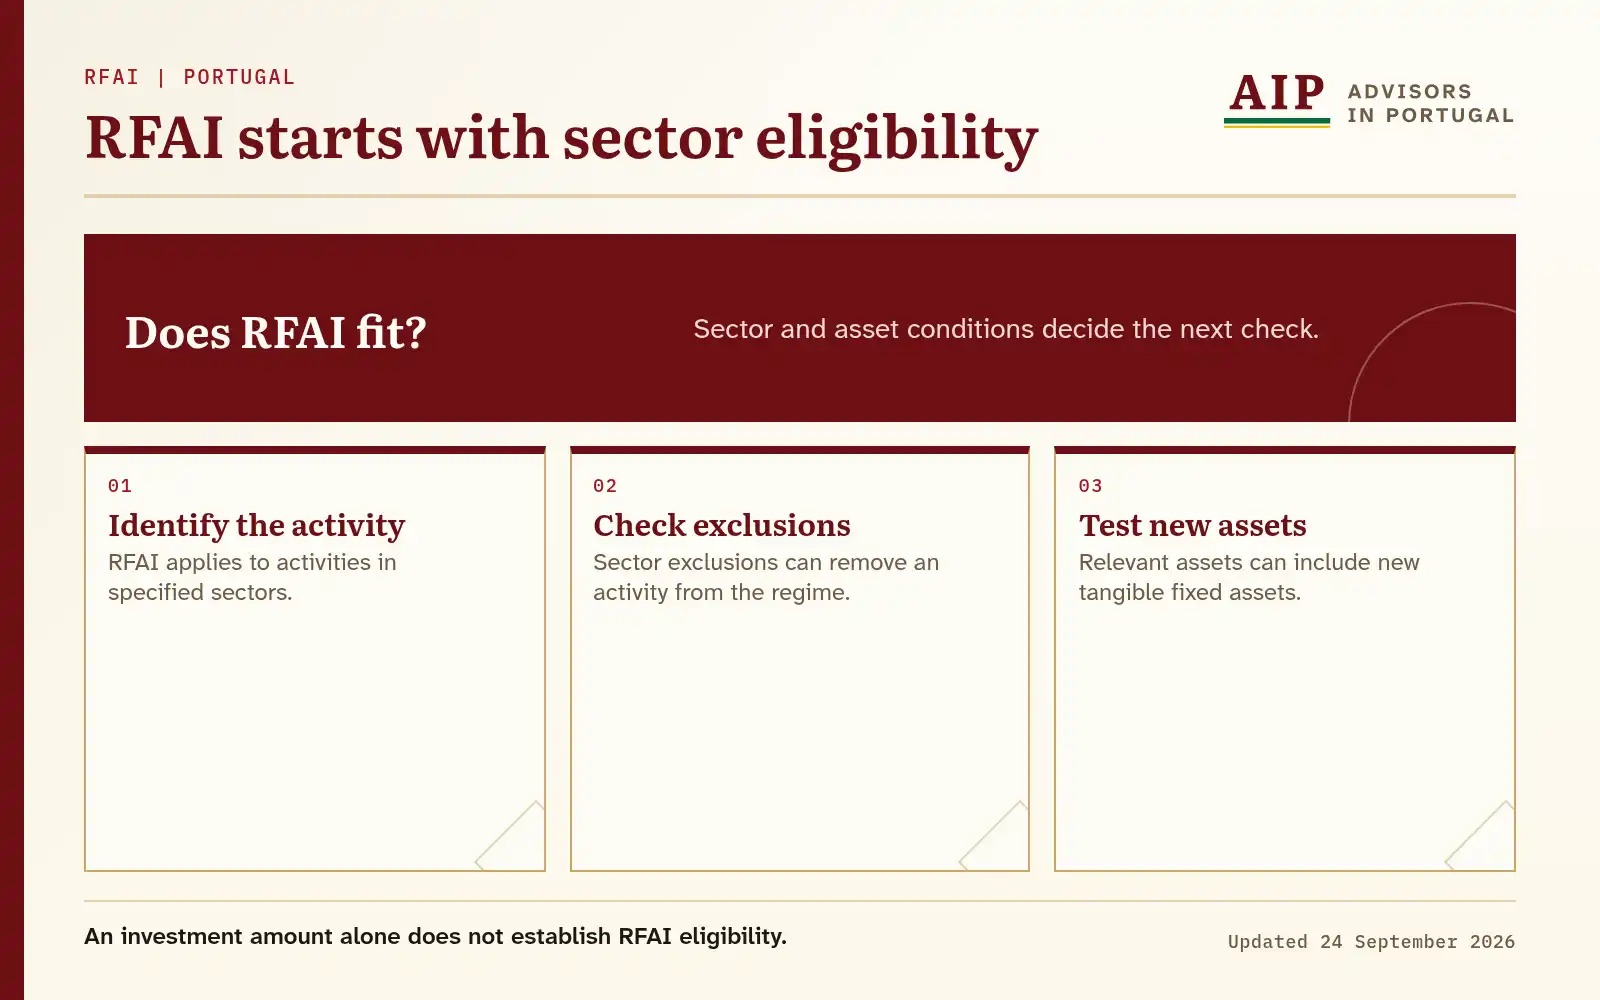
Diagram text version
Identify the activity. Check exclusions. Test the new assets.
How RFAI conditions and Portugal 2030 calls affect a Portuguese company’s investment project and tax records.
Which Portuguese investment incentive fits a project?
Código Fiscal do Investimento Article 22 governs the Regime Fiscal de Apoio ao Investimento, or RFAI, for IRC taxpayers carrying out qualifying investment in the sectors it identifies. Portugal 2030 support works through individual calls with their own notices. Your company should separate a proposed tax benefit from a grant application before budgeting an investment.
Article 22 first asks whether the activity falls within the statutory sectors and whether the investment meets its asset and company conditions. Your company should document its sector, the investment assets and the jobs actually created against every Article 22 condition. Each Article 22 condition is tested against the company’s actual activity, assets and tax position.
Portugal 2030 directs applicants to the relevant notice for the project. Your company should identify the call, applicant category, eligible operation and submission window in that notice.
Which businesses may claim RFAI?
Código Fiscal do Investimento Article 22(1) makes RFAI available to IRC taxpayers that carry out an activity in the Article 2 sectors and meet the Article 22 conditions. Your company should identify its principal activity and the entity that will own the qualifying investment.
Article 22(4) requires organised accounts under the accounting normalisation system. It requires the company to have its tax and social-security position regularised. Tax certificates, accounts and the project’s asset owner can be compared before a claim is built.
Article 22(4)(e) excludes a company in difficulty under the relevant definition. The company must meet the applicable job-creation and retention conditions. You should document the baseline and the jobs linked to the project, because an expected hiring plan is different from evidence of the statutory condition in the claim period.
Which investment costs qualify for RFAI?
Código Fiscal do Investimento Article 22(2) treats investment in specified tangible fixed assets as relevant, subject to its exclusions. Código Fiscal do Investimento Article 22(2)(b) covers certain intangible technology-transfer assets, on conditions set out in the current article text. Your company should identify each asset and its acquisition record.
The same article addresses costs tied to job creation in the qualifying investment framework. You should separate asset invoices from salary records and link each item to the project. Each item must be matched to the correct Article 22 paragraph before it enters the RFAI calculation.
Your company should preserve acquisition contracts, invoices, proof of payment, asset registers and the use of the asset. Those records allow the Article 22 conditions to be checked against the business activity.
How long must investment and jobs be maintained?
Código Fiscal do Investimento Article 22(4) requires relevant investment to remain in the company for at least three years for a small or medium enterprise and five years for other companies. The same condition set requires jobs to be created and maintained where applicable. Your company should identify its enterprise category and the start of each asset-retention period.
An asset register can show when each item entered service and whether it later moved or was disposed of. Payroll records can show the job position linked to the investment and its continuation. Those dates can be compared with the claim and the Article 22 requirements. You should keep the supporting records throughout the statutory period.
A change to the project after the claim may affect the factual basis for the benefit. Your company should examine a sale, transfer or restructuring against the retention conditions before acting.
What tax and accounting conditions apply?
Código Fiscal do Investimento Article 22(4) requires organised accounting and a regularised tax and social-security position. Your company should check those conditions for the claimant before calculating any possible tax effect. The article states conditions on the taxpayer as well as on the assets.
You should keep the accounting entries and the underlying investment records aligned. The fixed-asset ledger can be reconciled to invoices and the tax return for the relevant period. The RFAI claim should identify which company acquired and uses each item, especially where a group has several Portuguese entities.
The benefit depends on continued compliance with the statutory conditions. Your company should retain tax and social-security status evidence from the relevant stage and preserve later records that show the investment stayed with the company. Those records allow a later review to reconstruct the facts without guessing from a headline project budget.
How should a company assess a Portugal 2030 call?
Portugal 2030 says an applicant must read the notice for the call that supports its project. The notice sets who may apply, what expenditure and operations qualify, the submission channel and the closing date. Your company should start with the identified notice and match its project dates to that text.
A Portugal 2030 announcement in February 2026 described research, development and innovation incentives and gave a 17:00 on 30 April 2026 closing time for that call. That date has passed. You should treat it as the terms of a historical call, not an open application window. A later published notice has to be compared with the actual research or investment plan.
The project description, budget and applicant identity need to agree with the notice being used. You should keep the notice version and submission acknowledgement with the project file. Without a current notice, a grant percentage, co-financing amount or application deadline cannot be applied responsibly to your company.
Can the company combine tax and grant support?
Código Fiscal do Investimento Article 22 states the RFAI eligibility conditions for an IRC taxpayer. A Portugal 2030 grant notice separately sets its own support terms. Your company should identify the same costs and activities in both proposed claims before assuming they can be combined. The specific aid and cumulation rules must be read in the governing instruments for those claims.
One schedule of costs can show which invoices, assets and jobs appear in each proposal. You should disclose any other public support for the project in the application fields that require it.
You should calculate the aid ceiling from the governing tax instrument and the current grant notice for the particular project and location. Your company should keep that calculation with its cost schedule and each claim.
What should the company retain for a claim?
Código Fiscal do Investimento Article 22 requires the taxpayer to satisfy the investment, accounting, tax-status and retention conditions. Your company should keep a schedule linking each claimed item to the statutory condition and the accounting record. The schedule should show acquisition, ownership, use and the period during which the asset remains with the claimant.
Job records, investment invoices and tax-status evidence can be compared with the period in which the claim is made. You should preserve the claim calculation and the corporate tax return alongside those records. Where another group company pays an invoice or owns an asset, the identity should be resolved before the claimant includes the cost.
For a Portugal 2030 application, the call notice determines the documents and channel. Your company should save the notice used, the submitted application and acknowledgments.
What changed for 2026 investment applications?
The announced window is now closed. Your company should use a later published notice before assuming another project can apply. The closing date applies to that particular call and does not alter Código Fiscal do Investimento Article 22.
The current Article 22 text remains the starting point for an RFAI analysis. The company’s tax period and investment dates are examined against the text in force for that period. You should retain the date of each acquisition and the date of the tax claim so the correct version can be identified.
An investment plan may involve tax support, grants or both. Your company should build a separate eligibility schedule for each instrument and then compare any overlapping costs. That order makes the different conditions visible before an application or return is finalised.
Common questions
Can an indirectly assessed taxpayer use RFAI?
Must an RFAI tangible asset be new?
Where did the cited 2026 call receive applications?
Which definition of a company in difficulty does RFAI use?
Does the RFAI article supply a SIFIDE II application route?
Which intangible costs can Article 22 cover?
Related guides
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.