Madeira Company Formation
Madeira company formation provides ordinary incorporation with standard articles for groups that plan a qualifying activity in Madeira. We test the plan against Article 36-A, because its conditional 5% IRC rate depends on jobs and investment within the statutory periods.
First conversation free Reply within one business day
Who Needs Madeira Company Formation
- Your group plans to form a Portuguese company in Madeira for a qualifying business activity.
- Your company wants its International Business Centre conditions checked by a certified accountant before it relies on the reduced IRC rate.
- Your shareholders need the ordinary company-registration work and the Madeira tax conditions handled together.
- Your business needs an employment, investment and activity-start plan that a certified accountant can compare with Article 36-A of the Estatuto dos Benefícios Fiscais.
Your company needs an ordinary mainland Portuguese company with no Madeira activity or International Business Centre question; the service covers Madeira formation and the accounting and tax records that support the International Business Centre conditions.
What's Included in Madeira Company Formation
You get a quote in writing before any work starts.
- Formation file. A specialist collects the shareholder, activity and governance details needed for the standard articles before the company is formed.
- Ordinary incorporation. The agreed Portuguese company-registration steps for the Madeira entity are prepared with standard articles of association.
- Article 36-A tax review. A certified accountant compares the planned activity, employment and investment with the verified statutory conditions.
- Activity-start records. A timeline of the commercial start is kept next to the statutory period that applies to the proposed activity.
- Benefit-limit review. A certified accountant checks the statutory activity and annual benefit limits against the business plan.
- Accounting and tax setup. A certified accountant prepares the agreed opening and recurring work for the formed company.
Diagram text version
Two listed pages cover Lisbon. One listed page covers Porto. Two listed pages cover Madeira.
What Your Company Needs to Provide
- Shareholder and director details
- Identification, NIFs, ownership percentages, directors and beneficial owners for the proposed company.
- Business activity
- A specific description of the services, products, markets, customers and countries involved.
- Employment plan
- The proposed roles, number of jobs, hiring dates and location of the work.
- Investment plan
- The assets, expenditure, amounts and timing that your company expects to use for the Madeira activity.
- Activity-start plan
- The incorporation date, commercial preparations and expected date on which the company will begin its activity.
- Financial projections
- Expected income, costs, transactions and taxable profit for testing the statutory benefit limits.
How Madeira Company Formation Works
The International Business Centre, employment, investment, accounting and corporate-tax points are noted for the certified accountant.
-
Shareholder and activity review
The ownership, governance, proposed activity and commercial purpose of the Madeira company are collected.
-
International Business Centre tax check
A certified accountant compares the activity, employment, investment and timing facts with Article 36-A.
-
Incorporation file
The incorporation file is prepared with standard articles of association and the ownership details.
-
Commercial registration
A specialist files the agreed incorporation steps with IRN and the Registo Comercial.
-
Employment and investment evidence
Your company records the jobs, investment and activity-start evidence needed for the chosen business plan.
-
Accounting and tax setup
A certified accountant handles the agreed opening work and maps the records needed for ongoing compliance.
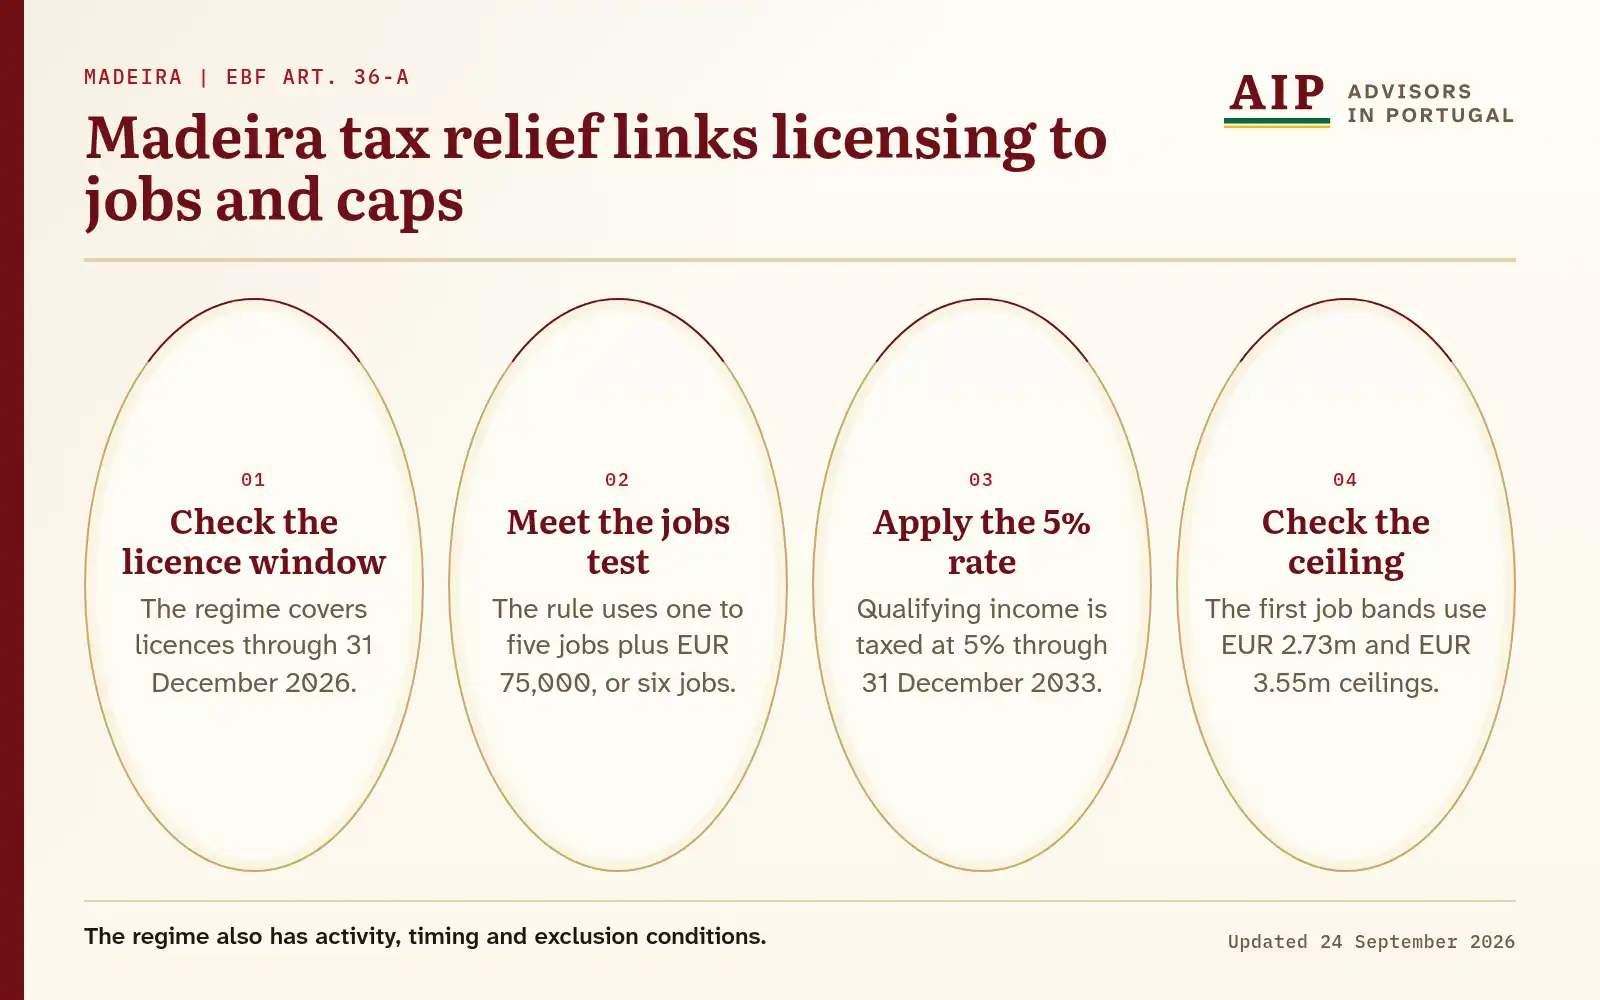
Diagram text version
Check the licence window. Meet the jobs test. Apply the 5 percent rate. Check the job-based ceiling.
Timing and Possible Delays
Set by the formation and statutory conditions
The work is planned around the ownership, activity, incorporation route, employment plan, investment evidence and commercial start.
What delays it
The work takes longer when shareholder documents, activity details, job plans, investment records or financial projections are incomplete.
What to prepare now
Your company gathers its ownership, activity, employment, investment, timing and financial records before the work begins.
Formation Evidence, Activity Start and Benefit Limits
Formation file before the tax analysis
Your company keeps the constitutional documents, ownership map and activity description in the same formation file. A certified accountant can then compare the entity that was registered with the business facts used for the Article 36-A review.
Evidence of the activity start
Your company records the first contracts, invoices, staff start dates and operational expenditure that show when the Madeira activity began. Your company should preserve those records with the applicable six-month or one-year start calculation.
Annual records for the statutory limits
Your accounting file separates qualifying activity, employment evidence, investment and taxable results for each relevant period. A certified accountant uses that separation to support the annual calculation before the company applies the reduced rate.
Set out your Madeira company plan
Describe who will own the company, what it will do, how it will employ and invest and when the activity will start.
Common questions
What tax rate can apply in the Madeira International Business Centre?
What is the current licensing cut-off in Article 36-A?
What employment and investment conditions apply?
When must the Madeira company begin its activity?
Does every Madeira company qualify for the 5% rate?
Does a Madeira company still use Portuguese incorporation steps?
Are there limits on the Madeira tax benefit?
What changed for the regime in the 2026 State Budget?
Which records support the tax review?
How is the Madeira formation handled?
How the Service Works
-
One team for the whole case.
The formation, tax, employment and accounting records for the company stay in one file, and a certified accountant handles the tax and accounting work.
-
English or Portuguese.
English or Portuguese, whichever you are most comfortable in.
-
A quote in writing before work starts.
You get a quote in writing before any work starts. You are told plainly if a case is outside the service.
Contact us
Your request is in
Every request is read in house. The requirements are assessed, and a reply by email sets out the appropriate next steps.
Every enquiry is read in house, and the aim is a reply within one business day.
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.