Portugal Holding Company Setup and Compliance
A Portugal holding company holds a group’s participations in operating companies, and we form it with standard articles and maintain its accounts. Article 51-C of the CIRC makes an uninterrupted 24-month holding period relevant to qualifying gains on disposal.
First conversation free Reply within one business day
Who Needs Portugal Holding Company Setup
- Your group is considering a Portuguese company to hold participations in operating companies.
- Your company plans an SGPS and needs it formed and registered with IRN and the Registo Comercial.
- Your group expects dividends or a future disposal and needs the company's tax filings and accounts kept in order.
- Your shareholders are outside Portugal and the company needs its records and filings ready before funds move.
Your company needs ordinary operating-company formation without a holding structure if it will carry on the trading activity itself; that work is handled as a separate company-formation engagement.
What's Included in Holding Company Setup
You get a quote in writing before any work starts.
- Group information. A specialist collects the shareholders, subsidiaries, jurisdictions and planned participations that the company file needs.
- Company formation. The formation steps are prepared with standard articles, and the commercial registration is filed with IRN and the Registo Comercial.
- Registered office and company records. The service includes a registered office. A specialist keeps the company secretarial records and files the beneficial-owner (RCBE) declaration.
- Tax compliance filings. A certified accountant prepares the company's tax compliance filings, including Modelo 22 and IES.
- Ongoing accounting. A certified accountant keeps the accounts and prepares the accounting, corporate and tax filings that follow formation.
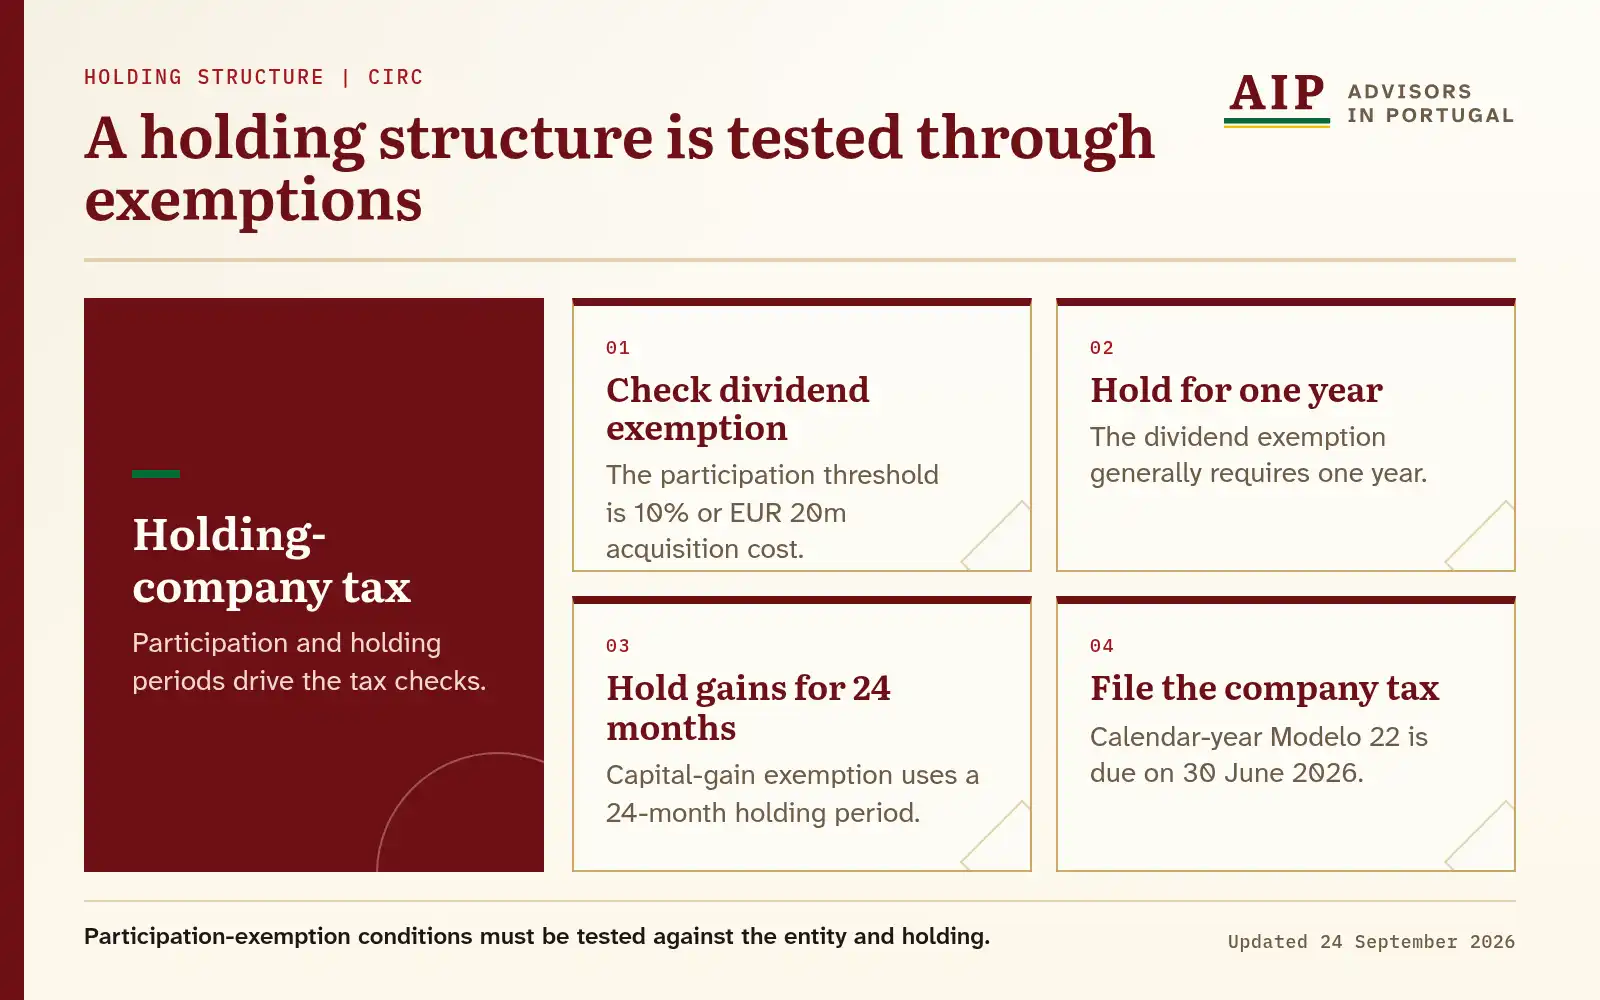
Diagram text version
Check 10 percent or EUR 20 million. Hold for one year. Check the 24-month gain period. File Modelo 22 by 30 June 2026.
What Your Group Needs to Provide
- Group chart
- The current and proposed shareholders, subsidiaries, ownership percentages and countries involved.
- Investment purpose
- The commercial reason for the structure and the participations the Portuguese company would hold.
- Transaction plan
- Expected acquisitions, dividends, financing, reorganizations and disposals.
- Entity documents
- Available constitutional, registry and beneficial-owner documents for the companies and shareholders in the structure.
- Financial information
- The acquisition cost, expected income and available accounts needed for the accounting and tax filings.
- Shareholder residence
- The tax residence of each shareholder that may receive a distribution, and whether it is an individual or a company (with its company type).
How Portugal Holding Company Formation Works
A specialist handles the company filings with IRN and the Registo Comercial. A certified accountant handles the tax compliance filings with the Autoridade Tributária e Aduaneira and the accounting.
-
Group and ownership mapping
The file starts with the current group chart, the proposed Portuguese company and the participations it would hold.
-
Company details
You confirm the company purpose, company type and capital. Decreto-Lei n.º 495/88 is generally understood to define an SGPS by the management of participations in other companies.
-
Commercial registration
A specialist prepares the formation steps with standard articles and files with IRN and the Registo Comercial.
-
Tax and accounts set-up
A certified accountant sets up the accounting and the tax compliance filings that the company needs after formation.
Timing and Possible Delays
Set case by case
The sequence runs through the entity documents, company formation and the accounting and tax set-up.
What delays it
More time is needed if the ownership chain is incomplete, foreign entity documents need further preparation or the company purpose changes.
What to prepare now
Your group prepares the ownership chart, entity documents, proposed participations, transaction plan and shareholder-residence information before the work begins.
Tax and Compliance After Formation
Participation exemption conditions
Article 51 of the CIRC generally requires a direct participation of at least 10 percent, or an acquisition cost of at least EUR 20 million, held for one year, together with its other conditions. Article 51-C applies separate conditions and exclusions to qualifying gains and losses and makes an uninterrupted 24-month holding period relevant. The entity, participation and transaction each have to meet the conditions before the company relies on either provision.
Corporate tax and filing dates
Article 87 of the CIRC sets the standard IRC rate at 19% for 2026, 18% for 2027 and 17% from 2028. The same article sets a 15 percent rate on the first EUR 50,000 of taxable income for eligible SMEs. The Autoridade Tributária e Aduaneira’s 2026 fiscal calendar sets 30 June 2026 for Modelo 22 and 15 July 2026 for IES/DA for a calendar-year company.
Non-resident shareholder distributions
The shareholder’s residence, whether it is an individual or a company, and supporting evidence are established before a cross-border distribution. Relief from withholding depends on the relevant treaty and domestic-law conditions.
Set out your holding-company plan
State who will own the company, which participations it will hold and which distributions or disposals you expect. The reply sets out the setup and compliance work that fits.
Common questions
What is an SGPS in Portugal?
Must every Portugal holding company be an SGPS?
Which company form can a Portuguese holding company use?
When can dividends qualify for the participation exemption?
When can a share disposal qualify for the capital-gain exemption?
What corporate tax rate applies to a Portugal holding company in 2026?
Does the participation exemption apply automatically?
When does a calendar-year holding company file Modelo 22 and IES?
How are dividends to a non-resident shareholder handled?
How is the holding-company work handled?
How the Service Works
-
One team for the whole case.
The company filings, tax filings and accounting come from the same team.
-
English or Portuguese.
English or Portuguese, whichever you are most comfortable in.
-
A written quote before work starts.
You get a quote in writing before any work starts. A case outside the service is flagged plainly.
Contact us
Your request is in
Every request is read in house. The requirements are assessed, and a reply by email sets out the appropriate next steps.
Every enquiry is read in house, and the aim is a reply within one business day.
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.