Inheritance Tax in Portugal: Stamp Duty Guide (2026)
Inheritance tax in Portugal is a 10% Stamp Duty charge, and spouses, de facto partners, descendants and ascendants are exempt. The cabeça de casal must file Modelo 1 ISTG by the end of the third month after the death, even when every heir is exempt.
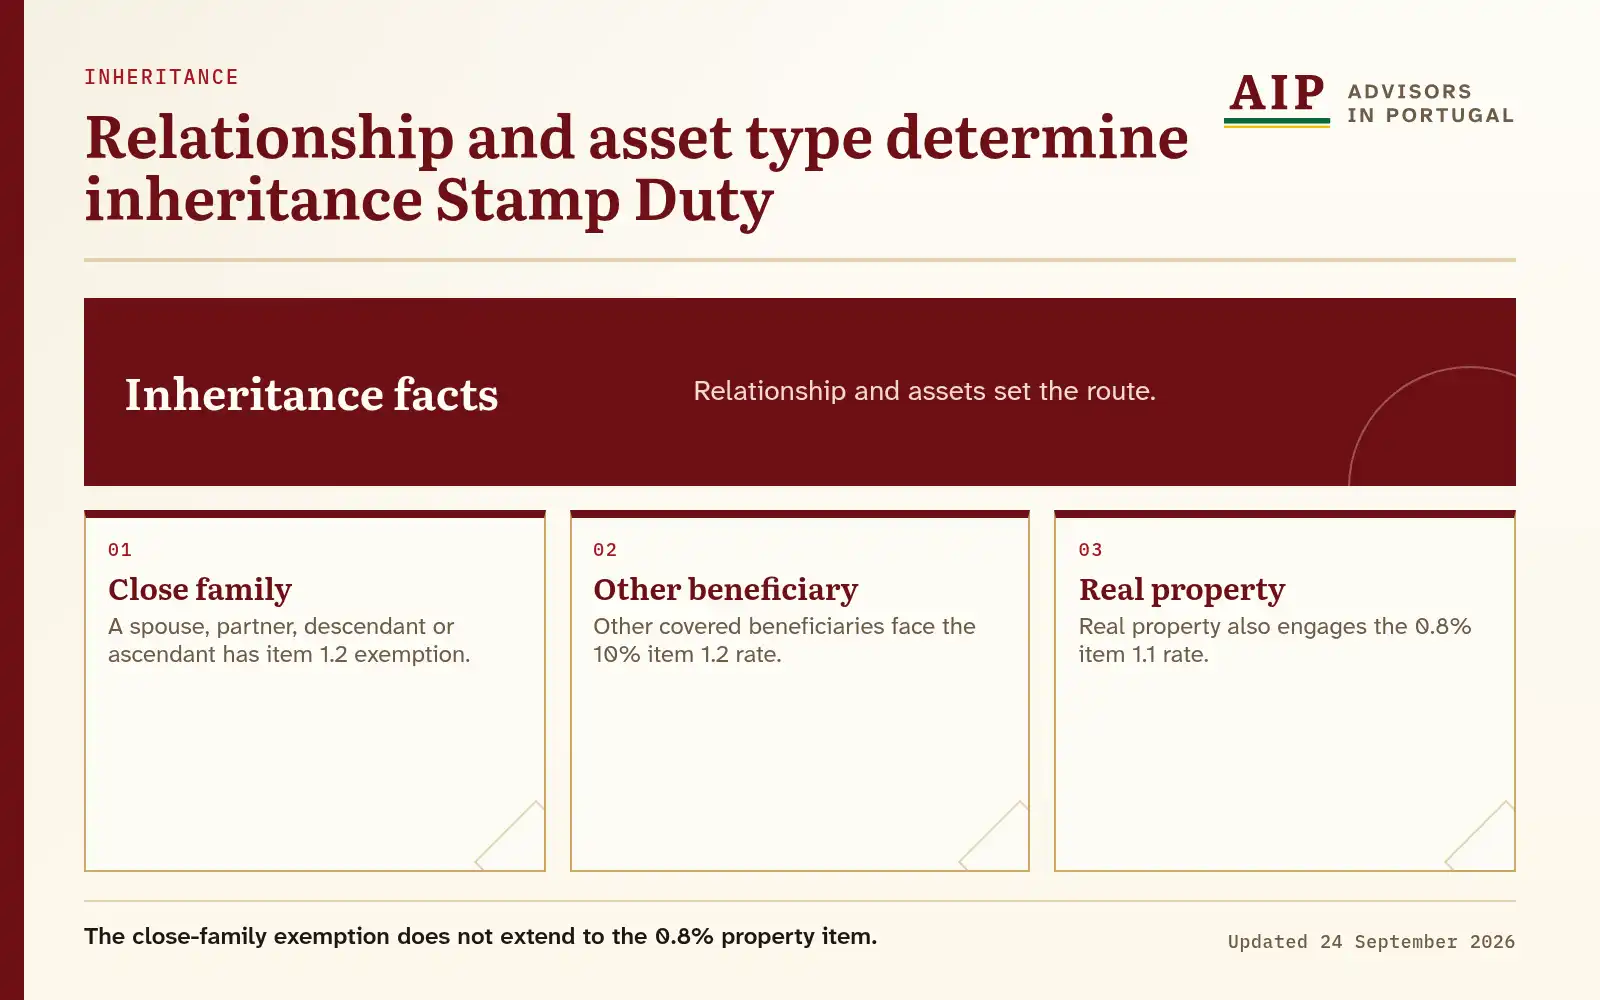
Diagram text version
A spouse, partner, descendant or ascendant has item 1.2 exemption. Other covered beneficiaries face the 10% item 1.2 rate. Real property also engages the 0.8% item 1.1 rate.
Portugal does not charge a separate tax called inheritance tax. It uses Stamp Duty on gratuitous acquisitions, including transfers on death. The beneficiary, the asset and the family relationship determine whether the 10% item 1.2 charge applies.
Property can add a separate 0.8% item 1.1 charge. Probate, the tax declaration and the applicable succession law also remain relevant when the main family exemption removes the 10% charge.
Does Portugal Have Inheritance Tax?
Item 1.2 of the Stamp Duty General Table sets a 10% charge on gratuitous acquisitions, including inheritances, when no exemption applies. Portugal therefore taxes some inheritances through Stamp Duty, although it does not use a separate inheritance-tax heading.
The tax result does not decide who inherits. Portuguese succession law and Regulation (EU) No 650/2012 address the applicable law and protected heirs. The Stamp Duty Code addresses the Portuguese charge.
Who Is Exempt From Stamp Duty on an Inheritance?
Article 6 of the Stamp Duty Code exempts a spouse or de facto partner, descendants and ascendants from the 10% item 1.2 charge. A child, grandchild, parent or grandparent can fall within that exemption based on the family relationship.
Other beneficiaries may face the 10% charge. Each beneficiary and each Portuguese asset is assessed separately. An exemption from item 1.2 does not remove the separate item 1.1 treatment for Portuguese real estate.
How Is Inherited Property Taxed?
The Stamp Duty General Table sets 0.8% under item 1.1 for Portuguese real-estate transfers and 10% under item 1.2 for gratuitous acquisitions. The close-family exemption does not cover item 1.1.
The value and treatment of a particular inherited property follow the applicable valuation rules and the estate’s declared asset information.
What Changes When the Deceased or Heir Is Non-Resident?
The estate must notify the Autoridade Tributária e Aduaneira when the deceased owned assets situated in Portugal. This remains mandatory when every heir is exempt from the 10% charge.
Residence alone does not settle the whole analysis. The analysis of a cross-border estate also depends on the type and location of the asset, the deceased’s circumstances, each beneficiary and the applicable succession law.
When Must the Estate Notify the Tax Authority?
The cabeça de casal, the estate representative, must submit Modelo 1 ISTG by the end of the third month following the death, according to the Autoridade Tributária e Aduaneira.
Habilitação de herdeiros is a separate civil-registration or notarial step. You track the tax notification deadline separately from that step.
How Does Forced Heirship Work in Portugal?
The Portuguese Civil Code protects the legitimate share of a spouse, descendants and ascendants. The reserved share depends on which protected heirs survive, so no single fraction applies to every family.
The will and estate plan are read against the actual family and the protected heirs where Portuguese succession law applies.
Can a Will Choose Another Country’s Succession Law?
Regulation (EU) No 650/2012 generally points to the law of the deceased’s habitual residence. Article 22 permits a person to choose the law of their nationality to govern the succession.
The Regulation applies in Portugal and its choice-of-law rule is not limited to EU nationals.
Are Lifetime Gifts Taxed the Same Way?
Gifts are gratuitous transfers under the Stamp Duty Code and use the same item 1.2 framework. A spouse or de facto partner, descendants and ascendants use the same family exemption when they receive a qualifying gift.
Portuguese real estate can still bring item 1.1 into the calculation.
What Happens When an Heir Sells Inherited Property?
A later sale is separate from inheritance Stamp Duty. Portuguese IRS capital-gains rules apply to the sale, and the calculation depends on the seller’s residence and the transaction facts.
Does a Foreign Will Work in Portugal?
Recognition and execution depend on the will, the applicable succession law and the documents needed for the Portuguese assets. A foreign will does not automatically need a Portuguese replacement, and it should not be assumed to work without review.
The will, the choice-of-law clause and the estate documents need review before the heirs act on them.
Common questions
Is there inheritance tax in Portugal?
Do children pay the 10% Stamp Duty charge on an inheritance?
Must an exempt heir still report the death?
What is the deadline for the Portuguese Stamp Duty declaration?
Can a will choose the law of the deceased's nationality?
Does a foreign will always need a Portuguese replacement?
Is a later sale of inherited property taxed separately?
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.