Probate in Portugal: Heirs' Declaration, Stamp Duty Filing and Partition
Probate in Portugal starts with the habilitação de herdeiros, which declares the heirs, and ends when the inherited property is registered in their names. The Imposto do Selo death declaration must also be filed, and the IRN fee for a habilitação starts at EUR 150.
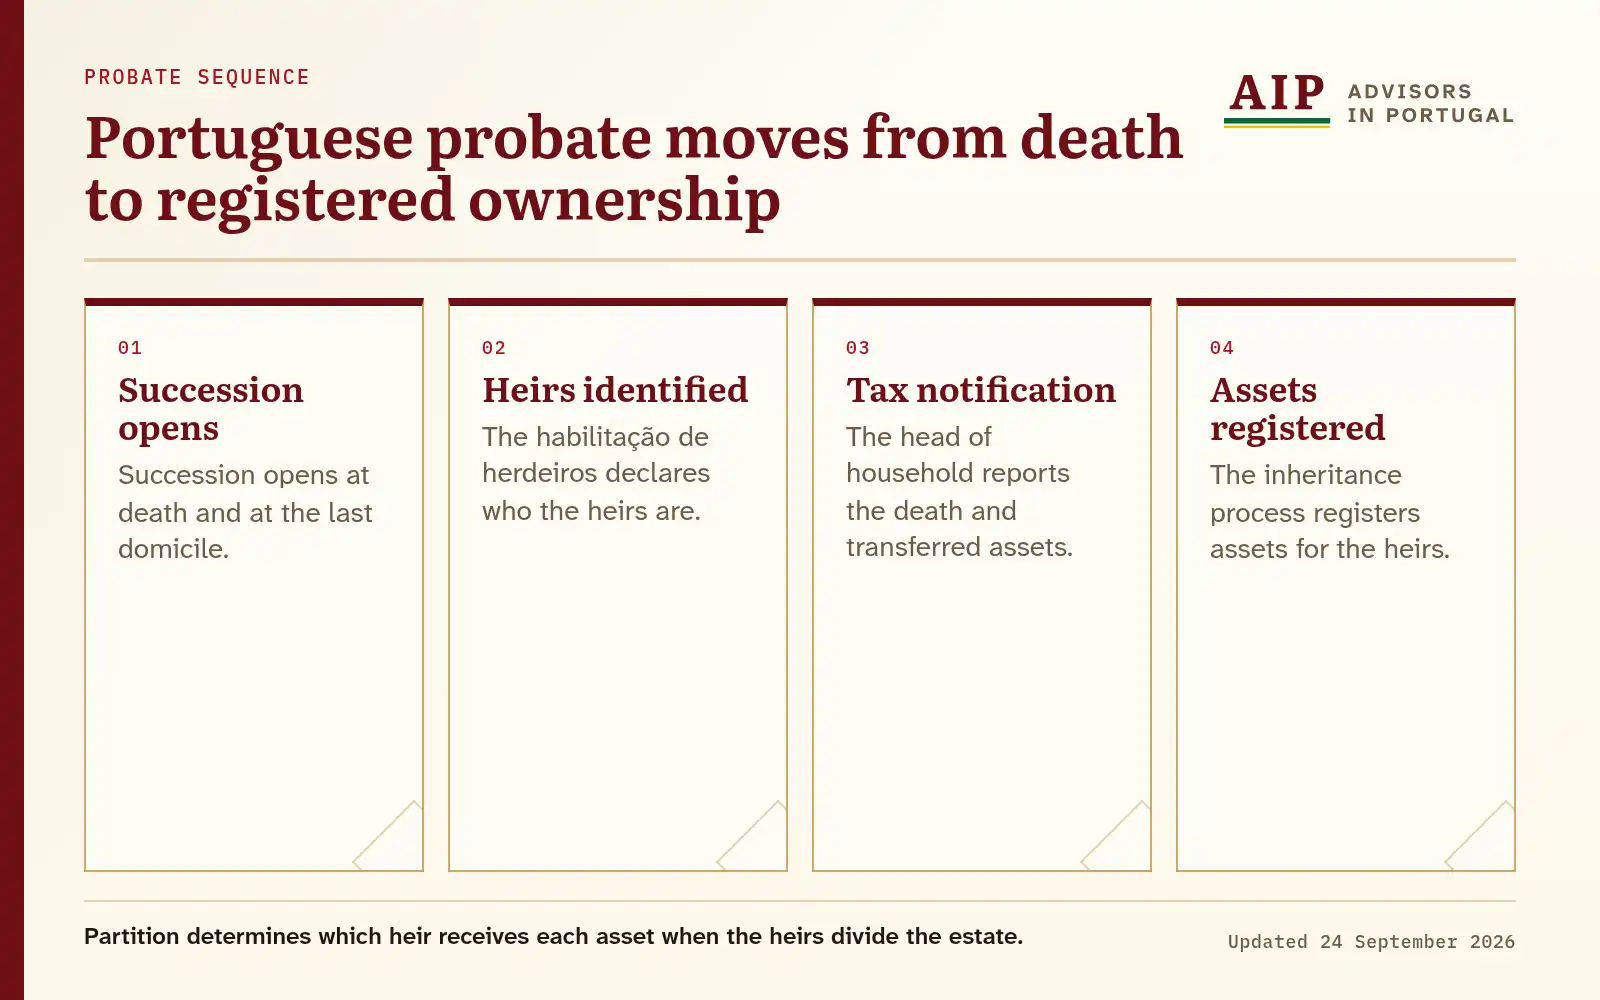
Diagram text version
Succession opens at death and at the last domicile. The habilitação de herdeiros declares who the heirs are. The head of household reports the death and transferred assets. The inheritance process registers assets for the heirs.
What does probate in Portugal involve?
An estate with assets, beneficiaries or formalities in Portugal moves through a fixed set of steps. The heirs are identified through the habilitação de herdeiros. The cabeça de casal or a taxable beneficiary files the Imposto do Selo death declaration. The estate is partitioned where the interested parties agree and goes through inventory proceedings where they do not. Inherited property is registered in the heirs’ names.
An estate is cross-border when it involves a foreign will, more than one nationality or assets in more than one country. Regulation (EU) 650/2012 then sets the succession framework. The sections below follow the order of the steps.
- The heirs obtain the habilitação de herdeiros, which identifies them from the civil, family and succession documents.
- The cabeça de casal or a taxable beneficiary files the Imposto do Selo death declaration with the Autoridade Tributária e Aduaneira.
- The interested parties partition the estate by agreement, or the estate goes through inventory proceedings when they disagree.
- The heirs register the inherited property on the inheritance or partition documents.
- Regulation (EU) 650/2012 decides which law governs a cross-border estate.
How does the heirs’ declaration work?
Justiça describes a habilitação de herdeiros as the document that declares who the heirs are. The civil, family and succession documents are the basis for it. The deceased’s last domicile, will, family position and estate records are read against the applicable succession framework.
Justiça states that the habilitação itself has no deadline. A separate tax deadline can still apply, and an asset may need the document before it can move through the next estate step.
How is the Imposto do Selo death declaration filed?
Article 26 of the Código do Imposto do Selo requires the filing to identify the deceased, the relevant dates and places, the successors, their relationships and the transferred assets. The same article requires the cabeça de casal or taxable beneficiary to file by the end of the third month after the tax obligation arises. The filing goes to the Autoridade Tributária e Aduaneira.
Article 6(e) of the Código do Imposto do Selo exempts a spouse or civil partner, descendants and ascendants from item 1.2 on gratuitous transfers. Item 1.2 of the Tabela Geral do Imposto do Selo, checked on 18 September 2026, sets the rate at 10% for taxable gratuitous acquisitions. The exemption or the taxable treatment is set for each beneficiary and asset.
How are liabilities, partition and inventory handled?
The assets and liabilities of the estate are recorded before partition. Loan, tax, expense and creditor information gives the estate position. The agreed partition follows from that record.
Justiça states that an inheritance proceeds through inventory proceedings when the interested parties do not agree. Articles 2050 to 2053 of the Código Civil govern acceptance of an inheritance, including acceptance for the benefit of inventory.
How is inherited property registered?
Justiça states that the inheritance service can register assets in all heirs’ names or, after partition, for the heirs to whom the assets are adjudicated. The documents that identify the heirs come first. The habilitação, any agreed partition and the registration basis for each inherited property follow from them.
The Regulamento Emolumentar dos Registos e Notariado, checked through the IRN costs page on 18 September 2026, adds EUR 30 for each additional property in the applicable multi-property registration process. The schedule’s conditions and ceiling apply.
Which law applies to a cross-border estate?
Article 21 of Regulation (EU) 650/2012 generally points to the law of the state where the deceased had habitual residence at death. Article 22 allows a person to choose the law of a state whose nationality they hold, subject to the Regulation’s conditions.
The deceased’s last habitual residence and any express choice of national law in the will therefore decide which law applies. The evidence is the will, the foreign civil records and documents showing where the deceased lived. Documents issued outside Portugal belong in the same file.
Documents the authority asks for
The Imposto do Selo death declaration under Article 26 identifies:
- the deceased
- the relevant dates and places
- the successors and their relationships
- the transferred assets
The habilitação de herdeiros is prepared from the civil, family and succession documents. A cross-border estate adds the will, foreign civil records and documents showing where the deceased lived.
Which official fees apply?
| Procedure | Official fee |
|---|---|
| Habilitação de herdeiros | EUR 150 |
| Habilitação with asset registration | EUR 375 |
| Habilitação with partition and registration | EUR 425 |
| Each additional property in a multi-property registration process | EUR 30 |
These amounts come from the Regulamento Emolumentar dos Registos e Notariado, checked through the IRN costs page on 18 September 2026. The exact amount depends on the procedure and the assets. The schedule’s conditions and ceiling apply to the additional-property fee.
How long does probate take?
No fixed period applies. The timeline follows the available civil records, the tax declaration, the habilitação, any partition and the assets that require registration.
Probate takes longer when documents come from another country, beneficiaries or assets are not fully identified, liability records remain incomplete or the interested parties disagree.
Common questions
What is a habilitação de herdeiros?
Is there a deadline for the habilitação de herdeiros?
What does a habilitação de herdeiros cost?
Who files the Imposto do Selo death declaration and when?
Who pays Portuguese Stamp Duty on an inheritance?
Can inherited property be registered during the inheritance procedure?
Which law applies to a cross-border inheritance?
Can I accept an inheritance subject to an inventory review?
What happens when the interested parties do not agree?
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.