UK-Portugal Tax Advice
UK-Portugal tax advice examines Portuguese residence and UK income for people living between the two countries. Article 21 of the 2025 convention provides for Portugal to credit qualifying UK tax, and we review how that relief applies.
First conversation free Reply within one business day
Who Needs UK-Portugal Tax Advice
- You live between the UK and Portugal and need your Portuguese tax residence assessed from the underlying facts.
- You receive UK income while resident or potentially resident in Portugal and need the applicable treaty article identified.
- You sold or plan to sell an asset with a UK-Portugal connection and need the gains position reviewed.
- You need Portuguese and UK filing work mapped for the same income and tax year.
You need only UK domestic tax work with no Portuguese residence, income, asset or filing connection. Your case falls outside this Portugal engagement.
What's Included in UK-Portugal Tax Advice
You get a quote in writing before any work starts.
- Residence analysis. A certified accountant reviews your Portuguese residence position under Article 16 of the CIRS.
- Treaty analysis. A certified accountant identifies the applicable UK-Portugal convention and tests the relevant article against each income or gain.
- Foreign-tax-relief review. A certified accountant reviews the convention's Portugal-side relief mechanism against the UK tax and supporting evidence.
- Income mapping. A certified accountant separates employment, pension, investment, property, business and other income before applying the relevant rules.
- Capital-gains review. A certified accountant reviews the disposal under Article 10 of the CIRS and the applicable convention article.
- Filing support. The agreed Portuguese compliance work is prepared, and the UK information that requires HMRC review is identified.
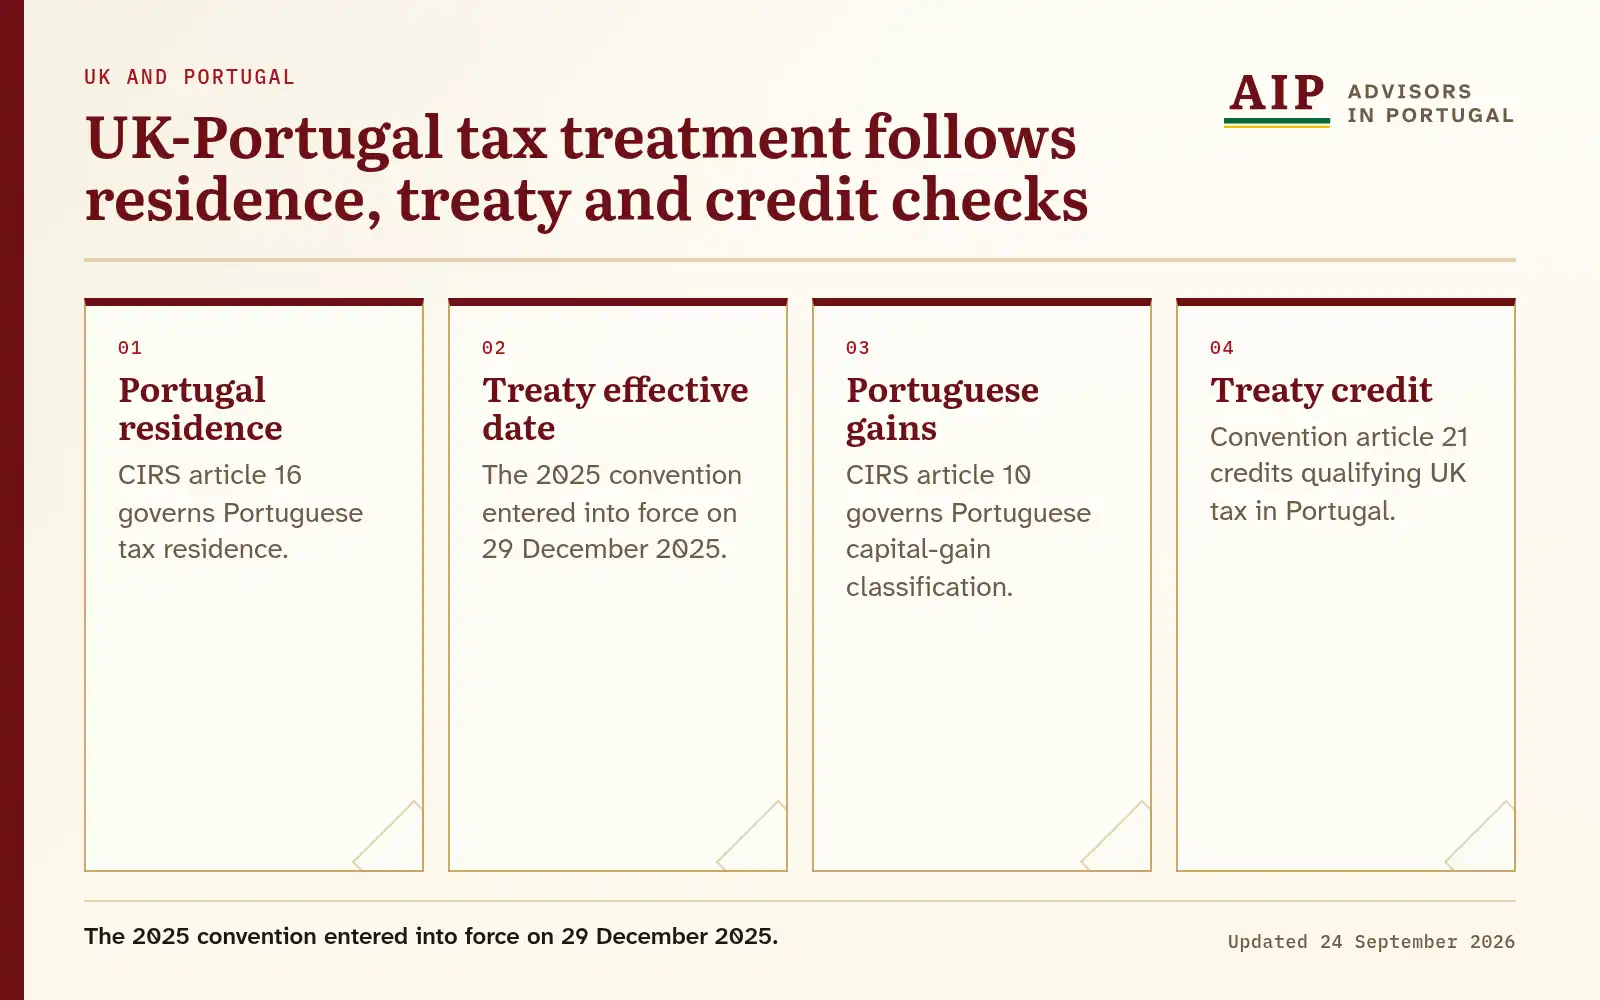
Diagram text version
CIRS article 16 governs Portuguese tax residence. The 2025 convention entered into force on 29 December 2025. CIRS article 10 governs Portuguese capital-gain classification. Convention article 21 credits qualifying UK tax in Portugal.
What You'll Need to Provide
- Residence timeline
- Your dates in Portugal and the UK, homes, household facts and any Portuguese tax registration.
- Income schedule
- Employment, pension, investment, rental, business and other income by country and tax year.
- Tax paid records
- UK and Portuguese assessments, withholding certificates, payment evidence and available relief claims.
- Asset and disposal records
- Purchase, improvement, valuation, sale and transaction-cost documents for relevant disposals.
- Treaty and status facts
- Citizenship, domicile or status information and the facts relevant to the applicable convention article.
- Prior filings
- Portuguese and UK returns, notices and correspondence for the periods under review.
How UK-Portugal Tax Work Is Handled
A certified accountant handles the tax compliance filings the engagement requires and flags treaty, residence, gains, pension and wealth-planning questions along the way.
-
Portuguese residence review
A certified accountant maps your presence, homes and household facts against Article 16 of the CIRS.
-
Income and gains inventory
A certified accountant separates each amount by type, source country, payment date and relevant tax year.
-
UK-Portugal convention analysis
A certified accountant identifies the convention and article that apply to each agreed income or gain.
-
Foreign-tax-relief evidence
A certified accountant compares the claimed UK tax with the convention mechanism and the available payment records.
-
Portuguese tax calculation
A certified accountant applies the verified residence, income, gains and treaty analysis to the agreed Portuguese work.
-
Portugal and UK filing map
The agreed Portuguese filings and the UK information that needs HMRC review are identified.
Timing and Possible Delays
Set by the residence facts and filing years
The work is planned around your residence history, income categories, disposals, tax-paid evidence and relevant filing periods.
What delays it
The work takes longer when travel dates, income records, acquisition costs, tax payments, treaty facts or prior returns are incomplete.
What to prepare now
You gather your residence, income, tax-paid, asset, treaty-status and prior-filing records before the work begins.
Residence Evidence, Treaty Analysis and Filing Records
Residence file for the relevant tax year
You keep a dated travel calendar, home records, household evidence and tax registrations for each period under review. A certified accountant uses that file to test residence without relying on a move date or mailing address alone.
Evidence behind the treaty position
You separate each income or gain by payer, source country, payment date and tax year, and you keep the contract or statement that identifies its character. A certified accountant can then connect the relevant convention article to the documented amount and its effective date.
Reconciliation before the Portuguese filing
You retain the UK assessment, withholding certificate and payment evidence beside the corresponding Portuguese income record. A certified accountant reconciles the currencies, periods and amounts before using the UK tax in the agreed Portuguese calculation.
Set out your UK-Portugal tax position
Describe where you lived, what income and gains arose, which taxes you paid and which returns have been filed.
Common questions
How is Portuguese tax residence determined?
Which UK-Portugal tax treaty applies in 2026?
When did the new convention become effective in Portugal?
Does the treaty apply in the same way to every type of income?
Can UK tax be relieved in Portugal?
How are UK-connected capital gains reviewed in Portugal?
Does HMRC still need to review the UK position?
Which filing dates apply?
Which documents support a cross-border tax review?
How is my UK-Portugal tax work handled?
How the Service Works
-
One team for the whole case.
One team is the single point of contact across residence, treaty, income, gains, filing and wealth-planning questions.
-
English or Portuguese.
English or Portuguese, whichever you are most comfortable in.
-
A quote in writing before work starts.
You get a quote in writing before any work starts. You are told plainly if your case falls outside the service.
Contact us
Your request is in
Every request is read in house. The requirements are assessed, and a reply by email sets out the appropriate next steps.
Every enquiry is read in house, and the aim is a reply within one business day.
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.