Challenging a Tax Assessment in Portugal: Routes and Deadlines
Challenging a tax assessment in Portugal can proceed by four routes, and CPPT Article 102 generally allows three months for a judicial impugnation. Notification and the end of voluntary payment start the main periods, so those dates decide which challenges remain open.
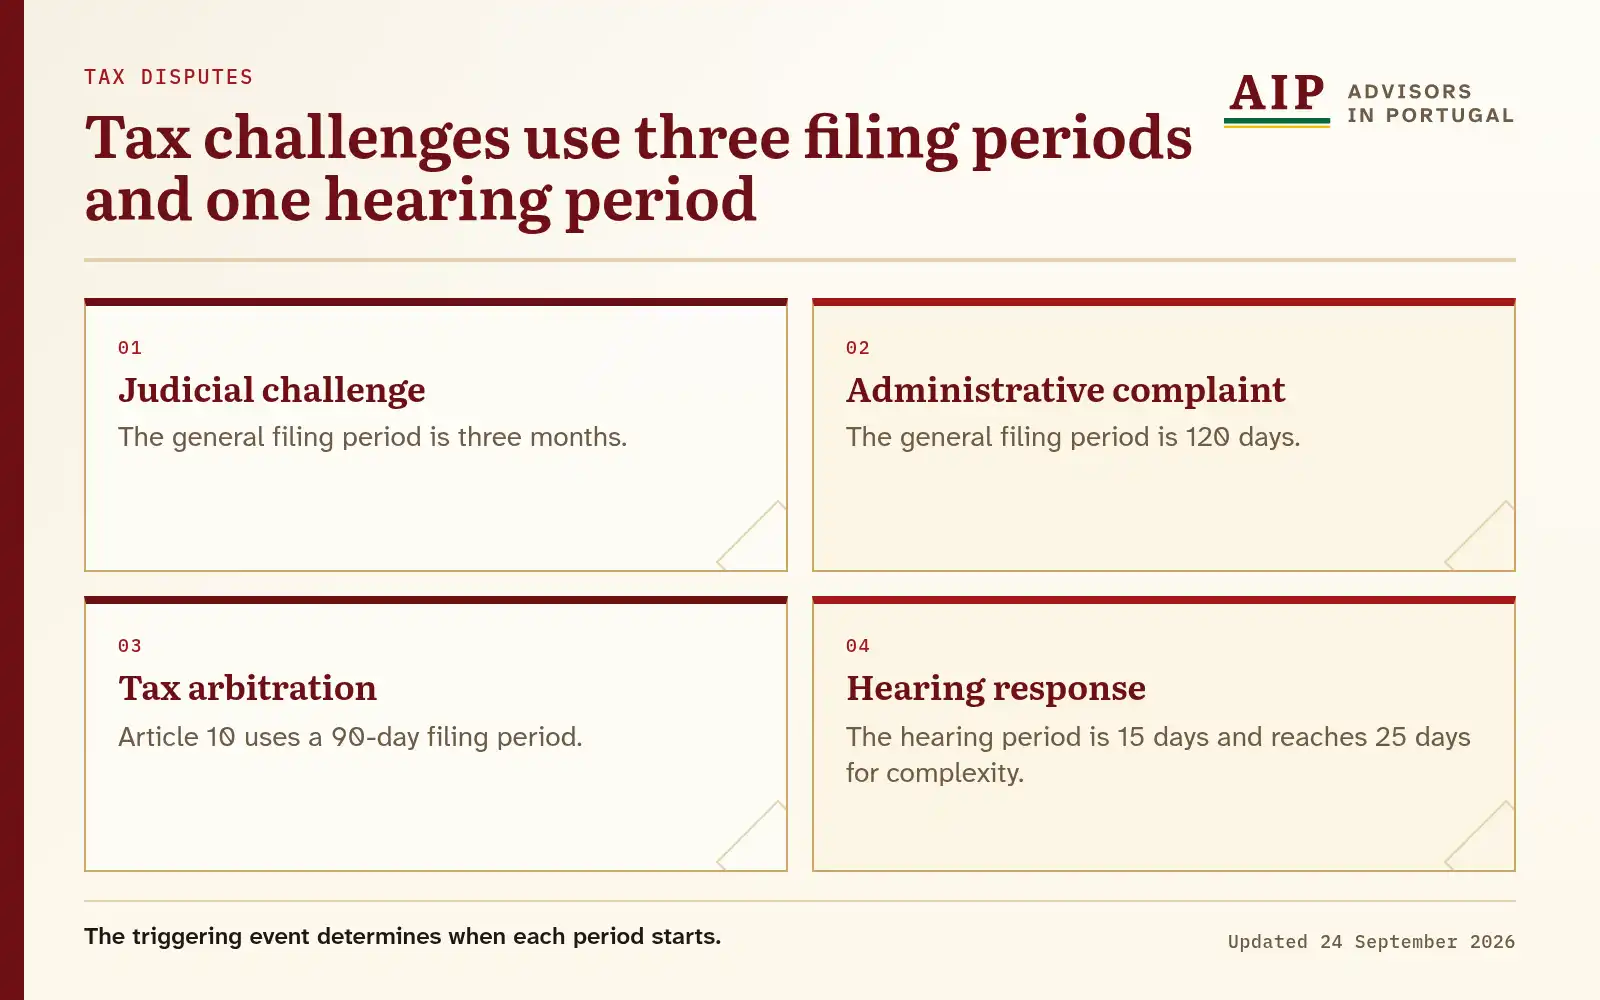
Diagram text version
The general filing period is three months. The general filing period is 120 days. Article 10 uses a 90-day filing period. The hearing period is 15 days and reaches 25 days for complexity.
Which routes can challenge a tax assessment?
Portuguese law gives four routes against a tax act. The act can be an assessment, a self-assessment, a withholding, a payment on account, an enforcement or another act of the tax authority.
| Route | Where it is filed |
|---|---|
| Reclamação graciosa | The local Serviço de Finanças |
| Hierarchical appeal | The author of the act, after a complaint is refused in whole or in part |
| Judicial impugnation | The competent tax court |
| Tax arbitration | The Centro de Arbitragem Administrativa, under the RJAT |
The remedy available depends on the act and on the CPPT deadlines that apply to it. The sections below set out each deadline and the questions that run alongside it: hearing, limitation, interest and enforcement.
What deadline applies to each route?
| Route | Period | Source |
|---|---|---|
| Judicial impugnation | 3 months | CPPT Article 102 |
| Reclamação graciosa | 120 days | CPPT Article 70 |
| Hierarchical appeal | 30 days from notification | CPPT Article 66(2) |
| Tax arbitration request | 90 days | RJAT Article 10(1)(a) |
The judicial-impugnation period runs from an event connected with the tax act, such as notification or the end of the voluntary-payment period. The reclamação graciosa period runs from the same Article 102 events, subject to special rules. A complaint may be filed with the local tax service for the domicile, the property or the assessment, and it may be filed electronically.
The date of notification, the voluntary-payment date and any hearing, refusal, appeal or enforcement date therefore decide which period applies. A service record gives the evidence for each of those dates.
How does the hearing before a tax decision work?
LGT Article 60 gives a 15-day hearing period before a tax decision. The tax authority may extend it to a maximum of 25 days according to complexity.
The taxpayer’s response to the draft decision sets out the facts and the law, together with the evidence for each contested point. That evidence can include returns, calculations, invoices, accounts, contracts and correspondence with the authority.
How long can the tax authority assess and collect?
Two limitation periods bear on a tax dispute.
- Assessment. LGT Article 45 generally gives the authority four years to validly notify a tax assessment, subject to the tax and statutory exceptions.
- Prescription of the debt. Tax debts generally prescribe after eight years under LGT Article 48. The counting rules and the interruption or suspension causes depend on the tax and on the enforcement history.
A limitation date can only be calculated from the full procedural history: the tax, the notices and the enforcement file.
How does tax arbitration work?
Tax arbitration is the fourth route and follows the RJAT, Decreto-Lei n.º 10/2011. RJAT Articles 2 and 3 set the subject matter that can go to arbitration. They do not state one general monetary threshold or a universal filing fee.
Article 10(1)(a) gives a 90-day period for the arbitration request. The applicable cost schedule of the Centro de Arbitragem Administrativa (CAAD) must be confirmed before a request is filed.
Which interest and payment rules apply during a dispute?
LGT Article 44 applies mora interest when tax is not paid by the legal deadline. It doubles the rate for the specified post-judgment period. The payment date is the one on the assessment or enforcement document unless a special rule applies.
The file that shows the payment position includes payment records, enforcement documents, security, interest notices and any instalment or suspension material.
Who may represent a taxpayer in a tax dispute?
Reserved legal acts, including court representation, are carried out by a lawyer registered with the Ordem dos Advogados or by a solicitador. CPPT Article 5(2) limits tax-mandate work where legal questions are raised. The representative route depends on the proceeding and the issues.
What belongs in the dispute file?
Notice, trigger and evidence file
The tax act, the service record, the voluntary-payment date and the procedural history decide the remedy. The returns, calculations, contracts, correspondence and accounting records support the grounds. The hearing response and the evidence for each contested point belong in the same file.
The timeline is harder to fix where the notice is incomplete, the service dates conflict, several entities hold the records or enforcement has already begun.
Limitation, interest and enforcement
The assessment and prescription periods are reconstructed from the tax, the notices and the enforcement file. Interest and payment obligations continue to run during the dispute.
Decision reasoning and arbitration trigger
New elements raised in the hearing must be addressed in the reasoning of the decision under LGT Article 60. The hierarchical decision, or the expiry of the period for that decision, is the point from which the RJAT Article 10 filing period becomes relevant.
Common questions
How long is the deadline for a judicial impugnation?
What is the deadline for a reclamação graciosa?
How long is the deadline for a hierarchical appeal?
What hearing period applies before a tax decision?
How long can the tax authority assess?
When does a tax debt prescribe?
Is there a threshold or fixed fee for tax arbitration?
Who can represent a taxpayer in a tax dispute?
What interest and payment date apply while a dispute is pending?
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.