Rental Income Tax in Portugal: Category F Rates and Filings
Rental income tax in Portugal is 25% for residential rents and 28% for other Category F rental income under Código do IRS Article 72. Landlords report the previous year's rents on Model 3 with the Category F annex between 1 April and 30 June.
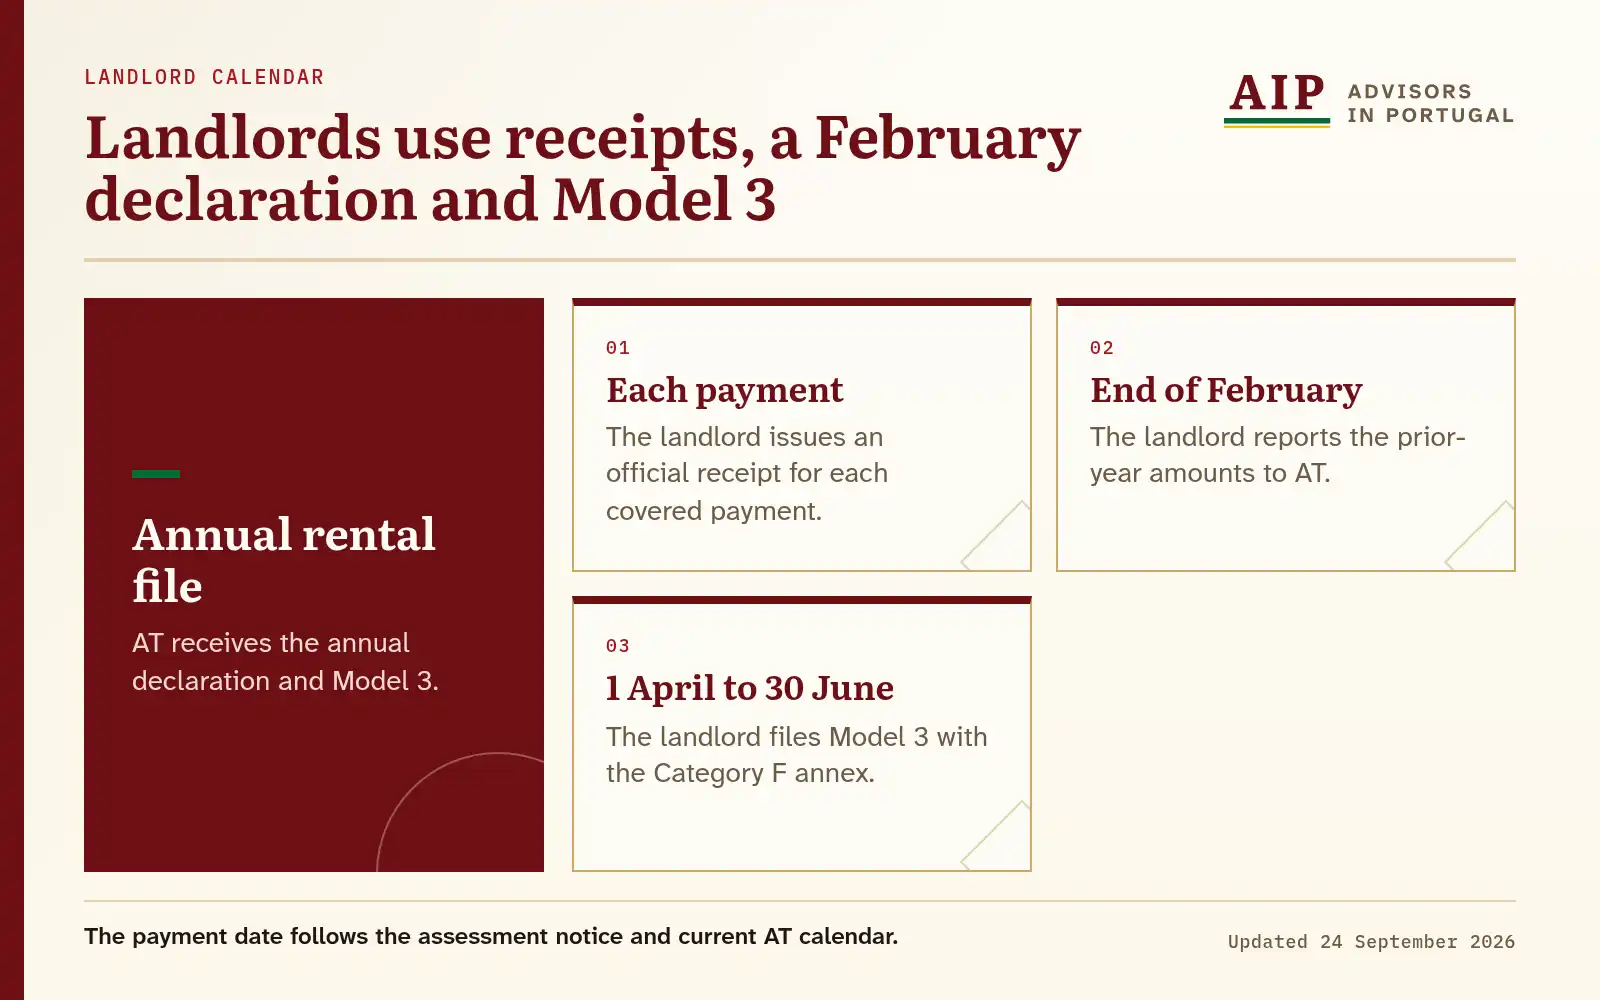
Diagram text version
The landlord issues an official receipt for each covered payment. The landlord reports the prior-year amounts to AT. The landlord files Model 3 with the Category F annex.
Código do IRS Articles 8, 41 and 72 govern taxable rents, deductions and the 25% or 28% Category F rates.
Which payments are Category F rental income?
Código do IRS Article 8(1) treats rents from rural, urban and mixed Portuguese property as Category F income when paid or made available to the holder and the holder has not chosen Category B treatment. The property, recipient and activity are identified before an IRS return is prepared, and the lease is compared with the payment record and the elected tax category.
Article 8(2) extends the category to amounts for use of the property and related services, machinery or furniture hire, sublease spreads and certain use of common parts or temporary rights of enjoyment. Each amount received under the lease is listed separately, and the contract description is compared with the receipts so a furniture charge or sub-rent is classified under the provision that covers it.
A landlord may receive ordinary rent, a reimbursement or another contractual payment. The contract and the invoice or receipt that explains each amount are preserved. Category F is distinct from a business activity taxed in Category B where the arrangement and election require it. The property record, lease and account statement should describe the same underlying transaction.
Which costs can reduce taxable rent?
Código do IRS Article 41(1) allows expenses actually borne and paid to obtain or secure Category F income, including rent insurance under the article’s conditions. The landlord retains invoices, proof of payment and the link between each expense and the rental property, and compares the documents with the permitted category before claiming a deduction.
Article 41 excludes financial costs, depreciation and furniture, appliance, comfort or decoration items. Those amounts are kept separate from potentially deductible maintenance or administration costs. Each invoice is matched to the paragraph that applies and to the rental income being reported. An accounting entry should be traceable to the supplier and payment.
The tax return should reflect the actual year and property involved. A schedule of income and expenses by property, including invoices for work and insurance, is reconciled with rent receipts and the Article 41 exclusions. A furnished property may produce several kinds of charges, so the contract and payment records should identify them.
What rate applies to residential and other rents?
Código do IRS Article 72(2) taxes residential lease income at an autonomous 25% rate, while Article 72(1)(e) sets 28% for property income outside that residential rule. The lease’s actual housing purpose and the income category determine the rate, so the contract and tax return are compared with the relevant paragraph.
Article 72 provides lower rates for qualifying permanent-housing leases of at least five years. A lease lasting five to under ten years receives a ten-percentage-point reduction; a qualifying lease of ten to under twenty years receives fifteen points. The signed term and any renewal documents are preserved, and the reduction follows the actual contractual period and the statutory exceptions.
A rate reduction follows its own conditions beyond the property’s address. The housing purpose, duration and reporting records are kept together, and an earlier return is compared with the contract used to claim the rate. The 25% residential rate is the starting rule, and Article 72 determines whether a lower qualifying rate applies.
How does lease duration affect a reduced rate?
Código do IRS Article 72(3)-(5) ties reduced rates to the stated duration of a permanent-housing lease and its qualifying renewals. A five-to-under-ten-year contract receives a ten-point reduction, with two further points for each renewal of equal duration up to the statutory cap. Each signed renewal and the date it took effect are kept.
Article 72(23)-(24) places conditions on the benefit, including a rent-limit test for certain contracts. The monthly rent is compared with the applicable local limit before a long-term reduction is applied, and the calculation is retained with the annual return.
Evidence of a termination and its reason is preserved with the original lease, because a change to the contract affects whether the rate claimed in an earlier year remains available. A renewal should be matched to its own term and payment history, because the reduced rate depends on what was agreed and maintained.
Which receipts and annual landlord report are required?
Código do IRS Article 115(5)(a) requires a Category F holder to issue an official-model rent discharge receipt for amounts received under the listed Article 8(2) categories. Article 115(5)(b), as changed by Decreto-Lei n.º 49/2025 with effect from 1 July 2025, requires the annual official-model income declaration by the end of February for the previous year. Each receipt and the annual acknowledgement are kept.
The rent receipt should correspond to the payer, property and amount actually received. Receipts are reconciled with bank movements and the lease terms before the annual declaration, so a missing receipt or a payment recorded in the wrong year shows up before filing.
A landlord communicates the lease through the applicable Portal das Finanças procedure. The communication acknowledgement is retained with the signed contract and later changes, and those records support the Article 115 reporting duty and the rate claimed under Article 72. The filing procedure for the particular lease supplies its own operative steps.
When is rental income included in Model 3?
Código do IRS Article 60(1) sets 1 April to 30 June for electronic delivery of the annual Model 3 return, including Portuguese Category F income in its applicable annex. The final day applies even when 30 June is not a working day. The previous year’s receipts, expense documents and lease changes are assembled before that filing window.
The return brings together the property income and other items relevant to the taxpayer’s assessment. The Category F annex is reconciled with the Article 115 annual report and receipts, and a copy of the submitted Model 3 and the assessment notice is kept. The notice supplies the payment reference and due date for that assessment.
A filing deadline and a tax payment date answer different questions. The issued assessment is read before an amount is paid, and the declared income, claimed deductions and rate are compared with the calculation shown by Autoridade Tributária e Aduaneira. The correction route depends on the actual return and assessment.
How is a non-resident landlord treated?
Código do IRS Article 18(1)(h) treats income from property situated in Portugal as Portuguese-source income. Article 130(1) addresses the tax representative for a non-resident receiving income subject to IRS, under its stated conditions. The taxpayer’s tax residence and the property income are identified before a representative is appointed or the return is filed.
Article 72 contains the relevant autonomous-rate rules for property income. The Portuguese lease, receipts and any foreign residence evidence are kept with the tax file, and the Article 72 rate is compared with any election available to the taxpayer. A certified accountant may assist with filings.
A non-resident owner may have tax obligations in more than one country. The Portuguese-source amount is calculated first, and the foreign residence and tax documents show whether another jurisdiction’s treatment creates a separate filing or credit question. The Portuguese property location supplies the source rule under Article 18.
How do foreign-tax credits arise?
Código do IRS Article 81(1)-(2) limits a foreign-tax credit for aggregated income to the lower of foreign income tax paid and the proportional Portuguese IRS assessment under the provision. The foreign tax assessment, proof of payment and income allocation are kept if a credit is claimed, and they are compared with the Portuguese return.
Autoridade Tributária e Aduaneira issues the Portuguese assessment and receives the return and supporting tax communications. Its notices and the submitted documents are preserved, and a mismatch between receipts, deductions and the final calculation is checked against them. The relevant deadline follows the type and date of the actual notice.
Foreign tax paid on an item should be tied to the same income period and taxpayer. The source country, tax paid and income involved are identified, and Article 81’s cap applies to that evidence, which leaves any excess outside the Portuguese credit. The credit calculation is a separate step from identifying Category F income.
How should furnished, sublet or local lodging income be classified?
Código do IRS Article 8(2)(b)-(c) includes specified furniture or machinery hire and sublease spreads in Category F. Article 41(6) denies deductions for the difference between sub-rent received and rent paid by a sublessor. The contract and payments that give rise to each amount are identified before a cost is claimed.
A furnished lease may include property rent and other charges. The inventory, contract and separate receipts for each payment are retained, and the facts are compared with Category F and any elected or applicable Category B activity. The tax treatment follows the actual use and business arrangement.
Alojamento Local activity has its own registration and tax rules. Registration and booking records are kept where that activity is carried on, so the lodging income stays distinct from a long-term housing lease and reconciles to the appropriate return. Documentary evidence is retained for every deduction claimed under Article 41.
Common questions
Does Category F include compensation for lost rents?
Can AIMI be deducted from Category F rents?
What reduction applies to a lease of at least 20 years?
What happens when a qualifying long lease ends early because of the landlord?
Does a deposit require an official rent receipt?
May an eligible EU or EEA non-resident elect resident-table treatment?
The information on this page is checked against official sources and reviewed regularly. It is corrected when the law or official guidance changes, as the Editorial Standards describe.